HVAC Business Valuation: Free HVAC Valuation Calculator. How Much Is My HVAC Business Worth in 2026?
HVAC business valuation, 2026: owner-run shops sold for 1.99x to 3.33x SDE (BizBuySell); firms above $1M EBITDA price on EBITDA, from 5.7x (GF Data) to north of 10x past $10M EBITDA (PKF O’Connor Davies).
Key takeaways
- Broker-sold HVAC businesses (2021 to 2025) priced at 1.99x to 3.33x SDE for the middle half, median 2.58x (BizBuySell).
- PE-backed specialty trade deals (NAICS 238) averaged 5.7x EBITDA at $10M to $25M of enterprise value and 8.2x at $100M to $500M (GF Data, April 2025).
- Comfort Systems USA paid $120.6M for J&S Mechanical on $12M to $15M of expected EBITDA: 8.0x to 10.1x, per its Form 10-Q.
- First Page Sage publishes 5.7x to 7.9x SDE for residential HVAC, over twice the closed-deal median; treat it as a ceiling.
- Platform multiples near 17x to 18.5x are HomePros press reports, not filings, and do not price add-ons.
How much is an HVAC business worth in 2026?
An HVAC business is worth a multiple of normalized earnings, and the multiple rises with size. Broker-sold shops closed at a 2.58x SDE median on BizBuySell. PE deals of $10M to $500M enterprise value averaged 5.7x to 8.2x EBITDA in GF Data’s NAICS 238 cohort, and PKF O’Connor Davies puts high-visibility HVAC services deals north of 10x.
| Source | What it measures | Multiple | Basis | Date |
|---|---|---|---|---|
| BizBuySell | Broker-sold HVAC businesses | 1.99x to 3.33x (median 2.58x); 0.38x to 0.74x revenue | SDE | 2021 to 2025 |
| GF Data | PE deals, NAICS 238: $10M to $25M / $25M to $50M / $50M to $100M / $100M to $500M TEV | 5.7x / 6.1x / 7.1x / 8.2x | EBITDA | Q4 2024 |
| Breakwater M&A | Owner-operated to platform-ready bands | 3x to 4x up to 6x to 7x | EBITDA | Feb 2026 |
| Comfort Systems USA 10-Q | J&S Mechanical purchase | 8.0x to 10.1x | EBITDA | Feb 2024 |
| PKF O’Connor Davies | High-visibility HVAC services deals | North of 10x | EBITDA | Aug 2025 |
| HomePros | Platform recaps, unconfirmed | About 17x to 18.5x | EBITDA | 2024 to 2026 |
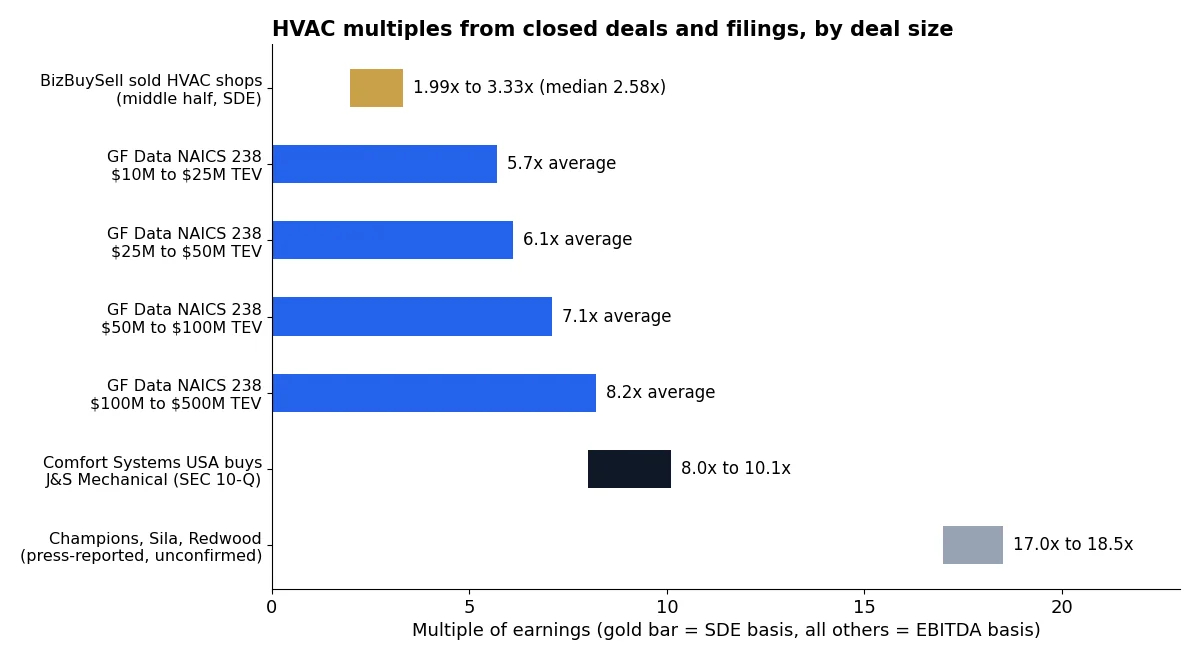
SDE adds the owner’s pay back; EBITDA deducts a market salary for that role, so EBITDA multiples read higher. Our guide to what SDE means in business valuation shows the math.
How does the free HVAC business valuation calculator work?
The calculator starts at 4.0x to 4.8x earnings by residential versus commercial mix, then adjusts for revenue size, margin, new construction share, maintenance agreement share, owner reliance, software, location and growth, capping the midpoint at 9.5x. Enter earnings after a normal salary for the owner role. It returns a screening range, not a Quality of Earnings result.
| Illustrative profile | Key inputs | Calculator result | Closed-deal check |
|---|---|---|---|
| Owner-operator, residential | $1.5M revenue, $200,000 earnings, 10% agreements, owner-reliant | 4.0x to 5.1x: $800,000 to $1,020,000 | $300,000 SDE (plus an illustrative $100,000 owner salary) at BizBuySell rates: $597,000 to $999,000 |
| Established residential | $4M revenue, $600,000 EBITDA, 20% agreements, strong team, ServiceTitan | 5.8x to 7.0x: $3,450,000 to $4,210,000 | Breakwater 5x to 6.5x for balanced to service-led firms |
| Worked example below | $14M revenue, $3.28M adjusted EBITDA, 10% agreements, major metro | 6.2x to 7.5x: $20,240,000 to $24,680,000 | GF Data 5.7x gives $18.7M |
Thinking about selling your HVAC business?
Skip the formulas. A 15-minute confidential valuation consultation gives you a real valuation range and tells you which buyers would compete for your business. No cost, no obligation.
How do I value my HVAC (heating and air conditioning) business?
Value a heating and air conditioning business in six steps: normalize 12 months of earnings, choose SDE or EBITDA, defend each add-back, apply a closed-deal multiple for your size, cross-check against revenue, then convert value into cash at closing. In the J&S Mechanical deal, 15.8% of the $120.6M price came as notes and an earnout.
- Normalize. Use the trailing 12 month profit and loss and three years of tax returns, so summer receivables do not distort the base.
- Pick the basis. Under $1M of SDE with the owner running calls, use SDE; above $1M of EBITDA, deduct a market salary and use EBITDA.
- Defend add-backs. Tie each one to a ledger line and invoice; see the adjusted EBITDA add-backs guide.
- Apply a closed-deal multiple. 1.99x to 3.33x SDE (BizBuySell) below $1M; 5.7x to 8.2x EBITDA (GF Data) for PE-sized deals.
- Cross-check revenue. BizBuySell’s 0.38x to 0.74x revenue range flags a margin or add-back error.
- Convert to proceeds. J&S took $100.0M cash, a $1.587M working capital adjustment, $10.0M of notes and a $9.052M earnout; read the working capital peg guide.
What is an HVAC business worth that makes $300,000 a year or $1 million in sales?
With BizBuySell’s 2021 to 2025 HVAC medians, $300,000 of SDE prices at $597,000 to $999,000, centred on $774,000. A $1,000,000 revenue shop at the 20.5% median SDE margin earns $205,000 of SDE and prices near $528,900; the 0.56x revenue median gives $560,000.
| Scenario | Arithmetic | Result |
|---|---|---|
| $300,000 a year of SDE | $300,000 x 1.99 / 2.58 / 3.33 | $597,000 / $774,000 / $999,000 |
| $1,000,000 in sales | $1,000,000 x 20.5% = $205,000 SDE; x 2.58 | $528,900 (0.56x revenue: $560,000) |
| $1,000,000 in sales at the 2025 margin | $1,000,000 x 24.8% = $248,000 SDE; x 2.58 | About $640,000 |
| $500,000 in sales | $500,000 x 20.5% = $102,500 SDE; x 2.58 | $264,450 (0.56x revenue: $280,000) |
BizBuySell’s median SDE margin rose from 17.1% in 2021 to 24.8% in 2025, so revenue multiples undervalue high-margin shops; sales closed at 92% to 94% of asking.
Why do published HVAC multiples disagree with closed deals?
Most HVAC multiple tables online are advisor estimates, not closed transactions. First Page Sage lists 5.7x to 7.9x SDE for residential HVAC from unnamed “private equity networks, expert interviews, and proprietary databases,” while BizBuySell’s reported sales sit at a 2.58x SDE median.
| Claim | Who says it | Closed or filed figure | Gap |
|---|---|---|---|
| Residential HVAC sells for 5.7x to 7.9x SDE | First Page Sage, Feb 6, 2025 | BizBuySell: 1.99x to 3.33x SDE, median 2.58x | Lowest band is 2.2 times the median |
| $1M to $5M residential sells for 9.2x EBITDA | First Page Sage | GF Data 5.7x ($10M to $25M TEV); Breakwater 6x to 7x platform-ready | 2.2 to 3.5 turns |
| Platform-ready trades at 7x to 10x (Breakwater) | Earlier version of this page | Breakwater, Feb 3, 2026: 6x to 7x | Misquote corrected |
| HVAC platforms sell for about 17x to 20x | HomePros sources | J&S Mechanical 10-Q: 8.0x to 10.1x | Platform recap, not an add-on price |
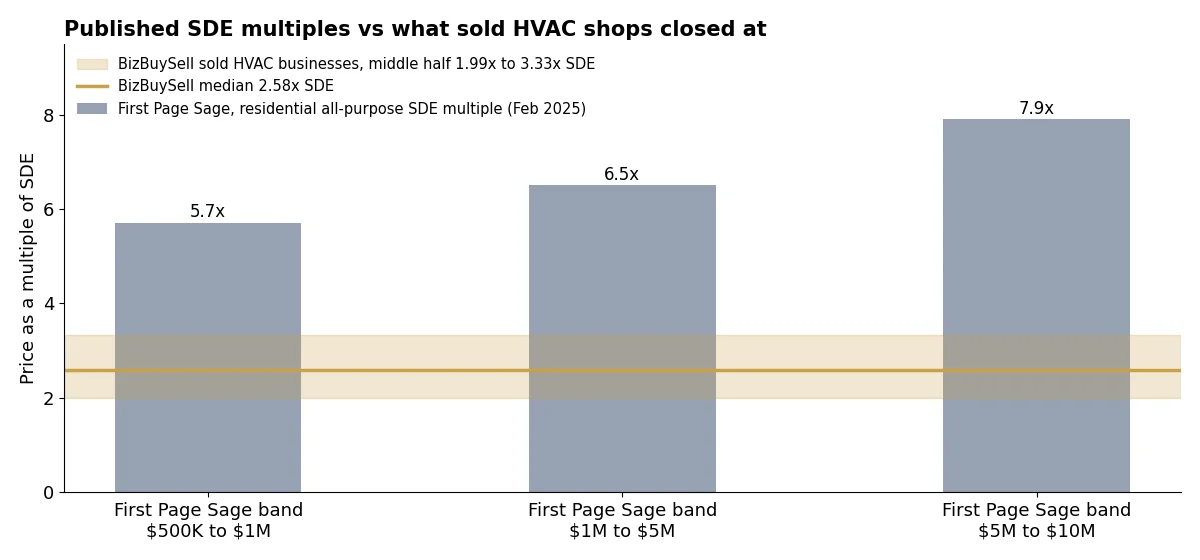
First Page Sage dates its page February 6, 2025 yet labels the data Q1 2025, a quarter ending March 31, and gives no deal count.
Which buyers pay which multiple for HVAC companies?
Strategic buyers and private equity platforms pay the EBITDA bands; individual and SBA-financed buyers pay the SDE band. Service Logic carries no multiple because no party disclosed terms, and the 18.5x Champions figure prices a $140M EBITDA platform, not its add-ons.
| Date | Buyer | Target | Figures | Multiple | Source |
|---|---|---|---|---|---|
| Feb 1, 2024 | Comfort Systems USA | J&S Mechanical, Utah | $120.6M paid; $12M to $15M expected EBITDA | 8.0x to 10.1x | 10-Q; release |
| Nov 2024 | Goldman Sachs Alternatives | Sila Services | About $1.7B; just under $100M EBITDA | About 17x | HomePros |
| May 8, 2025 | Altas Partners | Redwood Services | About $1.1B; about $65M EBITDA | About 17x | HomePros |
| Dec 2025 | Bain Capital, Mubadala | Service Logic, 140+ locations | Not disclosed | Not derivable | Bain Capital |
| Feb 17, 2026 | Blackstone | Champions Group | About $2.5B; about $140M EBITDA | About 18.5x | HomePros |
Our tracker of private equity buyers in HVAC lists the active platforms and their add-on criteria.
15-minute confidential call
Book a Call with CT Acquisitions
If you operate an HVAC business and want to know which buyer cohort would compete for your business, the 15-minute call is the easiest place to start. We tell you what range of multiples you would see, what to do in the 6-12 months before market, and what each buyer type would value most in your business. No fee to you on buy-side introductions; sell-side mandates are paid on success at closing. Sign nothing. Walk away anytime.
How do add-backs change an HVAC valuation? A worked example
Illustrative example: a hypothetical $14M revenue Texas residential HVAC company reports $3.0M of EBITDA. Nine Quality of Earnings adjustments net to +$280,000, so adjusted EBITDA is $3.28M, a 23.4% margin. Each accepted $10,000 add-back is worth $57,000 to $75,000 of price at 5.7x to 7.5x.
| Adjustment | Amount | Basis (illustrative) |
|---|---|---|
| Owner pay above a market manager rate | +$175,000 | $475,000 paid vs about $300,000 market |
| Spouse payroll above market | +$65,000 | $95,000 paid for about $30,000 of work |
| Below-market rent to owner’s property company | minus $40,000 | $90,000 paid vs about $130,000 market |
| Personal vehicles, dues, phones | +$55,000 | Personal costs booked to the business |
| Software rollout and fleet GPS | +$85,000 | One-time implementation |
| Settled employment lawsuit | +$45,000 | Resolved, non-recurring |
| Deferred fleet replacement | minus $90,000 | Fleet averages 7.4 years |
| Manufacturer rebate timing | minus $50,000 | $185,000 covered 14 months; run rate $135,000 |
| Bonuses outside policy | +$35,000 | Discretionary year-end gifts |
| Net | +$280,000 | $3,000,000 + $280,000 = $3,280,000 |
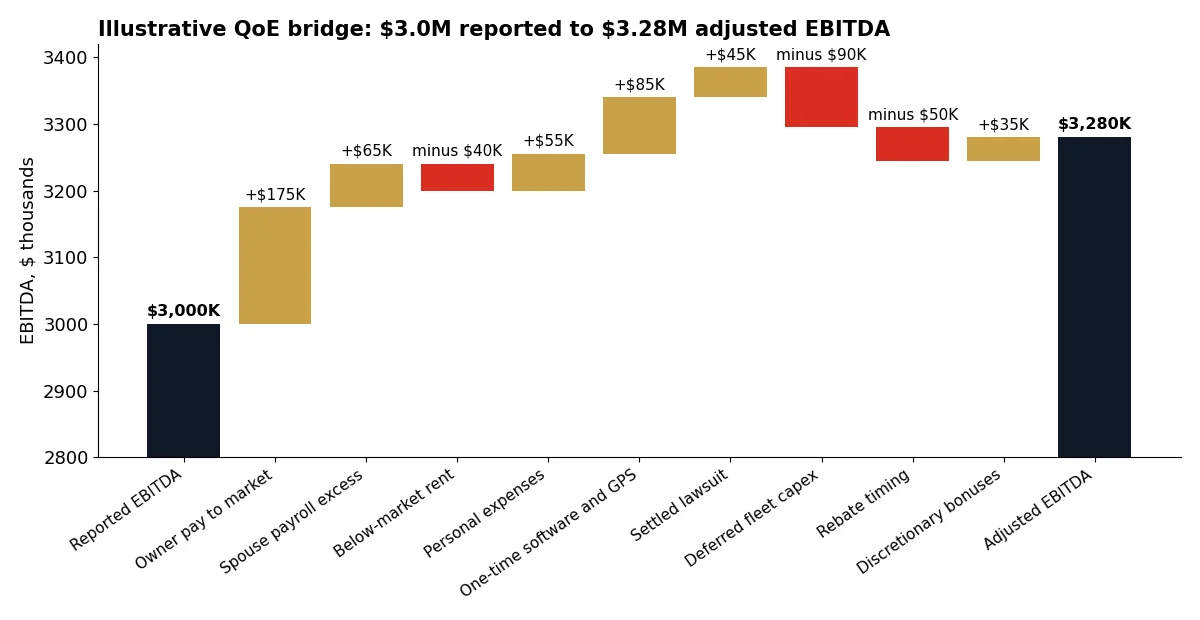
At the calculator’s 6.2x to 7.5x, $3.28M implies $20.24M to $24.68M; at GF Data’s 5.7x it implies $18.7M. Two facts here also lower the multiple: maintenance agreements at 10% of revenue and a founder who personally holds the state contractor license.
Confidential review of your business
Get a Specific Valuation for Your HVAC Business
The worked example above is illustrative. The 15-minute confidential conversation with our team is specific to your revenue, EBITDA, recurring-revenue mix, geography, license structure, and the buyers who would compete. You leave with a range, a buyer shortlist, and a 6-12 month pre-exit roadmap. No fee to you on buy-side introductions; sell-side mandates are paid on success at closing.
Start with the Free Valuation Form →
✓ No fee to you on buy-side introductions
✓ Terms in writing, before any work starts
✓ Terms in writing, before any work starts
What raises or lowers an HVAC business multiple?
Service mix, management depth and size move the multiple most. Breakwater M&A’s February 2026 bands run from 3x to 4x EBITDA for an owner-operated shop with few maintenance agreements to 6x to 7x for a platform-ready company, and PKF O’Connor Davies names $10M of EBITDA as the size that justifies significant expansion.
| Driver | Threshold | Effect | Source |
|---|---|---|---|
| Business profile | Owner-operated / installation-heavy / balanced / service-led 50%+ / platform-ready | 3x to 4x / 4x to 5x / 5x to 6x / 6x to 6.5x / 6x to 7x EBITDA | Breakwater, Feb 2026 |
| Maintenance agreements | 2,000 agreements, $400K annual revenue | Valued at 2x to 3x ($800K to $1.2M) on top; back plan EBITDA out or it counts twice | Breakwater |
| New construction | 20% to 30% of revenue is the usual limit; some buyers accept closer to 50% | Above it, fewer bidders | PKF, Aug 2025 |
| Size | $10M+ EBITDA | Critical size for multiple expansion | PKF |
| Technicians | BLS: 440,900 jobs (2025), 11% growth to 2035 | Departure risk priced into earnouts | BLS |
Commercial contracts are valued on contracted revenue, covered in the commercial HVAC business valuation guide; residential owners can follow our steps to increase HVAC business value before selling.
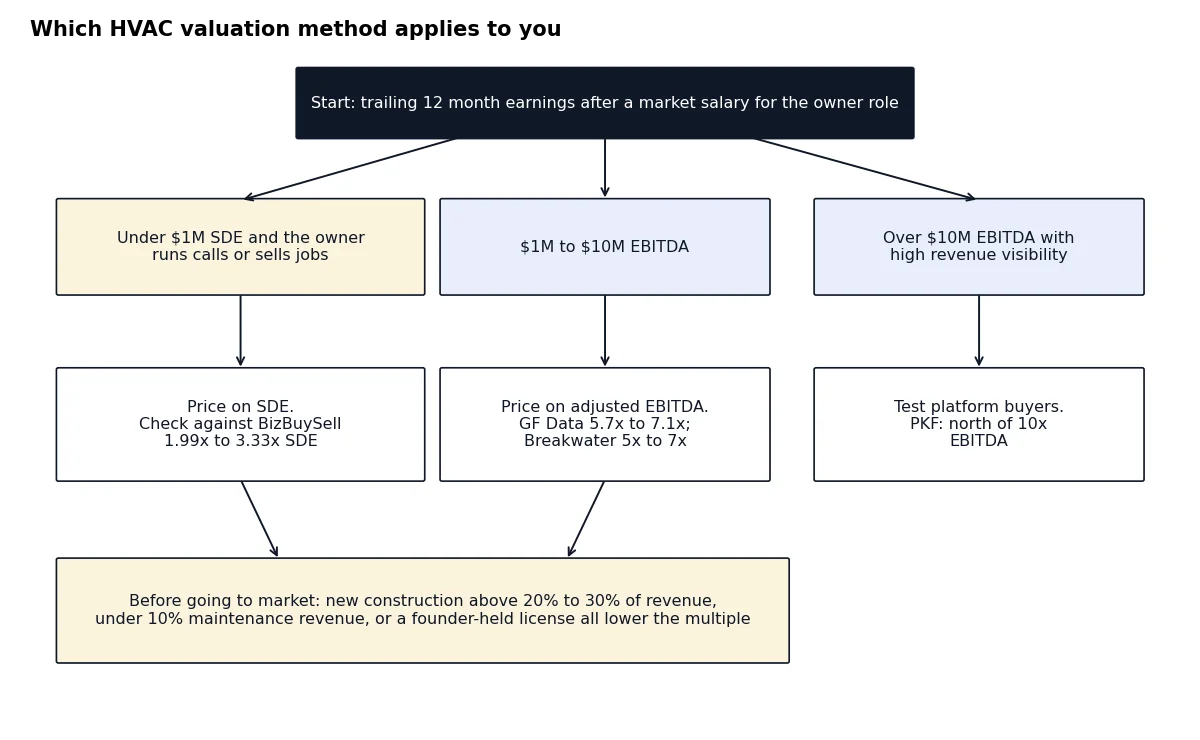
Which valuation path fits your HVAC business?
Match the method and the buyer to your earnings and operating profile. Each row gives the trigger, the action and the sourced number behind it, so you know which multiple band applies to your HVAC business before any buyer names a price in a letter of intent.
| If your situation is | Do this | Why |
|---|---|---|
| Under $1M of SDE and you still run calls | Price on SDE; test 1.99x to 3.33x | BizBuySell sold median 2.58x |
| $1M to $10M of EBITDA with a manager | Price on adjusted EBITDA; order a sell-side Quality of Earnings before the letter of intent | GF Data 5.7x to 7.1x for $10M to $100M deals |
| Agreements under 10% of revenue, 12 to 18 months before a sale | Grow the agreement base first | Breakwater: $400K of agreements worth $800K to $1.2M |
| New construction above 20% to 30% of revenue | Expect fewer bidders or a lower multiple | PKF buyer threshold |
| Over $10M of EBITDA with high revenue visibility | Test platform and strategic buyers | PKF north of 10x; J&S 8.0x to 10.1x |
Want to know what your HVAC business is worth?
Benchmarks give you a range. A 15-minute confidential call gives you a real number, based on what active buyers are paying right now and which ones would compete for your business. No cost, no obligation.
CT Acquisitions advises founder-owned businesses on sell side, buy side and exit planning with 500+ buyers. No fee to you on buy-side introductions; sell-side mandates are paid on success at closing. Start at sell your HVAC business.
How we compiled this
We compiled 12 primary or named sources in October 2026, led by a Comfort Systems USA Form 10-Q, GF Data’s Q4 2024 highlights and BizBuySell, plus the calculator’s own weights. BizBuySell blocked automated access in October 2026, so its figures carry over from our May 2026 review. Forum posts were excluded.
Frequently asked questions
How do I value my HVAC business?
Normalize trailing 12 month earnings, then apply a multiple from closed deals at your size. Under $1M of SDE, sold HVAC deals on BizBuySell priced at 1.99x to 3.33x SDE. Above $1M of EBITDA, GF Data’s NAICS 238 private equity deals averaged 5.7x to 8.2x EBITDA. Cross-check with 0.38x to 0.74x revenue.
How much is a HVAC business worth?
The median owner-run HVAC business BizBuySell recorded as sold from 2021 to 2025 went for 2.58x seller’s discretionary earnings, or 0.56x revenue. A company with $3M of adjusted EBITDA at 5.7x to 7.5x is worth about $17.1M to $22.5M, before working capital and deal terms.
How much is a business worth that makes $300,000 a year?
If the $300,000 is seller’s discretionary earnings, the middle half of sold HVAC deals on BizBuySell (1.99x to 3.33x SDE) puts the business at $597,000 to $999,000, and the 2.58x median at $774,000. If it is EBITDA after a manager’s salary, EBITDA multiples apply.
How much is a business worth with $1,000,000 in sales?
An HVAC business with $1,000,000 in sales and BizBuySell’s 20.5% median SDE margin earns about $205,000 of SDE. At the 2.58x median SDE multiple that is $528,900, and the 0.56x revenue median gives $560,000. At the 2025 median margin of 24.8%, the price is near $640,000.
Sources
- BizBuySell, HVAC valuation benchmarks, reviewed May 2026.
- GF Data, Q4 2024 highlights (April 2025), accessed Oct 2026.
- Comfort Systems USA, Form 10-Q, Q3 2024, accessed Oct 2026.
- Comfort Systems USA J&S announcement, Feb 2024, accessed Oct 2026.
- PKF O’Connor Davies, US HVAC M&A update, Aug 4, 2025, accessed Oct 2026.
- Breakwater M&A, HVAC multiples 2026, Feb 3, 2026, accessed Oct 2026.
- First Page Sage, HVAC EBITDA multiples, Feb 6, 2025, accessed Oct 2026.
- HomePros, Champions Group, Feb 17, 2026, accessed Oct 2026.
- HomePros, Sila Services, Nov 6, 2024, accessed Oct 2026.
- HomePros, Redwood Services, May 8, 2025, accessed Oct 2026.
- Bain Capital, Service Logic, Dec 2025, accessed May 2026.
- BLS Occupational Outlook Handbook, HVAC mechanics, accessed Oct 2026.

About the Author
Christoph Totter is the founder of CT Acquisitions, an M&A advisory firm working both sides of the table, headquartered in Sheridan, Wyoming. We work directly with 500+ buyers, search funders, family offices, lower middle-market PE, and strategic consolidators, including direct mandates with the largest consolidators that other intermediaries cannot access. No fee to you on buy-side introductions; sell-side mandates are paid on success at closing. Connect on LinkedIn · Get in touch
Related deep-dive M&A guides
Companion references with named transactions, mapped buyer landscapes, and operator-level diligence framing:
