
Tire Shop M&A Multiples Report 2026: Valuation Benchmarks by Size and Segment
Tire shop M&A in 2026 prices on size: IBBA’s Q2 2026 survey puts businesses under $500K at 2.0x SDE and $5M to $50M deals at 5.8x EBITDA, while priced tire chain deals ran from about $875K to $14M per location.
Key takeaways
- Main Street business sales cleared a median 2.0x SDE under $500K of price, 2.8x at $500K to $1M and 3.1x at $1M to $2M in Q2 2026 (IBBA Market Pulse Q2 2026).
- Peak Business Valuation’s tire dealership data shows 2.10x to 3.10x SDE, 2.68x to 4.89x EBITDA and 0.27x to 0.49x revenue (Peak, accessed Nov 2026).
- Mavis agreed on July 20, 2026 to buy Pep Boys, nearly 800 locations, for about $700 million in cash while Icahn Enterprises kept the owned real estate (The Shop, Jul 24, 2026).
- Big Brand Tire & Service closed a $1.625 billion recapitalization in October 2025, then agreed on July 16, 2026 to buy Belle Tire and its 180-plus stores (Modern Tire Dealer).
- Monro, the only listed US tire and service chain of scale, traded at 10.89x EBITDA and 0.72x sales on Nov 13, 2026, about $736K of enterprise value per store (Stock Analysis).
What multiples do tire shops sell for in 2026?
An owner-run tire shop sells for roughly 2.0x to 3.1x seller’s discretionary earnings (SDE) in 2026, and a multi-store group with $2M or more of purchase price moves onto EBITDA at 4.0x to 5.8x. Those are the IBBA Market Pulse Q2 2026 medians for all industries; no survey publishes a tire-only series, so the tire dealer data from Peak Business Valuation is the closest cross-check.
| Purchase price band | Earnings basis | Q2 2023 | Q2 2024 | Q2 2025 | Q2 2026 |
|---|---|---|---|---|---|
| Under $500K | SDE | 2.0x | 2.0x | 2.3x | 2.0x |
| $500K to $1M | SDE | 2.8x | 2.8x | 2.8x | 2.8x |
| $1M to $2M | SDE | 3.0x | 2.8x | 3.0x | 3.1x |
| $2M to $5M | EBITDA | 4.5x | 3.5x | 3.9x | 4.0x |
| $5M to $50M | EBITDA | 4.8x | 5.3x | 5.5x | 5.8x |
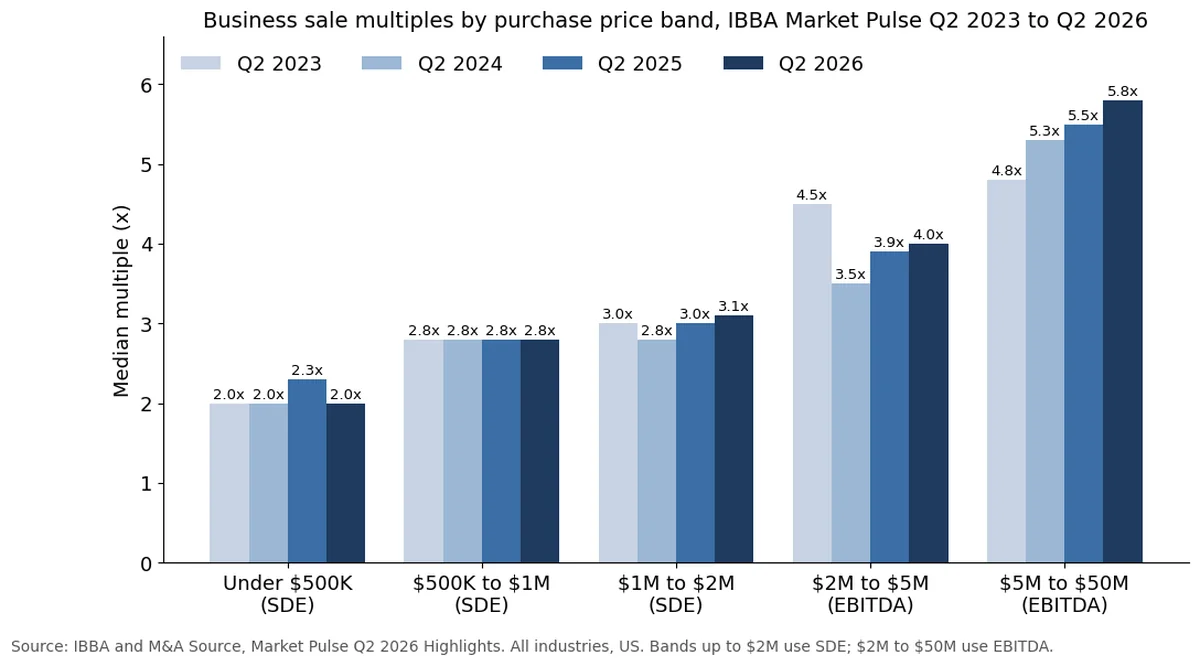
SDE adds the owner’s pay back to profit, so it fits a shop where the owner writes estimates and runs the counter. EBITDA assumes a paid manager. IBBA switches basis at $2M of purchase price, which is why a tire shop selling for $1.8M and a 6-store group selling for $2.5M can show 3.1x and 4.0x without the group being worth less per dollar of profit.
| Source (date) | Scope | SDE | EBITDA | Revenue |
|---|---|---|---|---|
| IBBA Market Pulse (Q2 2026) | All industries, by price band, broker survey | 2.0x to 3.1x | 4.0x to 5.8x | Not published |
| Peak Business Valuation (undated, accessed Nov 2026) | Tire dealerships, Peak’s database | 2.10x to 3.10x | 2.68x to 4.89x | 0.27x to 0.49x |
| GF Data via Middle Market Growth (H1 2025, published Nov 11, 2025) | Private equity deals, all industries, by enterprise value | Not published | 5.5x ($1M to $5M), 5.6x ($5M to $10M), 6.2x to 6.7x ($10M to $25M) | Not published |
| Monro, Inc. (Nov 13, 2026) | Public tire and service chain, 1,115 stores | Not applicable | 10.89x | 0.72x |
Which tire shop M&A deals disclosed a price?
Five tire chain transactions or sale processes since 2020 carry a public dollar figure, and only one of them, the 2024 Les Schwab sale talks, came with an EBITDA multiple: about 15x on roughly $500 million of EBITDA, per Reuters sources. Every other headline value is either a sources-based report or a company release without earnings, so a per-location figure is the most honest yardstick available.
| Date | Deal | Headline value | Locations | Basis of the figure | Source |
|---|---|---|---|---|---|
| Sep 2020 | Meritage Group buys Les Schwab Tire Centers from the family owners | About $3 billion | Not stated in the Reuters report | Reuters sources; never disclosed by the parties | Reuters via Investing.com |
| Mar 2021 | BayPine, with TSG Consumer Partners, buys Mavis Tire Express Services from Golden Gate Capital | More than $6 billion including debt | More than 1,100 in 27 states | Reuters sources before signing; final price undisclosed | Reuters via Fox Business, Mar 3, 2021 |
| Sep 2021 | Leonard Green & Partners becomes majority investor in Sun Auto Tire & Service; Greenbriar Equity stays a shareholder | Not disclosed | 200 | Trade press | Modern Tire Dealer, Sep 16, 2021 |
| May 2023 | TBC Corporation sells NTB (392) and Tire Kingdom (203) stores to Mavis | Not disclosed | 595 | Trade press | Tyre Press, May 23, 2023 |
| Aug 2024 | Meritage explores a Les Schwab sale with Goldman Sachs | More than $7 billion including debt; about 15x EBITDA of about $500 million | More than 500 in 13 states | Reuters sources; no completed sale found as of Nov 2026 | Reuters via Investing.com, Aug 8, 2024 |
| Oct 2025 | Percheron Capital recapitalizes Big Brand Tire & Service in a single-asset continuation vehicle co-led by Blue Owl, ICONIQ and Warburg Pincus | $1.625 billion | More than 250 | Company release | PR Newswire, Oct 2, 2025 |
| Jul 2026 | Big Brand agrees to buy Belle Tire (Michigan, Ohio, Indiana, Illinois) | Not disclosed; combined revenue above $1.5 billion | More than 180; combined more than 530 | Trade press; close expected Q3 2026 | Modern Tire Dealer, Jul 16, 2026 |
| Jul to Aug 2026 | Mavis buys Pep Boys from Icahn Enterprises; Icahn keeps owned real estate, AAMCO and Precision Tune | About $700 million cash | Nearly 800 | Company releases; closed by Aug 20, 2026 | European Rubber Journal |
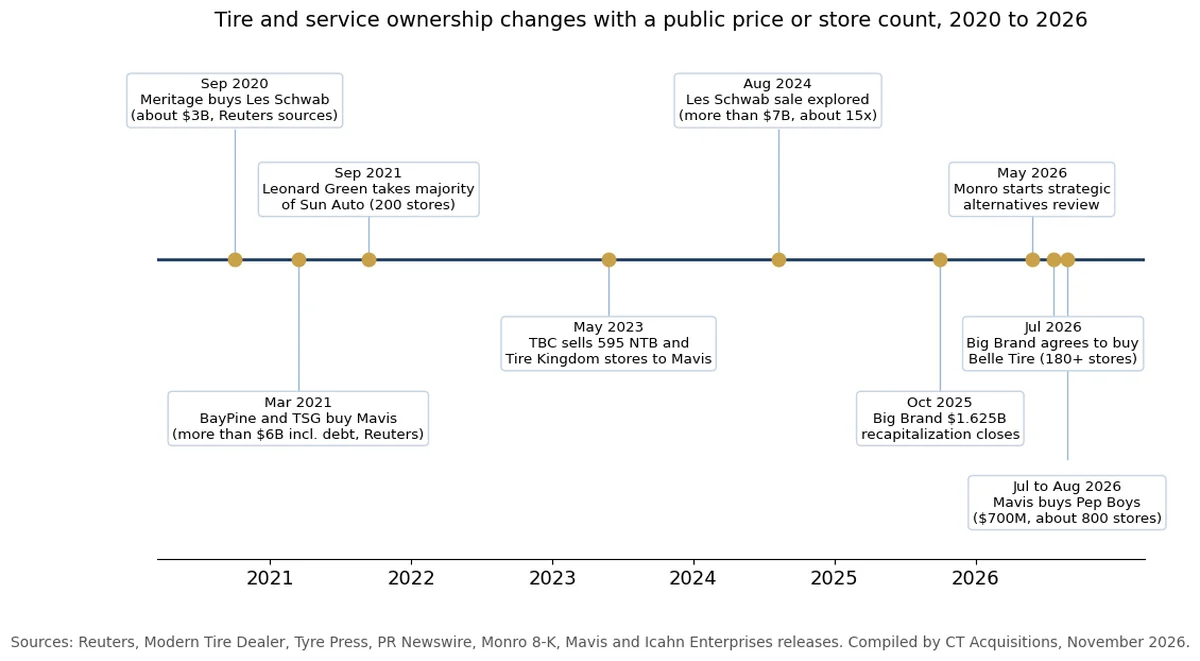
Mavis is the common thread. After the 595 TBC stores it reached about 2,000 locations per Tyre Press, the Midas deal took it past 3,500 in June 2025 per TBC Corporation, and Pep Boys lifted the network above 4,400 service centers in the United States and Canada. A single-store seller in a Mavis market is talking to a buyer that has closed four portfolio deals in six years.
What is a tire store location worth inside a chain?
Dividing each headline value by its stated store count gives a range from about $736K per store for Monro’s public enterprise value to about $14.0M per store in the reported 2024 Les Schwab talks. The spread is mostly scale, brand and owned real estate, not tire volume: Pep Boys, sold without its property, works out to about $875K per location.
| Company and date | Headline value | Locations | Value per location (CT arithmetic) | What the figure includes |
|---|---|---|---|---|
| Les Schwab, Aug 2024 (reported) | $7 billion | 500 | $14.0M or less | Debt; owned stores as reported; store count stated as more than 500 |
| Big Brand, Oct 2025 | $1.625 billion | 250 | $6.5M or less | Recapitalization value; store count stated as more than 250 |
| Mavis, Mar 2021 (reported) | $6 billion | 1,100 | $5.45M or less | Debt; store count stated as more than 1,100 |
| Pep Boys, Jul 2026 | $700 million | 800 | About $875K | Operating business only; Icahn kept the owned real estate |
| Monro, Nov 13, 2026 | $820.14 million enterprise value | 1,115 | About $736K | Public market value plus $506.79 million of debt, less cash |
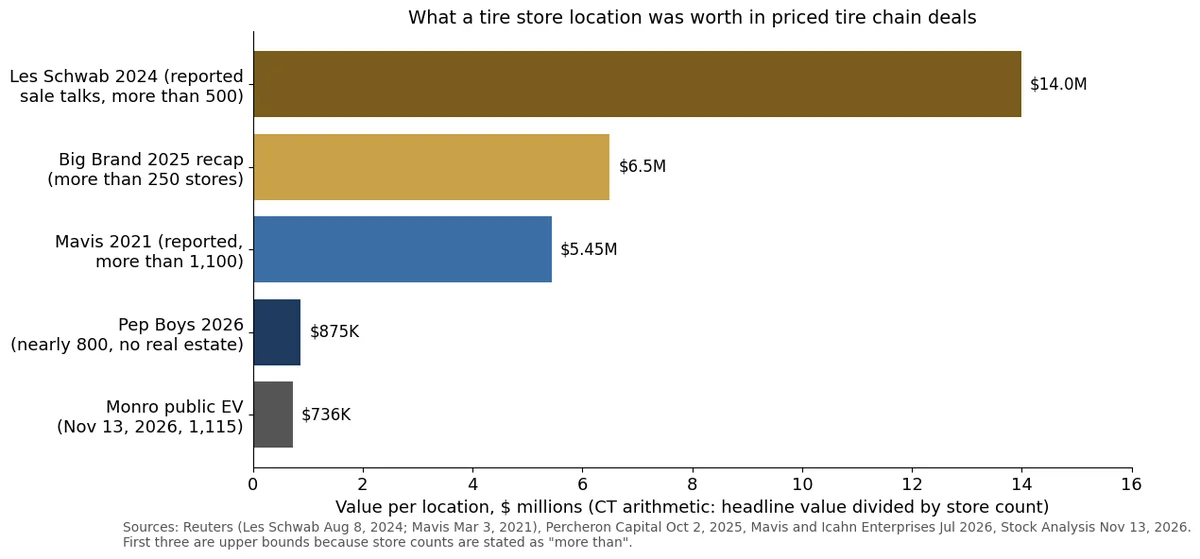
Treat the top three rows as ceilings, because each store count is a floor. The Pep Boys and Monro rows matter more to an independent owner: they show what a national buyer and the public market pay for an average tire and service box with the property stripped out or mostly leased. Monro leases 783 of its 1,115 stores per its fiscal 2026 Form 10-K.
What does Monro’s 10-K tell a private tire shop seller?
Monro’s fiscal 2026 Form 10-K shows a 1,115-store tire and service chain earning $20.0 million of operating income on $1,157.2 million of sales, a 1.7% operating margin, while the market values it at 10.89x trailing EBITDA. The public multiple is high because EBITDA is far above operating income, and the board opened a strategic alternatives review on May 27, 2026.
| Monro metric | Figure | Source |
|---|---|---|
| Fiscal year end | March 28, 2026 | Form 10-K |
| Sales | $1,157.2 million, down 3.2% | Form 10-K |
| Comparable store sales | Up 1.4% | Results release, May 27, 2026 |
| Operating income | $20.0 million (1.7% of sales) | Form 10-K; results release |
| Net income | $2.2 million | Form 10-K |
| Company-operated stores | 1,115 (783 leased, 290 owned, 42 owned buildings on leased land) | Form 10-K |
| Franchised locations | 46 Car-X | Form 10-K |
| Store closures | 145 underperforming stores closed in Q1 fiscal 2026 | Form 10-K |
| Owned stores sold | 26, for net proceeds of $19.7 million and a $9.9 million gain | Form 10-K |
| Enterprise value, Nov 13, 2026 | $820.14 million; 10.89x EBITDA of $75.31 million; 0.72x sales | Stock Analysis |
| Strategic review | Asset sales, refinancing, acquisitions or a sale of the company; no timeline | Form 8-K Exhibit 99.2 |
Two lessons carry over to a private shop. First, the 26 owned stores Monro sold for $19.7 million average about $758K each, which is the property-plus-box value a buyer will test against your own real estate. Second, a 1.7% operating margin with a 10.89x EBITDA multiple shows that buyers price tire chains on cash flow before depreciation and leases; a private buyer will rebuild your EBITDA with a market rent line before applying any multiple.
Who is buying tire shops in 2026?
Three sponsor-backed platforms did the dated tire buying from 2025 to November 2026: Mavis (BayPine and TSG), Sun Auto (Leonard Green) and Big Brand (Percheron, now with Belle Tire), while Les Schwab’s owner Meritage explored a sale in 2024. Monro is under strategic review rather than buying, and Discount Tire stays family-owned with about 1,250 stores per the Tire Business 2025 ranking.
| Buyer | Owner or sponsor | Latest dated footprint | Recent buying signal | Source |
|---|---|---|---|---|
| Mavis Tire Express Services | BayPine and TSG Consumer Partners (since 2021) | More than 4,400 service centers (Aug 2026) | Pep Boys, about 800 locations, 2026 | The Shop; European Rubber Journal |
| Sun Auto Tire & Service | Leonard Green & Partners (since Sep 2021) | 600th location (Oct 2026) | More than 80 locations added in 12 months; CEO calls M&A much more competitive | Modern Tire Dealer, Oct 19, 2026 |
| Big Brand Tire & Service | Percheron Capital; continuation vehicle co-led by Blue Owl, ICONIQ, Warburg Pincus | More than 530 with Belle Tire | Stated goal of 1,000 service centers | PR Newswire; Modern Tire Dealer |
| Les Schwab Tire Centers | Meritage Group (since 2020) | More than 500 in 13 states (Aug 2024) | Owner explored a sale in 2024 | Reuters |
| Monro, Inc. (NASDAQ: MNRO) | Public | 1,115 company stores (Mar 2026) | Closed 145 stores; strategic review since May 27, 2026 | Form 10-K; Form 8-K |
Tire Discounters, a regional chain often named as a consolidator, has no dated sponsor investment or sale release that we could find as of November 2026, so it is not listed with a sponsor. The roll-up logic is spelled out by KPMG Corporate Finance (June 2025): buy add-ons at lower multiples, exit at a higher one, and sell alignment and brake work that often carries gross margins of 50% or more. Our private equity auto repair platform tracker follows the same sponsors across general repair.
What would a $420K SDE tire shop sell for?
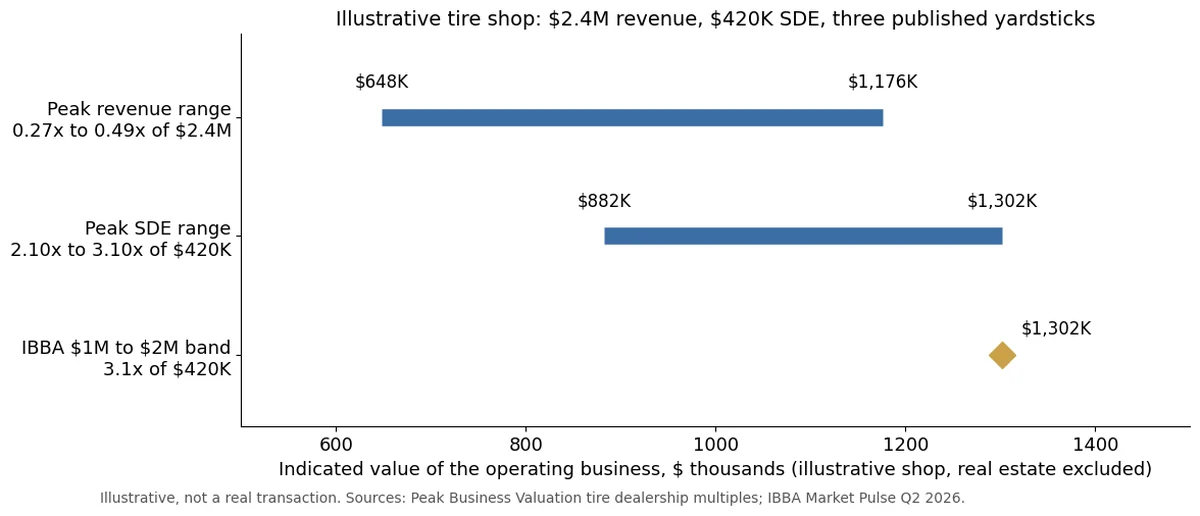
An illustrative single-store tire shop with $2.4M of revenue and $420K of SDE lands between $882K and $1,302K on Peak’s tire dealer SDE range, and at $1,302K on IBBA’s $1M to $2M band at 3.1x. Under IBBA’s Q2 2026 payment mix for that band, about 91% would arrive as cash at close. This is a constructed example, not a real transaction.
| Step | Input | Multiple or share | Result |
|---|---|---|---|
| 1. Revenue yardstick (Peak) | $2.4M revenue | 0.27x to 0.49x | $648K to $1,176K |
| 2. SDE yardstick (Peak) | $420K SDE | 2.10x to 3.10x | $882K to $1,302K |
| 3. Survey median (IBBA, $1M to $2M band) | $420K SDE | 3.1x | $1,302K |
| 4. Cash at close | $1,302K price | 91% | $1,184.8K |
| 5. Seller financing | $1,302K price | 7% | $91.1K |
| 6. Earnout | $1,302K price | 1% | $13.0K |
The SDE in step 2 must already carry a market rent. If the owner’s property company charges the shop below market, a buyer restates SDE downward before applying any multiple; at 3.1x, every $10K of rent restatement removes $31K of price. Our tire shop business valuation guide walks through the add-backs and the rent normalization step by step, and the tire shop valuation calculator runs the same arithmetic on your numbers.
For a 12-store group with $3.0M of EBITDA, the same yardsticks give $17.4M at IBBA’s 5.8x and $18.6M to $20.1M on GF Data’s 6.2x to 6.7x for $10M to $25M deals. The $2.7M gap between 5.8x and 6.7x is what a competitive process among two or three platforms is meant to win. Monro’s 10.89x would imply $32.7M, a public-market multiple no private buyer of a 12-store group is pricing toward.
How are tire shop deals paid, and what happens to the real estate?
Most of the price arrives as cash at close: IBBA’s Q2 2026 data shows 88% to 92% cash below $2M of price and 83% to 84% above it, with seller notes of 6% to 11%. Real estate is usually split off: Icahn kept Pep Boys’ owned property in the July 2026 sale, and Monro sold 26 owned stores separately for $19.7 million.
| Price band | Cash at close | Seller financing | Earnout | Retained equity |
|---|---|---|---|---|
| Under $500K | 88% | 11% | 1% | Not shown |
| $500K to $1M | 92% | 6% | 1% | Not shown |
| $1M to $2M | 91% | 7% | 1% | Not shown |
| $2M to $5M | 84% | 9% | 1% | Not shown |
| $5M to $50M | 83% | 6% | 7% | 4% |
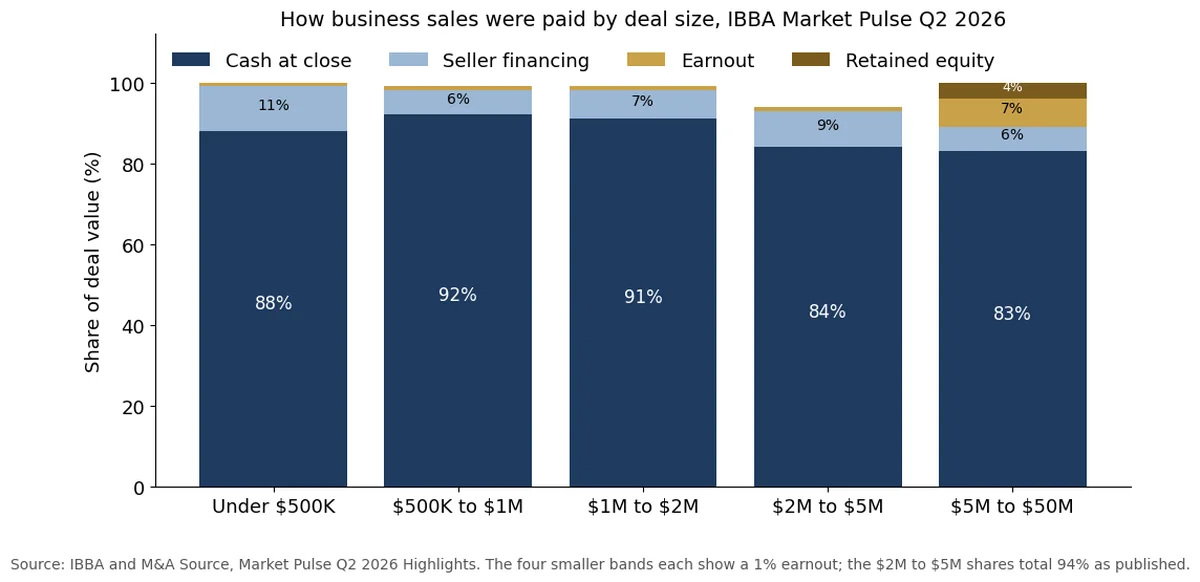
Below $5M, the buyer is often an individual using an SBA 7(a) loan, and the SBA caps a 7(a) loan at $5 million, so the lender’s debt-service test sets the practical ceiling. Lender appetite by bank is compared in our SBA acquisition lender rankings. In the $5M to $50M band, the 4% retained equity is the rollover a platform asks for; norms are in our rollover equity benchmarks.
Which path fits your tire shop?
The right sale path depends on three thresholds you can check today: purchase price above or below $2M (SDE versus EBITDA pricing), purchase price above or below the $5 million SBA 7(a) cap (individual versus platform buyer), and whether you own the property. Store overlap with Mavis, Sun Auto, Big Brand or Les Schwab decides how many platforms will bid.
| If your situation is | Expect | Do this first |
|---|---|---|
| If your likely price is under $1M and you work the counter | About 2.0x to 2.8x SDE (IBBA); SBA-financed individual buyer; 6% to 11% seller note | Hire or name a counter manager and get two years of clean tax returns before listing |
| If your likely price is $1M to $2M | About 3.1x SDE (IBBA Q2 2026); 91% cash at close | Restate SDE with a market rent line so diligence does not do it for you |
| If you own the land under the shop | Business priced on earnings after rent; property sold or leased separately | Get a separate real estate appraisal and decide sell versus lease before going to market |
| If you run 3 or more stores with $1M to $3M of EBITDA | 4.0x to 5.8x EBITDA on IBBA bands; 5.5x to 6.7x on GF Data private equity bands | Commission a sell-side quality of earnings review and invite more than one platform |
| If your stores sit in Michigan, Ohio, Indiana or Illinois | Big Brand plus Belle Tire is a new buyer with density there (agreement of Jul 16, 2026) | Check which of your stores overlap Belle Tire’s footprint before any conversation |
| If a platform calls you unsolicited | A single bidder sets the price; Sun Auto’s CEO says M&A is “much more competitive” | Ask for the offer in writing, then test it against at least one other platform |
What several pages say vs what the primary source says
Several tire M&A pages, including the earlier version of this report, repeat figures that the primary sources do not support. The table lists each claim, what the filing or original report says, and the date, so a seller quoting a multiple to a buyer quotes one that survives a check.
| Claim seen | What the primary source says | Source |
|---|---|---|
| Sun Auto sold to Leonard Green at about 12x to 14x EBITDA | Price not disclosed; Leonard Green became majority investor on Sep 16, 2021 with 200 stores | Modern Tire Dealer |
| Mavis recapitalized at a disclosed enterprise value above $6 billion | More than $6 billion including debt was a Reuters sources report before signing; final terms undisclosed | Reuters, Mar 3, 2021 |
| Les Schwab sold for $3 billion in 2020 | Price never disclosed; about $3 billion comes from Reuters sources | Reuters, Aug 8, 2024 |
| Monro has 1,116 company stores and 48 franchised | 1,115 company-operated stores and 46 Car-X franchised locations at Mar 28, 2026 | Monro Form 10-K |
| Monro trades near 9.2x EBITDA | 10.89x EV/EBITDA on Nov 13, 2026 | Stock Analysis |
| IBBA Q1 2026 release reports 2.0x under $500K and 5.5x at $5M to $50M | The Q1 release gives no multiples; the Q2 2026 highlights show 2.0x and 5.8x | IBBA |
How we compiled this
We compiled this report in November 2026 from the dated documents listed under Sources: Monro’s fiscal 2026 Form 10-K and Form 8-K, the IBBA Market Pulse Q2 2026 highlights, GF Data’s H1 2025 summary, company releases from Percheron Capital, Mavis and Icahn Enterprises, Reuters reports and tire trade press. Per-location values are our arithmetic from headline values and stated store counts. We excluded listing asking prices and multiples with no named source.
We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells. If you are weighing a platform offer for your tire business, our tire shop sale process page explains how a confidential sale runs, and you can book a call with CT Acquisitions to test an offer against our 500+ buyer network.
Frequently asked questions
What multiple does a tire shop sell for in 2026?
An owner-run tire shop typically sells for about 2.0x to 3.1x SDE, the IBBA Market Pulse Q2 2026 medians for deals under $2M. Peak Business Valuation’s tire dealership data shows 2.10x to 3.10x SDE and 0.27x to 0.49x revenue. Multi-store groups priced above $2M move to EBITDA, at 4.0x to 5.8x on IBBA’s Q2 2026 bands.
How much did Les Schwab sell for in 2020?
Meritage Group bought Les Schwab Tire Centers from the founding family in September 2020 without disclosing a price. Reuters later reported, citing sources, that the 2020 deal was worth about $3 billion, and in August 2024 that Meritage was exploring a sale valuing the chain of more than 500 stores at more than $7 billion including debt.
Who bought Pep Boys and for how much?
Mavis Tire Express Services agreed on July 20, 2026 to buy Pep Boys from Icahn Enterprises for about $700 million in cash, and the deal closed by August 20, 2026. Pep Boys added nearly 800 locations, taking Mavis above 4,400 service centers. Icahn Enterprises kept the owned real estate plus AAMCO and Precision Tune.
Who is acquiring Belle Tire?
Big Brand Tire & Service, owned by Percheron Capital, signed a definitive agreement on July 16, 2026 to acquire Belle Tire, which runs more than 180 stores in Michigan, Ohio, Indiana and Illinois. Terms were not disclosed. The combined company has more than 530 locations and more than $1.5 billion of revenue, with closing expected in the third quarter of 2026.
Is Discount Tire publicly traded?
No. Discount Tire is family-owned and has no public stock, so it never prints a transaction multiple. It operated about 1,250 stores across 40 states as of mid-2025 and ranked as the highest-dollar-sales tire retailer in the Tire Business 2025 ranking. The only listed US tire and service chain of scale is Monro, Inc. (NASDAQ: MNRO).
Should I sell my tire shop’s real estate with the business?
Usually the two are priced separately. The business sells on earnings after a market rent, and the property is sold at appraisal or leased to the buyer. Icahn Enterprises kept Pep Boys’ owned real estate in the 2026 sale, and Monro sold 26 owned stores for $19.7 million as a separate step in fiscal 2026.
Sources
- IBBA and M&A Source, Market Pulse Q2 2026 Highlights, August 2026 (accessed Nov 14, 2026)
- IBBA and M&A Source, Market Pulse Q1 2026 release, PR Newswire, Jun 30, 2026
- Peak Business Valuation, Valuation Multiples for Tire Dealerships, undated (accessed Nov 14, 2026)
- Middle Market Growth, GF Data small deals H1 2025, Nov 11, 2025
- Monro, Inc., Form 10-K for fiscal year ended Mar 28, 2026, SEC EDGAR (accessed Nov 14, 2026)
- Monro, Inc., fourth quarter and fiscal 2026 results and strategic alternatives review (Form 8-K), May 27, 2026
- Stock Analysis, MNRO statistics, Nov 13, 2026
- Reuters via Fox Business, BayPine close to $6B Mavis Tire acquisition, Mar 3, 2021
- Reuters via Investing.com, Les Schwab owner explores sale, Aug 8, 2024
- Modern Tire Dealer, Sun Auto Tire gets new majority investor and CEO, Sep 16, 2021; Sun CEO talks growth strategy, Oct 19, 2026; Big Brand owner closes recapitalization, Oct 2, 2025; Big Brand to acquire Belle Tire, Jul 16, 2026
- PR Newswire, Percheron Capital $1.625 billion recapitalization of Big Brand Tire & Service, Oct 2, 2025
- Tyre Press, TBC Corporation sells 595 NTB and Tire Kingdom centres to Mavis, May 23, 2023
- TBC Corporation, divestiture of Midas to Mavis, June 2025
- The Shop, Mavis to acquire Pep Boys from Icahn Enterprises, Jul 24, 2026; European Rubber Journal, Mavis completes acquisition of Pep Boys, Aug 2026
- KPMG Corporate Finance, Gaining traction: Why tire retail is on a roll, June 2025
- Tire Business, Top 100 tire retail dealerships in North America, 2025
- U.S. Small Business Administration, 7(a) loans (accessed Nov 14, 2026)
Related research: the automotive services M&A multiples report compares tire with repair, quick lube, collision and car wash, and the auto repair shop M&A multiples report covers shops without a tire anchor.
Related research: for the 2026 Automotive Services M&A Multiples Report, the cluster pillar comparing 8 automotive sub-verticals side-by-side, see the linked report.
Related research: for the 2026 Auto Repair and Mechanic Shop M&A Multiples Report, sibling automotive spoke, see the linked report.
Related research: for the 2026 Quick Lube M&A Multiples Report, sibling automotive spoke with car-count economics + Valvoline/Breeze 10.7x disclosed anchor, see the linked report.
