How to Sell a Data Center Business in 2026: Colocation M&A Multiples and Named Buyers
Data center M&A pays for contracted power: buyers price a founder-owned colocation, edge or data center services firm on leased MW, utilization, lease term and customer concentration, between about 5.5x and 13x EBITDA.
By Christoph Totter, Founder of CT Acquisitions · Last reviewed: November 2026
Thinking about selling your business?
A 15-minute confidential call gives you a real valuation range and the buyers most likely to compete for your business. No cost, no obligation.
Key takeaways
- The headline deal of this cycle closed on July 21, 2026: AIP, MGX and BlackRock’s Global Infrastructure Partners bought Aligned Data Centers at an enterprise value of about $40 billion, with 51 campuses and more than 6.4 GW of operational and planned capacity (Aligned release).
- Size sets the multiple: Alantra’s 2024 review shows a 130 MW hyperscale carve-out in Paris (Opcore) at 25x EBITDA and a 15 MW retail colocation carve-out in Brussels (Proximus) at 13.1x (Alantra, January 2025).
- Across all industries, the IBBA and M&A Source Market Pulse put Q4 2025 average multiples at 4.1x EBITDA for $2M to $5M deals and 5.5x for $5M to $50M deals (Market Pulse Q4 2025), the realistic floor for a data center services firm.
- Space is scarce: primary-market vacancy fell to a record low of 1.4% in H1 2026 from 1.6% a year earlier, per CBRE North America Data Center Trends H1 2026 (published August 27, 2026).
- Mergermarket counted 33 North American data center deals worth USD 50.7bn in 2025 through November 12, against 43 deals worth USD 14.3bn a year earlier; Aligned alone was USD 40bn (ION Analytics).
Who sells in data center M&A, and which seller are you?
Most data center M&A headlines are hyperscale campuses sold between infrastructure funds. The seller CT Acquisitions works with is different: a founder-owned colocation operator with 1 to 10 MW, an edge facility in a secondary metro, or a data center services firm that maintains, cables or decommissions other people’s facilities. Each one sells to a different buyer, at a different multiple, so identify your row first.
If you own a hyperscale campus leased to a cloud provider, this page is not for you; you already have bankers.
| Seller profile | Typical size | What the buyer is paying for | Recent comparable | Source |
|---|---|---|---|---|
| Hyperscale campus (not a typical CT seller) | 100 MW to multiple GW | Long cloud leases, powered land, expansion rights | Aligned Data Centers, about $40 billion EV, closed July 21, 2026 | Aligned release |
| Regional multi-tenant colocation | 1 to 10 MW | Leased kW, customer contracts, interconnection | Lightedge (backed by GI Partners) bought a 3 MW Tier III facility in Kansas City, 100% pre-leased, April 30, 2026 | Lightedge |
| Edge or suburban facility with expansion rights | 4 to 8 MW today | Built capacity plus a path to more MW | US Signal (backed by Igneo) bought an Aurora, Illinois site planned for 4 MW critical, January 2026; RadiusDC agreed to buy phoenixNAP’s Phoenix facility, 8 MW expanding to a 26 MW campus, March 2026 | Pulse 2.0; W.Media |
| Data center services firm (critical facilities maintenance, cabling, decommissioning) | $2M to $50M purchase price | Recurring service contracts, technicians, customer list | Priced like other services businesses: 4.1x to 5.5x EBITDA averages in Q4 2025 | IBBA and M&A Source Market Pulse |
Services sellers have sibling guides: decommissioning firms should read our ITAD and data center decommissioning valuation guide, and cabling contractors our guide on how to sell a low-voltage company.
What is a data center business worth? Data center valuation by asset type
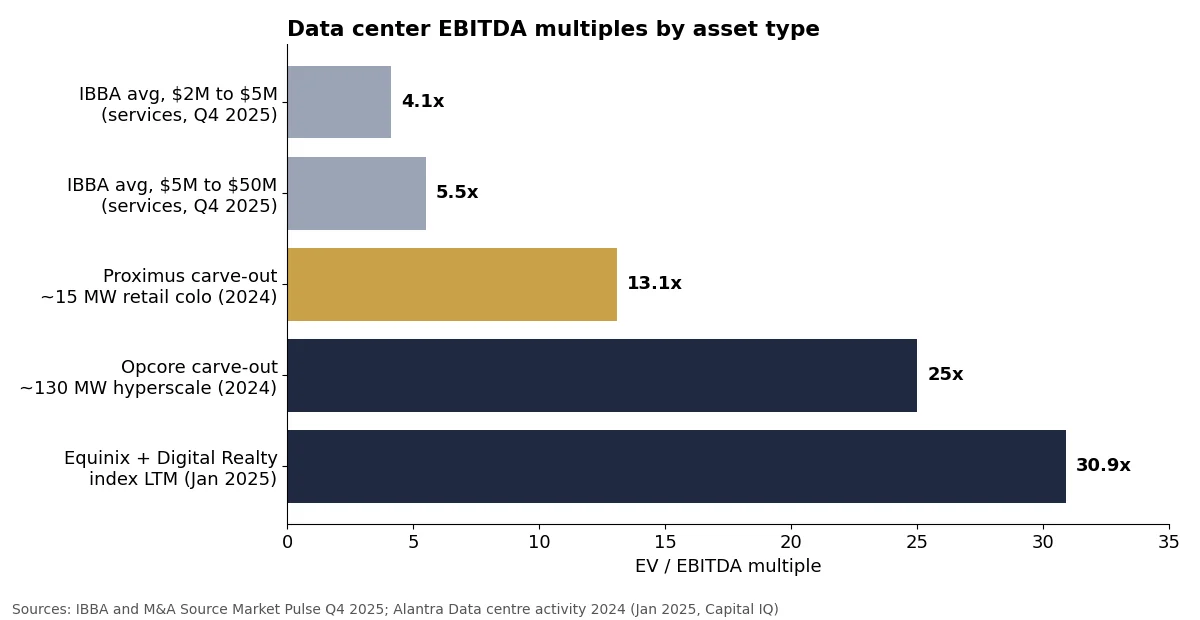
A data center business is worth a multiple of EBITDA that climbs with scale, contract length and tenant credit. Disclosed anchors run from 4.1x to 5.5x EBITDA for services businesses (IBBA, Q4 2025), 13.1x for a 15 MW retail colocation carve-out, 25x for a 130 MW hyperscale portfolio, and 30.9x for the listed Equinix and Digital Realty index in January 2025.
| Anchor | Size or scope | EV/EBITDA | Date | Source |
|---|---|---|---|---|
| Lower middle market average, all industries ($2M to $5M price) | Services businesses | 4.1x | Q4 2025 | IBBA and M&A Source Market Pulse |
| Lower middle market average, all industries ($5M to $50M price) | Services businesses | 5.5x | Q4 2025 | IBBA and M&A Source Market Pulse |
| Proximus data centre carve-out to Cordiant and TINC (Brussels) | ~15 MW, 3 facilities, retail colocation | 13.1x | October 2024 | Alantra |
| Opcore carve-out (Paris) | ~130 MW, 6 facilities, hyperscale | 25x | 2024 | Alantra |
| AirTrunk to Blackstone and CPP Investments | 800 MW+ committed to customers | ~30x (rumoured) | September 4, 2024 | Alantra; CPP Investments |
| Listed data centre index (Equinix and Digital Realty), LTM | Global public platforms | 30.9x (S&P 500: 17.4x) | January 21, 2025 | Alantra, citing Capital IQ |
What several guides say vs what the disclosed deals show
Many seller guides, including the earlier version of this page, quote 20x to 30x EBITDA as “the” data center multiple. That band comes from listed REITs (30.9x LTM in January 2025, per Alantra) and hyperscale platforms. The one disclosed retail colocation trade in Alantra’s 2024 review, 15 MW across 3 Brussels facilities, priced at 13.1x. A 2 MW founder-owned facility should benchmark against that deal and the IBBA bands, not AirTrunk.
Which valuation drivers move a data center multiple?
Five drivers decide where a data center business lands between 5.5x and 13x or more: contracted kW versus built kW (utilization), remaining lease term, the share of revenue from the largest customer, a written utility commitment for more power, and engineering proof such as an Uptime Institute Tier certification and a measured PUE. Buyers check each one in diligence with documents, not with the seller’s summary.
| Driver | What the buyer measures | Benchmark | Source |
|---|---|---|---|
| Contracted MW and utilization | Leased kW divided by built kW, by customer, by month | Lightedge’s 3 MW Kansas City purchase was 100% pre-leased, with rights of first refusal for all tenants | Lightedge, April 30, 2026 |
| Power availability | Utility service agreement, committed load, substation ownership, expansion MW | DartPoints’ Lexington campus came with an owned on-site substation and a 20 to 30 MW first phase | Baxtel, May 28, 2026 |
| Lease terms and churn | Remaining term per contract, renewal history, monthly recurring revenue (MRR) churn | Equinix targets MRR churn of 2% to 2.5% per quarter for 2026 and averaged 2.4% in 2025 | Equinix Q4 2025 call |
| Customer concentration | Largest customer’s share of MRR, and that customer’s renewal date | Concentrated revenue is discounted or moved into an earnout | CT Acquisitions working rule |
| Engineering and efficiency | Uptime Tier (Tier III: concurrently maintainable; Tier IV: fault tolerant), trailing 12 month PUE | Industry weighted average PUE was 1.54 in 2025, the sixth flat year | Uptime Institute Tiers; Uptime 2025 survey |
| Interconnection | Cross-connect count and revenue, carriers on site | Equinix passed 0.5 million interconnections in Q4 2025 | Equinix Q4 2025 call |
Customer concentration deserves its own check before you go to market. Our guide to customer concentration risk in a business sale shows how buyers price a single large tenant, and a colocation facility with one tenant above a quarter of MRR is that case.
Worked example: how contracted kW becomes a price (illustrative)
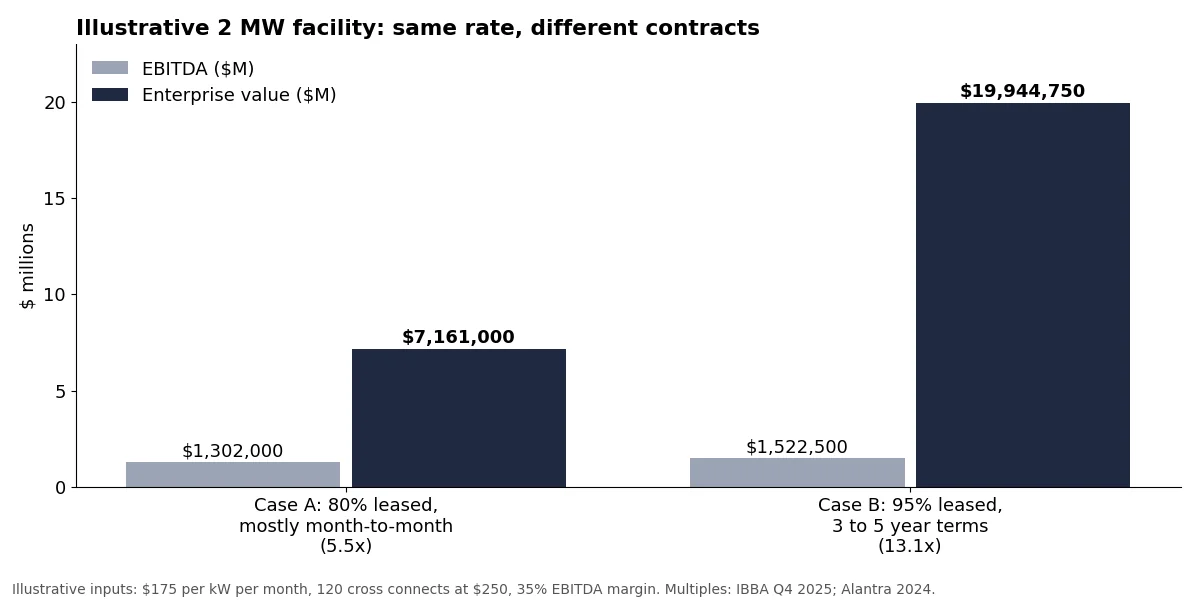
The example below is illustrative, with invented inputs. A 2 MW facility charging $175 per kW per month earns the same rate in both cases; what changes is leased kW, contract term and concentration. That moves the buyer from a services-style 5.5x (IBBA $5M to $50M average) to the 13.1x paid for the Proximus retail colocation carve-out.
| Line | Case A: 80% leased, mostly month-to-month | Case B: 95% leased, 3 to 5 year terms | How it is calculated |
|---|---|---|---|
| Built capacity | 2,000 kW | 2,000 kW | Illustrative input |
| Leased capacity | 1,600 kW | 1,900 kW | Built kW x utilization |
| Colocation revenue | $3,360,000 | $3,990,000 | Leased kW x $175 x 12 months |
| Cross-connect revenue | $360,000 | $360,000 | 120 cross connects x $250 x 12 months |
| Total revenue | $3,720,000 | $4,350,000 | Sum of the two lines |
| EBITDA at a 35% margin | $1,302,000 | $1,522,500 | Revenue x 35% |
| Multiple applied | 5.5x | 13.1x | IBBA $5M to $50M average vs Proximus carve-out |
| Enterprise value | $7,161,000 | $19,944,750 | EBITDA x multiple |
The 300 kW of extra leasing adds $220,500 of EBITDA. The contract terms and the buyer class add the rest of the $12,783,750 gap. That is why signing terms before a sale usually pays more than cutting costs.
Which deals set the price in data center mergers and acquisitions?
Data center mergers and acquisitions since 2021 split into two markets. Take-privates and platform buyouts, from QTS at about $10 billion to Aligned at about $40 billion, set headlines. Single-site purchases by PE-backed platforms such as Lightedge, US Signal and DartPoints, usually with the price undisclosed, set what a founder-owned facility can expect.
| Date | Target | Acquirer | Reported value or size | Source |
|---|---|---|---|---|
| 2021 (completed October 2021) | QTS Realty Trust | Blackstone | About $10 billion | Data Center Frontier |
| November 2021 | CyrusOne | KKR and Global Infrastructure Partners | About $15 billion | Data Center Frontier |
| 2021 | CoreSite Realty | American Tower | About $10.1 billion | Data Center Frontier |
| May 2022 | Switch | DigitalBridge and IFM Investors | About $11 billion | Data Center Frontier |
| September 4, 2024 | AirTrunk | Blackstone and CPP Investments | Implied EV over A$24 billion | CPP Investments |
| October 15, 2025 (closed July 21, 2026) | Aligned Data Centers | AIP, MGX and Global Infrastructure Partners | About $40 billion EV | Aligned release |
| January 2026 | Aurora, Illinois facility | US Signal | Planned 4 MW critical, price undisclosed | Pulse 2.0 |
| March 2026 | phoenixNAP Phoenix facility | RadiusDC | 8 MW, 26 MW campus plan, price undisclosed | W.Media |
| April 30, 2026 | Kansas City Tier III facility | Lightedge | 3 MW, price undisclosed | Lightedge |
| May 2026 | Lexington, Kentucky campus | DartPoints | 20 to 30 MW first phase, price undisclosed | Baxtel |
Two lessons carry down to a regional operator. Buyers pay for power and expansion: Aligned’s buyers committed an additional $5 billion of growth capital at closing. And PE-backed platforms such as Lightedge (GI Partners) and US Signal (Igneo) buy single facilities as add-ons, the realistic exit for a 1 to 10 MW site. Tower owners face the same buyer logic, covered in our guide on selling a wireless tower business.
How do you prepare a data center business for sale?
To sell a data center company, assemble the documents a buyer will test before you talk to one: the utility agreement, every customer contract with kW and term, 24 months of MRR and churn, engineering records, a current Phase I environmental report, and accrual financials. Sellers who hand these over in week one avoid the price cuts that follow surprises in diligence.
- Power file. Utility service agreement, committed load in MW, any written commitment for expansion load, substation ownership, and 24 months of power bills. If the utility has not committed extra load in writing, expect buyers to price built capacity only.
- Customer schedule. One row per customer: contracted kW, monthly charge, start date, end date, renewal history, cross connects. Flag every customer above 10% of MRR.
- Churn and MRR history. Monthly recurring revenue and churn by quarter for 8 quarters, the format Equinix reports against its 2% to 2.5% per quarter target.
- Engineering record. Uptime Tier certification if held, redundancy design, trailing 12 month PUE (total facility power divided by IT power), cooling capacity per rack, capex log.
- Real estate and environment. Deed or ground lease, zoning, and a Phase I environmental site assessment under ASTM E1527-21; the EPA all appropriate inquiries rule (40 CFR Part 312) needs key parts updated within 180 days before the acquisition date.
- Financials. Accrual statements for 3 years, contracted vs uncontracted revenue split, power pass-through shown separately, and a sell-side review modeled on a quality of earnings report.
What kills data center deals in diligence?
Data center deals fail on facts the seller could have found first: power that is not committed in writing, a largest customer with a renewal inside the next 12 months, a PUE far above the 1.54 industry average, an environmental finding, or revenue that mixes power pass-through with margin. Each one either lowers the multiple or moves price into an earnout.
- No written utility commitment for the MW the buyer is modeling, or an interconnection queue with no date.
- One tenant with a large share of MRR and a lease that ends within 12 months of closing.
- Measured PUE well above 1.54 (Uptime 2025 average), which signals cooling capex the buyer will deduct.
- A Phase I environmental report older than one year at closing, outside the EPA window.
How long does data center M&A take, and what filings apply?
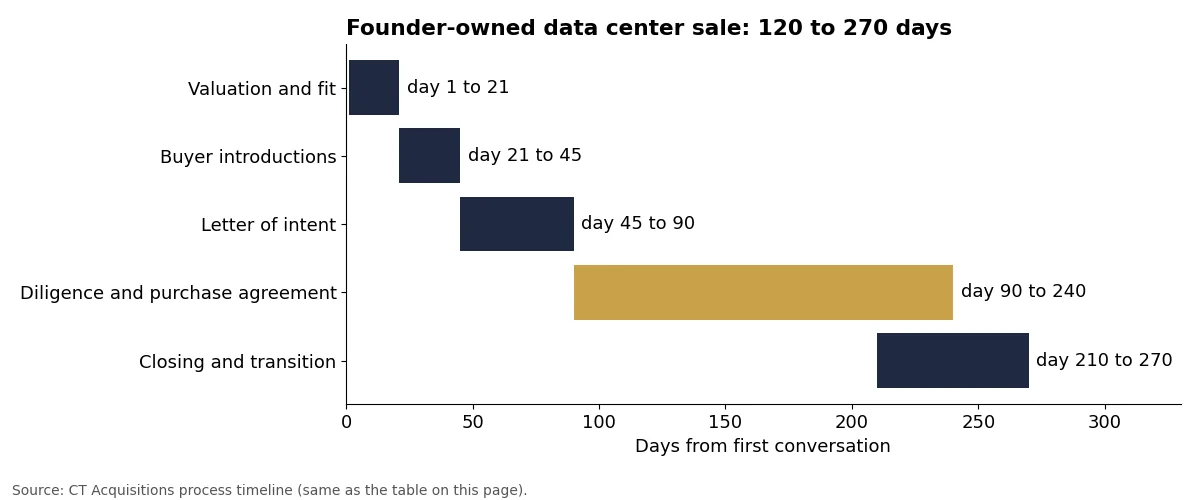
A founder-owned data center sale usually runs 120 to 270 days from first conversation to closing, longer than most services deals because power, real estate and engineering diligence run in parallel with the financial review. Deals above the 2026 Hart-Scott-Rodino threshold of $133.9 million also need a federal premerger filing before closing.
| Phase | Days | What happens |
|---|---|---|
| Valuation and fit | 1 to 21 | Power file, customer schedule and EBITDA reviewed; buyer types chosen |
| Buyer introductions | 21 to 45 | Confidential outreach to platforms and infrastructure funds under NDA |
| Letter of intent | 45 to 90 | Price, structure, earnout and exclusivity agreed in an LOI |
| Diligence and purchase agreement | 90 to 240 | Utility, leases, engineering, Phase I, quality of earnings; definitive agreement drafted |
| Closing and transition | 210 to 270 | Customer notices, utility account transfer, funds flow |
The FTC raised the HSR size-of-transaction threshold to $133.9 million from $126.4 million for 2026. In an asset sale, both buyer and seller file IRS Form 8594 to allocate price across equipment, real estate and goodwill; our guide to asset sale vs stock sale covers which structure fits a facility you own.
Should you sell, recapitalize or wait? A decision table
Match your facts to a next step. Rows marked CT working rule are cutoffs CT Acquisitions applies in first conversations, not published standards; the HSR ($133.9 million), EPA (180 days) and IBBA (4.1x to 5.5x) rows come from the cited sources. If two rows apply, the power or concentration row usually decides timing.
| If your situation is | Then do this | Basis |
|---|---|---|
| If more than half of MRR is month-to-month | Sign 3 to 5 year terms with your top customers before going to market | Worked example: 5.5x vs 13.1x |
| If one customer is above 25% of MRR with under 12 months left | Renew that contract first, or expect part of the price as an earnout | CT working rule |
| If utilization is below 70% and the utility has committed more load | Consider a partial recapitalization to fund lease-up and sell the rest later | CT working rule |
| If the utility has not committed expansion load in writing | Price only built capacity; get the letter before marketing expansion | Buyers model committed MW |
| If you sell services, not space (cabling, maintenance, decommissioning) | Benchmark against 4.1x to 5.5x EBITDA and services buyers | IBBA Q4 2025 |
| If expected value is above $133.9 million | Budget time for an HSR filing before closing | FTC, 2026 thresholds |
| If your Phase I is older than 180 days at the target closing date | Order an update so the buyer keeps its all appropriate inquiries protection | EPA, 40 CFR Part 312 |
How we compiled this
We compiled this page in November 2026 from 16 public documents: company and investor releases (Aligned Data Centers, CPP Investments, Lightedge), market reports (CBRE, Mergermarket via ION Analytics, Alantra, Uptime Institute, IBBA and M&A Source), government sources (FTC, IRS, EPA) and dated trade press for deals with no primary release. Deal prices marked undisclosed were not published. We excluded forum posts and unattributed multiples.
Sources
All sources accessed November 2026.
- Aligned Data Centers, closing release, July 21, 2026
- CPP Investments, AirTrunk announcement, September 4, 2024
- Alantra, Data centre activity 2024, January 2025
- IBBA and M&A Source, Market Pulse Q4 2025 Highlights
- CBRE, North America Data Center Trends H1 2026, August 27, 2026
- ION Analytics, Dealspeak North America, November 12, 2025
- Uptime Institute, Global Data Center Survey 2025 and Tier Classification System
- Equinix Q4 2025 earnings call transcript, February 11, 2026
- Lightedge, Kansas City acquisition release, April 30, 2026
- W.Media, RadiusDC and phoenixNAP, March 13, 2026
- Pulse 2.0, US Signal Aurora acquisition, January 30, 2026
- Baxtel, DartPoints Lexington acquisition, May 28, 2026
- Data Center Frontier, The largest data center deals of all time, May 11, 2022
- FTC, 2026 HSR thresholds, January 14, 2026
- IRS, About Form 8594 and EPA, Brownfields All Appropriate Inquiries
Data Center / Colocation Valuation
What’s your data center business worth?
Get a starting range from our 90-second tool, then a confidential call about your leased kW, contract terms, largest customer, utility commitment and PUE.
Curious what your business is worth?
A 15-minute confidential call gives you a real valuation range and tells you which buyers would compete for your business. No cost, no obligation, no pressure to sell.
The five pillars of how CT Acquisitions works
We represent owners: confidential sale, recapitalization and exit planning.
Success fee only, nothing upfront. You pay nothing unless the business sells.
Search funders, family offices, lower-middle-market PE, strategics.
Introductions to the right buyers only. No public listing.
You see exactly how we are paid before any work starts.
No Pitch · No Pressure
Considering selling your data center business?
In a 15-minute call, tell us your built and leased kW, contract terms, utility commitment and EBITDA. We will tell you which buyer class fits and what to fix before a sale. You will know our terms in writing before any work starts.
About the Author
Christoph Totter is the founder of CT Acquisitions, an M&A advisory firm that represents business owners on the sell side, headquartered in Sheridan, Wyoming. We work directly with 500+ buyers, search funders, family offices, lower middle-market PE, and strategic consolidators, including direct mandates with the largest consolidators that other intermediaries cannot access. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells. Connect on LinkedIn · Get in touch
Frequently asked questions
How much is a data center worth?
A data center business is worth a multiple of EBITDA set by its size and contracts. Disclosed anchors run from 4.1x to 5.5x for services businesses (IBBA, Q4 2025) to 13.1x for a 15 MW retail colocation carve-out and 25x for a 130 MW hyperscale portfolio (Alantra, January 2025). Leased kW, remaining lease term, the largest customer’s share and committed utility power decide where yours lands.
How do you sell a data center company?
Build the power file, customer schedule, 8 quarters of MRR and churn, engineering records, a Phase I environmental report under ASTM E1527-21 and accrual financials first. Then approach the buyer class that fits your size, usually PE-backed colocation platforms or infrastructure funds for 1 to 10 MW sites, under NDA and in parallel, and negotiate price and earnout in a letter of intent.
Who buys data center businesses in 2026?
Buyers split by size. Infrastructure consortia buy hyperscale platforms, such as AIP, MGX and Global Infrastructure Partners with Aligned at about $40 billion. PE-backed platforms buy single regional sites: Lightedge (GI Partners) bought a 3 MW Kansas City facility in April 2026 and US Signal (Igneo) an Aurora, Illinois site in January 2026. Services roll-ups buy cabling, maintenance and decommissioning firms.
How long does it take to sell a data center business?
Plan on 120 to 270 days from first conversation to closing for a founder-owned facility. Utility agreements, leases, engineering and the Phase I report are reviewed alongside the quality of earnings work, which takes longer than a typical services deal. If the price exceeds the 2026 HSR threshold of $133.9 million, add time for the FTC premerger filing and waiting period.
Is a data center a profitable business?
It can be once capacity is leased. Profit turns on utilization, contract term, power cost and churn: Equinix, the largest colocation operator, targets MRR churn of 2% to 2.5% per quarter for 2026. A partly leased site carries the full cost of power, cooling and staff, so lease-up from 80% to 95% moves EBITDA far more than cost cuts do.
Did BlackRock acquire Aligned Data Centers?
Yes, through a consortium. BlackRock’s Global Infrastructure Partners, MGX and the AI Infrastructure Partnership (AIP) agreed on October 15, 2025 to buy Aligned Data Centers from Macquarie Asset Management funds at an enterprise value of about $40 billion, and closed on July 21, 2026, committing an additional $5 billion of growth capital. Aligned has 51 campuses and more than 6.4 GW of capacity.
Related research
- Free Business Valuation Tool, your business is worth in 90 seconds
- The Business Broker Alternative Guide (national pillar)
- Business Brokers by State
- The Complete Guide to Selling Your Business in 2026
- What’s My Business Worth? Founder’s Valuation Guide
- Who Buys These Companies? Buyer Types Explained
- How to Sell to Private Equity, A Founder’s Walkthrough
- Owner’s Pre-Exit Checklist, 90 Days Before You List
- CT Commentary, Founder & M&A Insights
