
How Is Goodwill Taxed When Selling a Business?
Quick Answer
How is goodwill taxed when you sell a business? As long-term capital gain: 0%, 15% or 20% federal in 2026, plus 3.8% NIIT for passive owners, but 39.8% when a C corporation sells it and distributes the cash.
By Christoph Totter, Founder of CT Acquisitions · Last reviewed: November 2026
General information for U.S. owners, not tax advice. Confirm the numbers with your CPA before you sign a letter of intent, because the allocation is usually set there.
Key takeaways
- For 2026, a married couple pays 0% on long-term gain up to $98,900 of taxable income, 15% up to $613,700 and 20% above (IRS Rev. Proc. 2025-32).
- Goodwill is Class VII on IRS Form 8594, the residual after Classes I to VI, and buyer and seller both file the form for the year of sale.
- Goodwill you bought and amortized is treated as depreciable property under IRC Section 197(f)(7), so gain up to the amortization taken is ordinary income under Section 1245.
- A C corporation pays 21% on goodwill gain under IRC Section 11(b), and the owner pays up to 23.8% on the distribution, about 39.8% combined.
- Personal goodwill sold by the owner avoids the corporate layer, but in Howard v. United States (9th Cir. 2011) a noncompete with the owner’s own company made the goodwill corporate.
How is goodwill taxed when you sell a business?
Goodwill is taxed by who owns it and how it got on the books. Self-created goodwill held by an individual, partnership or S corporation produces long-term capital gain at 0%, 15% or 20%. Bought and amortized goodwill is partly ordinary income. Goodwill inside a C corporation is taxed twice. The IRS Sale of a Business page treats each asset as sold separately.
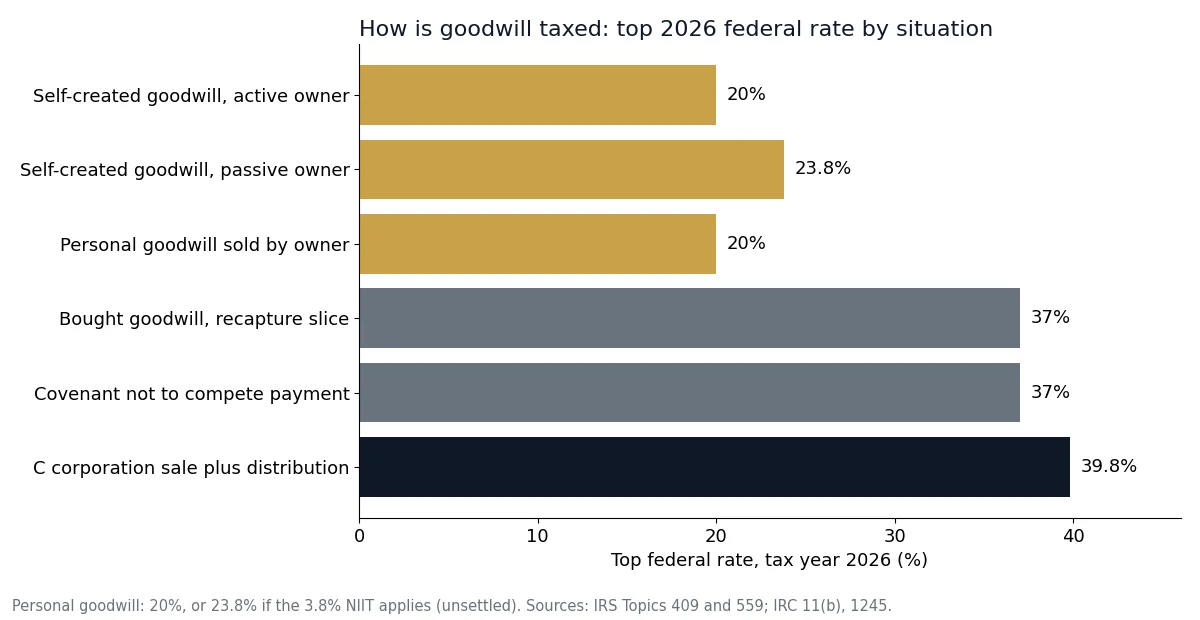
| Goodwill situation | Tax character | Top federal rate, 2026 | Source |
|---|---|---|---|
| Self-created goodwill, LLC, partnership or S corporation, owner materially participates | Long-term capital gain | 20% | IRS Topic 409; IRC 1221 |
| Same, owner is passive | Long-term capital gain plus NIIT | 23.8% | IRS Topic 559 |
| Goodwill bought earlier and amortized | Ordinary up to amortization taken, then Section 1231 gain | 37% on the recapture slice | IRC 197(f)(7); IRC 1245 |
| C corporation sells goodwill and distributes cash | Corporate gain, then shareholder gain or dividend | 39.8% combined | IRC 11(b); Topic 409 |
| Personal goodwill sold by the owner | Long-term capital gain | 20%, NIIT unsettled | The Tax Adviser, 2016 |
| Payment for a covenant not to compete | Ordinary income | 37% | The Tax Adviser, 2014 |
Which 2026 capital gains bracket does goodwill land in?
Goodwill gain stacks on top of your other taxable income, so a seven-figure sale lands mostly in the 20% band. IRS Rev. Proc. 2025-32 sets the 2026 ceilings below; the 3.8% NIIT starts at $250,000 of joint or $200,000 of single modified AGI and is not indexed.
| Filing status, 2026 | 0% rate up to | 15% rate up to | 20% rate above | NIIT threshold |
|---|---|---|---|---|
| Married filing jointly | $98,900 | $613,700 | $613,700 | $250,000 |
| Single | $49,450 | $545,500 | $545,500 | $200,000 |
| Head of household | $66,200 | $579,600 | $579,600 | $200,000 |
State tax sits on top: 0% in Texas and Florida, up to 13.3% in California, and 7% or 9.9% in Washington. The full state table is in our guide to how much tax you pay when you sell a business.
Is goodwill a capital asset or Section 1231 property?
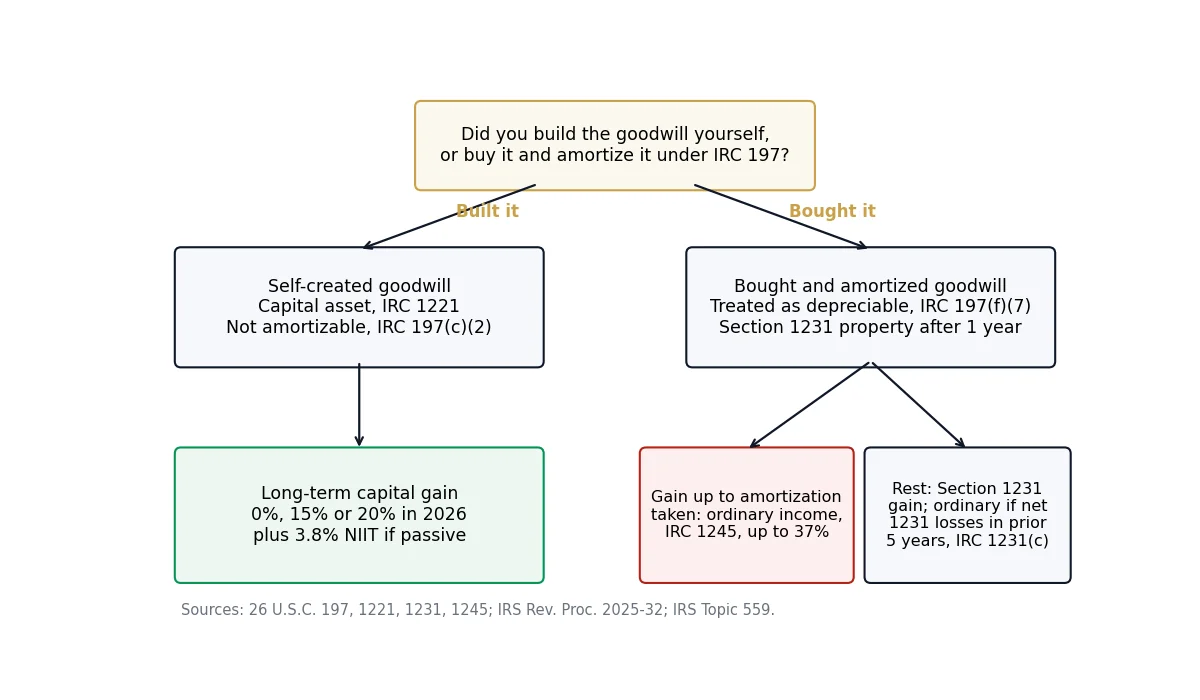
Self-created goodwill is a capital asset under IRC Section 1221 because it is not property “of a character which is subject to the allowance for depreciation.” Section 197(c)(2) bars amortizing goodwill you built yourself. Goodwill you bought in an earlier acquisition is different: Section 197(f)(7) treats it as depreciable, which makes it Section 1231 property after one year.
That split creates a trap most top results skip. If you bought a competitor in 2018 and amortized its goodwill over 15 years under IRC Section 197(a), the gain on that goodwill is ordinary income up to the amortization you deducted. Section 1231(c) adds a second trap: net 1231 losses from the 5 preceding tax years turn the same amount of this year’s 1231 gain into ordinary income.
| If your goodwill is… | Character on sale | Statute | Where it is reported |
|---|---|---|---|
| If self-created and held more than 1 year | Long-term capital gain | IRC 1221(a), 197(c)(2) | Class VII on Form 8594; your CPA picks the return line |
| If bought and amortized | Ordinary up to amortization, rest Section 1231 | IRC 197(f)(7), 1245(a)(1), 1231(b) | Form 4797: recapture as Section 1245 property |
| If you had net 1231 losses in the last 5 years | Ordinary up to those losses | IRC 1231(c) | Form 4797 |
| If held 1 year or less | Short-term, ordinary rates | IRS Topic 409 | Form 4797 or Form 8949 |
How much tax is due on goodwill in a C corporation sale?
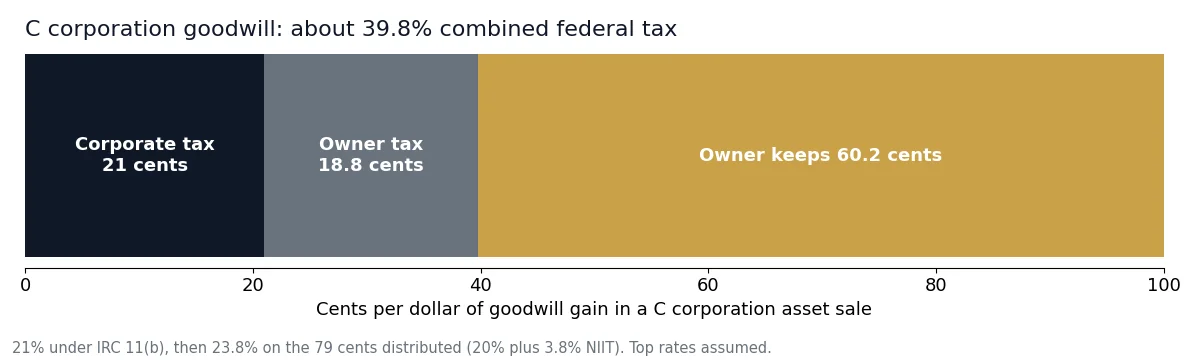
A C corporation that sells goodwill in an asset sale pays 21% under IRC Section 11(b), then the owner pays up to 23.8% when the remaining cash is distributed. On each dollar of gain that is 21 cents plus 23.8% of the remaining 79 cents, or 39.8% combined. The owner keeps about 60.2 cents of each dollar, after 21 cents of corporate tax and 18.8 cents of shareholder tax. A stock sale avoids the corporate layer, which is why C corporation owners usually push for one.
S corporations escape the double tax with one exception. Under IRC Section 1374, an S corporation that converted from C status pays the 21% built-in gains tax on goodwill that existed at conversion if it sells within the 5-year recognition period. Our page on S corp asset sale goodwill covers that case.
What is personal goodwill, and when does the IRS accept it?
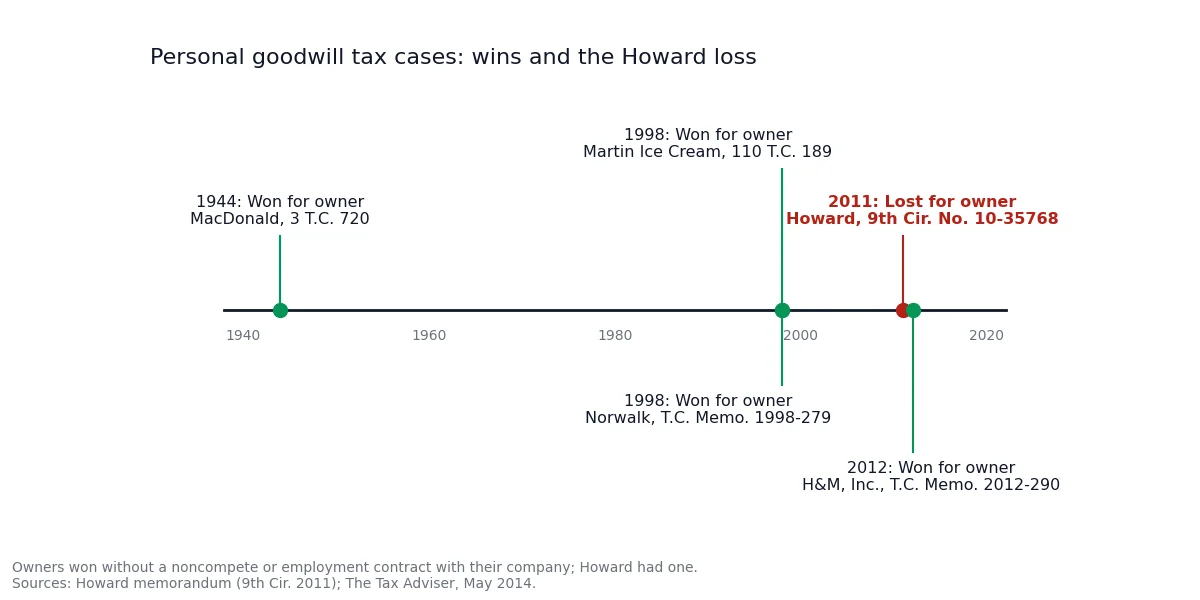
Personal goodwill is value tied to the owner’s own relationships and skill, owned by the owner rather than the company. The Tax Court accepted it in Martin Ice Cream Co. v. Commissioner, 110 T.C. 189 (1998), because the founder had no employment contract or covenant not to compete with his corporation. The owner sells it directly to the buyer, so a C corporation never pays the 21% layer on that slice.
| Case | Year | Result for owner | Deciding fact |
|---|---|---|---|
| MacDonald v. Commissioner, 3 T.C. 720 | 1944 | Won | Corporation had no contract right to his future services |
| Martin Ice Cream Co. v. Commissioner, 110 T.C. 189 | 1998 | Won | No employment contract or noncompete with the corporation |
| Norwalk v. Commissioner, T.C. Memo. 1998-279 | 1998 | Won | Accountants had no enforceable noncompete with their firm |
| Howard v. United States, 9th Cir. No. 10-35768 | 2011 | Lost | Noncompete with his own corporation while a shareholder plus 3 years |
| H&M, Inc. v. Commissioner, T.C. Memo. 2012-290 | 2012 | Won | Goodwill belonged to the shareholder, so his pay was not disguised price |
Howard is the warning case. Dr. Howard’s purchase agreement called the goodwill “a personal, non-corporate asset,” yet the Ninth Circuit held that “self-serving language in a purchase agreement is not a substitute for a careful analysis” and the IRS taxed the proceeds as a corporate dividend. Owners who signed a noncompete with their own company years ago start from the Howard facts.
The steps practitioners use to support a personal goodwill sale, drawn from the Payne analysis in The Tax Adviser (2014) and the Howard opinion:
- Check every employment agreement, noncompete and bill of sale between you and your company; any of them can move the goodwill to the entity, as in Howard.
- Commission a qualified valuation that splits personal and enterprise goodwill before the LOI is signed.
- Sign two purchase agreements and two bills of sale: one for the company’s assets, one for your personal goodwill.
- Agree a transition period long enough to transfer the relationships, with introductions or training written into the contract.
- Price any noncompete with the buyer separately; that payment is ordinary income, so each dollar moved from goodwill to the covenant goes from 20% to up to 37%.
Does the 3.8% NIIT apply to personal goodwill?
No statute or regulation answers it directly. Christopher Hesse argued in The Tax Adviser (May 2016) that most personal goodwill sales should escape the 3.8% NIIT, because personal goodwill is a personally developed intangible and not passive income under IRC Section 1411(c)(1)(A)(iii). Ask your CPA to model both outcomes.
Worked example: the same goodwill under four structures
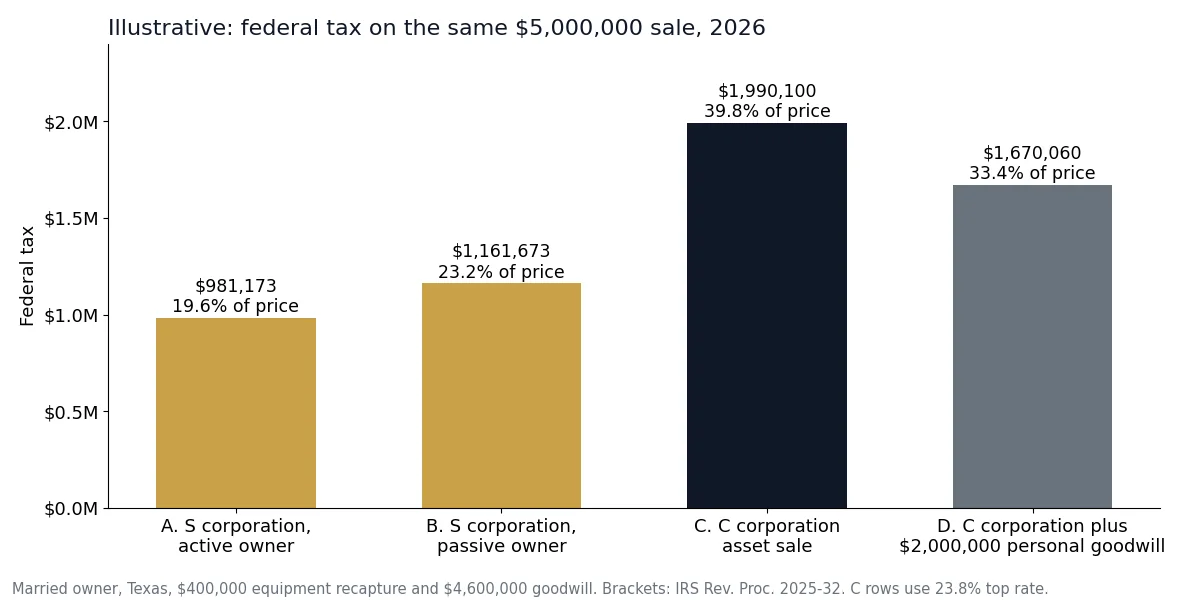
Illustrative: a married owner in Texas sells for $5,000,000 in 2026 with no other income: $400,000 to fully depreciated equipment (Class V) and $4,600,000 to self-created goodwill (Class VII). C corporation rows use the 23.8% top rate on the whole distribution and zero stock basis, a simplification.
| Structure (illustrative) | Arithmetic | Federal tax | Share of price | Owner keeps |
|---|---|---|---|---|
| A. S corporation, active owner | Ordinary tax $73,468 on $367,800; $245,900 at 15% = $36,885; $4,354,100 at 20% = $870,820 | $981,173 | 19.6% | $4,018,827 |
| B. S corporation, passive owner | A plus 3.8% NIIT on $4,750,000 = $180,500 | $1,161,673 | 23.2% | $3,838,327 |
| C. C corporation asset sale | Corporate $1,050,000; owner 23.8% of $3,950,000 = $940,100 | $1,990,100 | 39.8% | $3,009,900 |
| D. C corporation plus $2,000,000 personal goodwill | Corporate $630,000; owner $564,060 on $2,370,000; $476,000 on personal goodwill | $1,670,060 | 33.4% | $3,329,940 |
Structure D saves $320,040 against C if the 3.8% NIIT applies to the personal goodwill and $396,040 if it does not. Structure A shows why a pass-through owner gains little from a personal goodwill carve-out: the goodwill is already taxed once at 20%.
Why does the buyer care how much goes to goodwill?
The buyer deducts goodwill over 15 years under IRC Section 197(a), so $4,600,000 of goodwill gives it $306,667 of deductions a year. Equipment in Class V is usually recovered faster, which is why buyers push price toward Class V while sellers want goodwill. Form 8594 must show the same split on both returns, so settle it in the purchase price allocation schedule.
| Form 8594 class | Assets | Seller’s tax character | Buyer’s recovery |
|---|---|---|---|
| III and IV | Receivables, inventory | Ordinary income | Collected or sold |
| V | Equipment, vehicles, buildings, land | Section 1245 recapture as ordinary, rest Section 1231 | Depreciation |
| VI | Section 197 intangibles other than goodwill, including a noncompete | Capital gain if self-created; noncompete ordinary | 15-year amortization |
| VII | Goodwill and going concern value | Capital gain if self-created | 15-year amortization |
In a stock sale no goodwill changes hands; you pay capital gain on the shares. A Section 338(h)(10) election turns a stock sale of an S corporation into an asset sale for tax: under Treas. Reg. 1.338(h)(10)-1(c) the corporate buyer and the S corporation shareholders elect jointly on Form 8023 after a qualified stock purchase.
Which goodwill tax move fits your situation?
Use the thresholds below before you sign an LOI, because the allocation and any personal goodwill sale are usually written into the letter of intent. Each row names the rule that sets the outcome.
| If your situation is… | Then | Rule |
|---|---|---|
| If you own a C corporation and never signed an employment agreement or noncompete with it | Value personal goodwill before the LOI and sell it under a separate agreement | Martin Ice Cream, 110 T.C. 189 |
| If you own a C corporation and signed a noncompete with it | Expect the IRS to treat goodwill as corporate; push for a stock sale and check QSBS under Section 1202 | Howard, 9th Cir. 2011 |
| If your S corporation converted from a C corporation less than 5 years ago | Model the 21% built-in gains tax on pre-conversion goodwill, or close after the 5-year mark | IRC 1374(d)(7) |
| If you materially participate in an S corporation or LLC | Expect 20% top rate on goodwill and no NIIT | IRC 1411(c)(4); Topic 559 |
| If you are a passive owner with joint MAGI over $250,000 | Add 3.8% NIIT to the goodwill gain | IRC 1411(a) |
| If the company amortized goodwill from an earlier acquisition | Ask your CPA for the Section 1245 recapture amount before you agree the allocation | IRC 197(f)(7), 1245 |
| If the buyer wants a large noncompete allocation | Move value back to goodwill; covenant payments are ordinary income | IRC 197(d)(1)(E) |
If the sale price is paid over time, the goodwill gain can be spread under the installment method, but Section 1245 recapture is taxed in the year of sale.
What do most guides get wrong about goodwill tax?
Four claims circulate on the first page of Google that the primary sources contradict. We checked each one against the statute, the IRS form instructions or the court opinion.
| Common claim | What the primary source says |
|---|---|
| Goodwill is always taxed at 23.8% | The 3.8% NIIT does not apply to income from an active business (IRS Topic 559), so many owner-operators pay 20% |
| All goodwill is capital gain | Bought goodwill is depreciable under IRC 197(f)(7); gain up to amortization is ordinary under IRC 1245 |
| Calling it personal goodwill in the purchase agreement is enough | Howard (9th Cir. 2011): substance over form; the proceeds were taxed as a dividend |
| Howard established personal goodwill | The taxpayer lost; Martin Ice Cream (1998) and H&M (2012) are the owner wins |
Considering selling your business?
CT Acquisitions helps owners of founder-owned businesses make the most of their exit through a confidential sale, a recapitalization or exit planning, with a 500+ buyer network. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells. Try our free valuation calculator for a starting-point range first if you prefer.
How we compiled this
We compiled this page in November 2026 from 19 primary documents: IRS Rev. Proc. 2025-32, IRS Topics 409 and 559, the Form 8594 and Form 4797 instructions, the IRS Sale of a Business page, 7 Internal Revenue Code sections, Treas. Reg. 1.338(h)(10)-1, the Howard opinion read in full, and 4 state revenue sources. Two practitioner articles in The Tax Adviser supplied case summaries; we excluded forum posts. The examples are our own arithmetic.
Frequently asked questions
Does goodwill pay taxes when you sell a business?
Yes. The seller pays tax on the gain allocated to goodwill, which is usually the whole amount because self-created goodwill has zero basis. For 2026 the federal rate is 0%, 15% or 20% as long-term capital gain, plus 3.8% NIIT for passive owners. The buyer then deducts the goodwill over 15 years under IRC Section 197.
Is goodwill taxed as ordinary income?
Self-created goodwill is not: it is a capital asset under IRC Section 1221 and taxed at long-term capital gain rates. Goodwill your company bought and amortized is ordinary income up to the amortization deducted, under Sections 197(f)(7) and 1245. Payments for a covenant not to compete are ordinary income at up to 37%.
Is goodwill a 1231 asset?
Purchased goodwill held more than one year is Section 1231 property, because IRC Section 197(f)(7) treats amortizable intangibles as depreciable. Self-created goodwill is not amortizable under Section 197(c)(2), so it is a capital asset under Section 1221. Net 1231 gain is taxed as long-term capital gain unless net 1231 losses from the prior 5 years recapture it.
What is the goodwill tax rate in 2026?
For 2026 the federal rate on long-term goodwill gain is 0% up to $98,900 of joint taxable income, 15% up to $613,700 and 20% above, per IRS Rev. Proc. 2025-32. Passive owners add 3.8% NIIT. Goodwill sold by a C corporation carries about 39.8% combined once the cash is distributed.
Is personal goodwill subject to the 3.8% NIIT?
The IRS has not ruled on it. A May 2016 analysis in The Tax Adviser concluded that most personal goodwill sales should not be subject to the NIIT, because the goodwill is a personally developed intangible rather than passive income under IRC Section 1411(c)(1)(A)(iii). Model the sale with and without the 3.8% before you rely on it.
Where do you report the sale of goodwill?
Buyer and seller each attach IRS Form 8594 to the return for the year of sale, showing goodwill in Class VII. Recapture on goodwill your company amortized goes on Form 4797 as Section 1245 property. The gain then flows to your return through Schedule K-1 if an S corporation or partnership sold the goodwill.
Sources
- IRS: Rev. Proc. 2025-32; Topics 409 and 559; Instructions for Form 8594; Instructions for Form 4797; Sale of a Business. Accessed November 2026.
- 26 U.S.C. sections 11, 197, 1221, 1231, 1245, 1374 and 1411; Treas. Reg. 1.338(h)(10)-1 (Cornell LII). Accessed November 2026.
- Howard v. United States, No. 10-35768 (9th Cir. Aug. 29, 2011), memorandum. Martin Ice Cream Co., 110 T.C. 189 (1998), as quoted in Howard.
- Payne, “Goodwill as Part of a Corporate Asset Sale,” The Tax Adviser, May 2014; Hesse, “Personal Goodwill and Net Investment Income Tax,” The Tax Adviser, May 2016.
- State: California FTB 2025 Form 540 booklet; Washington DOR; Tex. Const. art. 8, sec. 24-a; Florida DOR. Accessed November 2026.
Related Guide: How Much Tax When You Sell a Business, Federal capital gains, state taxes, and the structural choices that move 15-25% of net proceeds.
Related Guide: Asset Sale vs Stock Sale: Which Is Right for You, The structural choice that determines your tax bill, your liability exposure, and which buyers will bid.
Related Guide: Quality of Earnings (QoE), What Buyers Test, What QoE analysts test, what they reject, and how to prepare.
Related Guide: 2026 LMM Buyer Demand Report, Aggregated buy-box data from 76 active U.S. lower middle market buyers.
Want a Specific View of Your Business?
30 minutes, confidential, no contract, no cost. You leave with a view of your local buyer market and a likely valuation range.
