The 2026 Waste Hauling Private Equity Roll-Up Tracker: Active Platforms, Sponsors and Dated Deals
Waste hauling private equity in 2026 runs through sponsor-backed platforms such as Ecowaste (Kinderhook), Meridian (Warren Equity), TXP (NMS Capital) and Coastal (Macquarie), which compete with WM, Republic, Waste Connections, GFL and Casella for independent haulers.
By Christoph Totter, Founder of CT Acquisitions · Last reviewed: November 2026
This edition was rebuilt in November 2026. Every owner, sponsor and dated deal below is tied to a filing, a company or sponsor release, or a named trade report. Platforms and figures we could not confirm were removed; the corrections are listed under How we compiled this.
Key takeaways
- Kinderhook closed a $1.0 billion continuation vehicle for Ecowaste Solutions on January 16, 2026, merging Live Oak Environmental and CARDS Recycling into one hauler with more than 400,000 customers in 9 states (Kinderhook Industries, Jan 16, 2026).
- Public consolidators kept buying in 2025: Republic Services invested $1.1 billion in acquisitions, WM about $400 million, and Waste Connections added about $330 million of annualized revenue (Republic Services FY2025 results).
- Financial buyers made 55.1% of waste and recycling deals from January to mid August 2025, and PE add-ons alone were 54 of 98 deals (Capstone Partners, Aug 25, 2025).
- A single regional hauler might trade at 5x to 6x EBITDA, while a platform of 10 haulers can exit at 9x to 10x (Waste Advantage Magazine, Jul 15, 2026). That spread is the reason platforms want your routes.
- Two sponsors are past the 6.0-year typical private equity hold: Warren Equity at Meridian Waste (8.6 years) and Macquarie at WIN Waste (about 7.9 years), measured against Private Equity Info, Sep 7, 2026.
- GFL set a November 9, 2026 deadline for take-private proposals, so the buyer that took Frontier Waste in Texas may itself become privately owned (Waste Dive, Oct 29, 2026).
Who is buying waste hauling companies in 2026?
Fourteen buyers set the price for independent haulers in 2026: five public consolidators (WM, Republic Services, Waste Connections, GFL, Casella), one founder-owned buyer (Waste Pro USA) and eight sponsor-backed platforms, one of which (Frontier Waste) exited to GFL in April 2026. The table names each owner, when that owner arrived and the latest hauling deal we could tie to a dated document as of November 9, 2026.
| Buyer | Owner or sponsor (since) | Footprint | Latest dated hauling deal found | Source |
|---|---|---|---|---|
| WM (NYSE: WM) | Public | National | About $400M of solid waste and recycling acquisitions in 2025; WB Waste Solutions (MD/DC), May 2025 | WM FY2025 release |
| Republic Services (NYSE: RSG) | Public | National | $1.1B of acquisitions in 2025; about $400M invested in 2026 by Feb 17, 2026 | RSG FY2025 release |
| Waste Connections (NYSE: WCN) | Public | US secondary and rural markets, Canada | About $330M of acquired annualized revenue in 2025; Florida Express Environmental (Marion County, FL), Nov 2025; NYC routes alongside IWS, Nov 2025 | WCN Q4 2025 release |
| GFL Environmental (NYSE: GFL) | Public; take-private proposals due Nov 9, 2026 | US and Canada | Frontier Waste Solutions (Texas), announced Apr 1, 2026; Superior Waste (Oklahoma), Sep 2025 | Waste Dive |
| Casella Waste Systems (NASDAQ: CWST) | Public | Northeast, Mid-Atlantic, West Virginia | Nine businesses, about $115M revenue, in 2025; Mountain State Waste (WV), Jan 1, 2026, about $30M | Casella FY2025 release |
| Waste Pro USA | Private, founder John Jennings | Southeast | 24 acquisitions for $170M, Jan to Sep 2025; 15 for $140M in 2024 | Waste360 |
| Ecowaste Solutions | Kinderhook Fund 8, Goldman Sachs Alternatives, Apollo S3 (continuation vehicle, Jan 16, 2026) | AL, AR, FL, KS, LA, MS, MO, OK, TX | Gardner Disposal (Kansas City metro) and Baker Trash Service (Inola, OK), Jan 2026; Howie’s Enterprises (Manhattan, KS), early 2026 | Kinderhook release |
| Meridian Waste | Warren Equity Partners (Apr 2018) | Southeast; HQ Charlotte, NC | Evergreen Environmental Partners and ADSI, incl. Noble Hill MSW Landfill (AL), effective Sep 1, 2024; 35 add-ons to date | Meridian release |
| Apex Waste Solutions | Kinderhook Industries (Nov 2023) | Colorado Front Range and Western Slope | Twin Enviro Services and certain WM of Colorado assets, mid 2024 (deals three and four) | Waste Dive |
| TXP Environmental | NMS Capital (Texas Pride recap, Apr 28, 2023) | Texas: Houston, West and South Texas | Diamond Back Recycling and Sanitary Landfill (Odessa, TX), Jan 27, 2026, its fifth deal | Waste360 |
| Coastal Waste & Recycling | Macquarie Asset Management, majority (Jun 13, 2023) | Florida, Georgia | No dated add-on found in a primary source since the 2023 recap | Macquarie release |
| Interstate Waste Services (IWS) | Littlejohn & Co. (2020) and Ares (Oct 24, 2023) | New York City, New Jersey | Bought competitors’ NYC routes and a Queens transfer station with Waste Connections, Nov 2025 | Waste Dive |
| WIN Waste Innovations | Macquarie Infrastructure and Real Assets (early 2019) | Northeast collection plus waste-to-energy | Sold a Broward County, FL waste-to-energy plant to FCC, Apr 2025 | Waste Dive |
| Frontier Waste Solutions (exited) | Summer Street and Concentric (majority, 2022) to GFL (Apr 2026) | Texas: 24 locations, 665 vehicles | Sale to GFL; terms not disclosed | Sellers’ release |
Who owns Live Oak Environmental now?
Live Oak Environmental no longer trades as a standalone platform. On January 16, 2026, Kinderhook merged it with CARDS Recycling into Ecowaste Solutions, a Coppell, Texas hauler with about $300 million of annual revenue, more than 600 vehicles and three landfills (Waste Dive, Feb 5, 2026). Live Oak and CARDS had completed more than 35 add-on acquisitions under Kinderhook before the merger.
Gardner Disposal, the hauler behind the search “Live Oak Environmental Gardner KS”, joined Ecowaste in January 2026 as its Kansas City flagship, alongside Baker Trash Service of Inola, Oklahoma; the two run close to 20 daily routes (Waste360, Jan 2026). PitchBook records the Gardner buyer as Live Oak Environmental on January 20, 2026, which reflects the entity name used days after the merger. Ecowaste says it targets independent haulers with under $10 million of annual revenue, the size band WM and Republic often pass on.
How much are the public consolidators spending on acquisitions?
The five public waste companies still set the ceiling on price. In 2025 Republic Services invested $1.1 billion in acquisitions, WM about $400 million, Waste Connections bought about $330 million of annualized revenue and Casella about $115 million. Republic planned about $1 billion more for 2026. These buyers pay most for haulers whose volume can go into their own landfills.
| Buyer | 2025 acquisition measure | Detail | Source |
|---|---|---|---|
| Republic Services | $1.1B invested | Acquisitions added 1.3 points of 3.5% revenue growth; about $1B planned for 2026 | RSG release, Feb 17, 2026 |
| WM | About $400M invested | Solid waste and recycling tuck-ins; Stericycle ($7.2B EV) closed Nov 4, 2024 | WM release, Jan 28, 2026 |
| Waste Connections | About $330M annualized revenue acquired | 2025 revenue $9.467B | WCN release, Feb 11, 2026 |
| Casella | About $115M annualized revenue (9 deals) | Plus Mountain State Waste, about $30M, Jan 1, 2026; about $145M combined | Casella FY2025 release |
| Waste Pro USA (private) | $170M invested (24 deals, Jan to Sep) | 12 of the deals in Louisiana and Florida | Waste360, Oct 2025 |
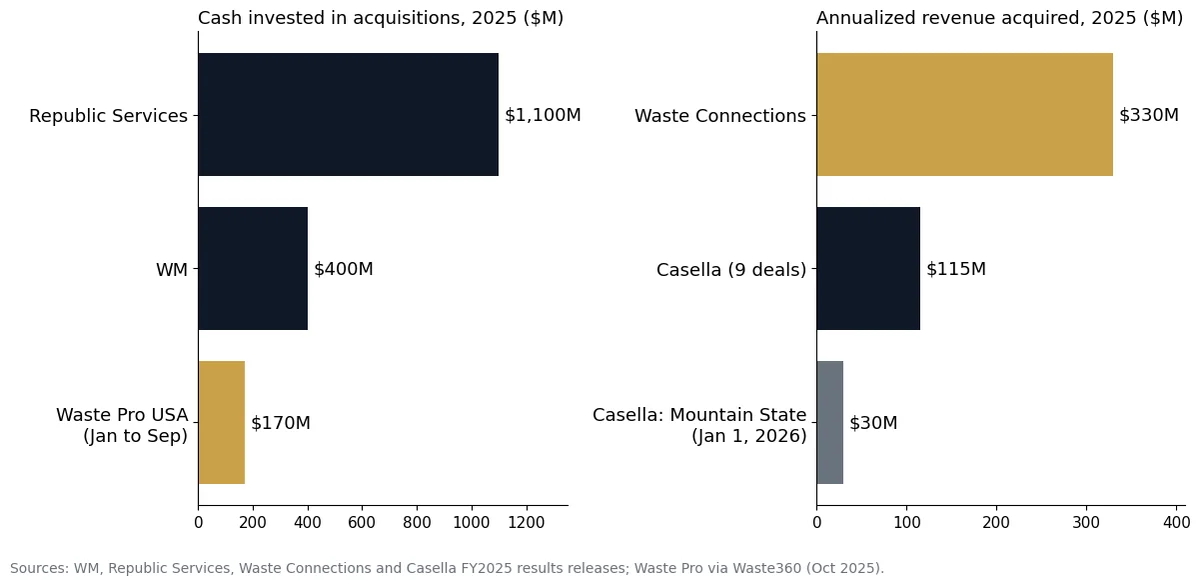
The figures use two different measures, which is why the chart splits them. Republic, WM and Waste Pro report cash invested; Waste Connections and Casella report the annualized revenue of what they bought. Republic’s 2025 Form 10-K explains the appetite: about 67% of the solid waste volume it collected went into landfills it owns or operates, across 207 active landfills and 255 transfer stations. Every hauler it buys near one of those sites adds tons at a disposal margin it already earns.
GFL is the one to watch in late 2026. After announcing Frontier Waste Solutions (24 Texas locations, 665 vehicles, more than 460,000 customers) on April 1, 2026, GFL formed a special committee advised by CIBC and set a November 9, 2026 deadline for take-private proposals, with CEO Patrick Dovigi planning to roll over his stake (Waste Dive, Oct 29, 2026). If you are in GFL’s Texas or Oklahoma footprint, ask any GFL team how a change of control would affect its 2027 acquisition budget.
Is private equity buying more waste haulers than the strategics?
Yes, by deal count. Capstone Partners counted 98 waste and recycling deals from January to mid August 2025, and financial buyers made 55.1% of them: 54 PE add-ons and 8 new PE platforms. Private strategic deals fell from 41 to 22. Cherry Bekaert, citing PitchBook, puts the full 2025 total at 178 closed deals, with PE add-ons up 18.8%.
| Buyer type | Jan to mid Aug 2024 | Jan to mid Aug 2025 | Source |
|---|---|---|---|
| PE add-on | 51 | 54 | Capstone |
| PE platform | 7 | 8 | Capstone |
| Private strategic | 41 | 22 | Capstone |
| Public strategic | 19 | 22 | Capstone |
| Total | 111 | 98 (down 11.7%) | Capstone |
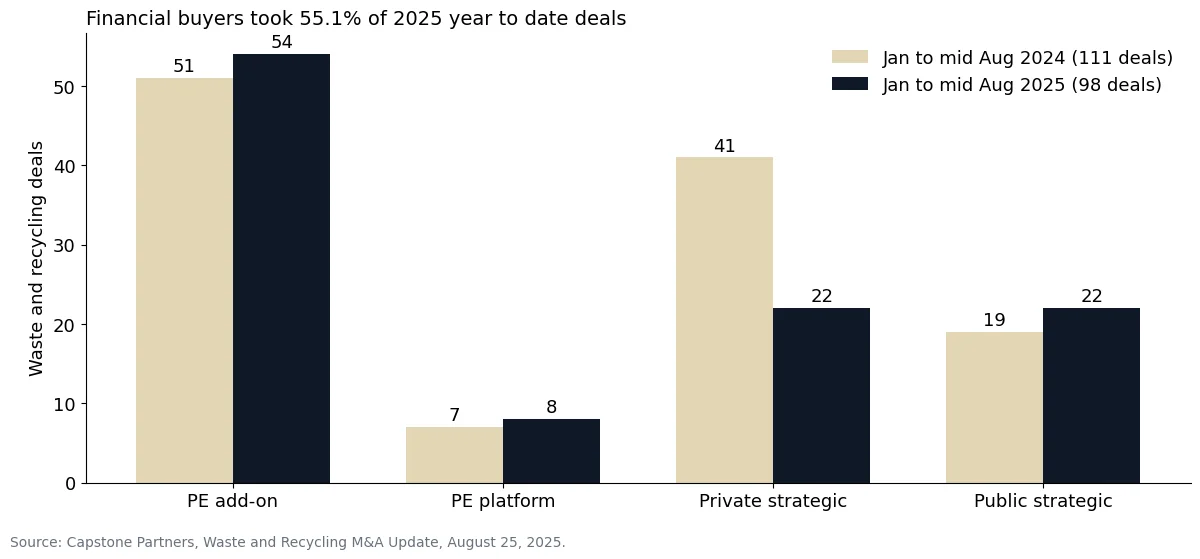
The drop in private strategic buyers matters for a seller. Family-owned regional haulers that used to buy their neighbors made 22 deals in the 2025 period against 41 a year earlier, so an owner who expects to sell to the hauler across town will often find that hauler has become a platform add-on itself. Cherry Bekaert (Jul 2, 2026) puts PE add-ons at about 43% of 2025 volume.
How long has each sponsor held its waste hauling platform?
Private Equity Info puts the typical private equity hold at 6.0 years, based on 13,757 exits from 2021 to mid 2026. Measured at November 9, 2026, Warren Equity has held Meridian Waste for 8.6 years and Macquarie has held WIN Waste for about 7.9 years. Most other hauling platforms in this tracker are three to four years into their holds.
| Platform | Sponsor | Sponsor entry | Years held at Nov 9, 2026 | Status | Source |
|---|---|---|---|---|---|
| Meridian Waste | Warren Equity Partners | April 2018 | 8.6 | Past typical hold | Warren Equity |
| WIN Waste Innovations | Macquarie (MIRA) | Early 2019 | About 7.9 | Past typical hold; Waste Dive notes Macquarie tends to hold about seven years | Waste Dive |
| Interstate Waste Services | Littlejohn; Ares | 2020; Oct 24, 2023 | About 6; 3.0 | Littlejohn at typical hold | Business Wire |
| TXP Environmental | NMS Capital | April 28, 2023 | 3.5 | Mid hold | Waste360 |
| Coastal Waste & Recycling | Macquarie Asset Management | June 13, 2023 | 3.4 | Mid hold | Macquarie |
| Apex Waste Solutions | Kinderhook | November 2023 | 3.0 | Mid hold | Waste Dive |
| Ecowaste Solutions | Kinderhook continuation vehicle | January 16, 2026 | 0.8 | New hold; plan to double in three years | Kinderhook |
| Frontier Waste Solutions | Summer Street, Concentric | 2022 | About 4 at exit | Sold to GFL, April 2026 | Waste Dive |
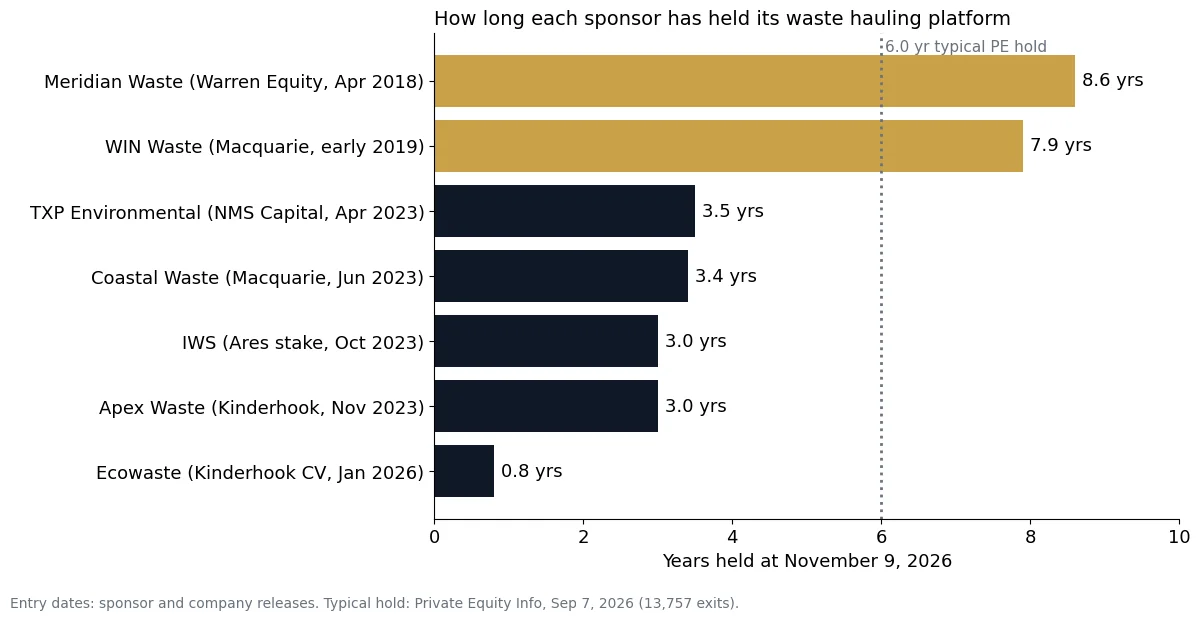
The hold clock changes what rollover equity is worth to you. If you take 20% of your price in platform stock, your second payday arrives when the sponsor sells. A sponsor 8 years into its hold is likely to sell within one to two years, which can mean a fast second check, or a new owner who did not agree to your deal terms. A sponsor in year one, like the Ecowaste vehicle, implies a longer wait. Ask every sponsor buyer when its fund term ends and whether a continuation vehicle, the structure Kinderhook used for Ecowaste, is on the table. Our guide to rollover equity in a business sale covers the tax side.
What do buyers pay for in a waste hauling business?
Buyers pay for revenue they can keep and tons they can route cheaply: dense routes, contracted or franchised customers with price escalators, access to disposal they control, and a fleet that will not need replacing in year one. Republic Services runs about 17,800 collection vehicles at an average age of 7.9 years, so a buyer will compare your fleet age to that benchmark.
| Value driver | What the buyer measures | Why it moves price | Evidence |
|---|---|---|---|
| Route density | Stops per route hour, revenue per truck, overlap with its existing routes | A tuck-in that fills its own trucks is worth more to that buyer than to anyone else | Barrili lists route density with permitted facilities as a barrier to entry (Waste Advantage, Jul 2026) |
| Disposal access and internalization | Where your tons go, at what tip fee, and whether it owns that landfill or transfer station | A buyer that internalizes your volume earns the disposal margin too | Republic disposed about 67% of collected volume in its own landfills in 2025 (10-K) |
| Municipal and franchise contracts | Term left, renewal and assignment clauses, rebid dates | Exclusive territory makes revenue predictable; a rebid inside 18 months is a risk | Waste Connections franchises typically run 7 years or longer (10-K FY2025) |
| Subscription and commercial contracts | Share of revenue under written contract, churn, auto-renewal | Barrili cites 60 to 70% of revenue under contract as earning a higher offer | Waste Advantage, Jul 15, 2026 |
| CPI escalators and pass-throughs | Whether rates move with CPI, fuel and disposal cost indexes | Without them, the buyer prices in margin squeeze from tip fee and fuel increases | Read your contracts; buyers model this line by line |
| Fleet age and fuel | Truck age by line, maintenance records, CNG versus diesel | Old trucks become a capex deduction from price; CNG needs fueling access | Republic average fleet age 7.9 years; part of its fleet runs on CNG (10-K) |
| Landfill liabilities (if you own one) | Remaining airspace, closure cost, post-closure obligations | The buyer inherits 30 years of post-closure care and the financial assurance | 40 CFR 258.61 and Part 258 Subpart G |
If you own a landfill, the federal rules travel with it. Under 40 CFR Part 258, the EPA rule for municipal solid waste landfills, section 258.61 sets post-closure care at 30 years, and Subpart G requires financial assurance for closure, post-closure care and any corrective action. Expect a buyer to price the gap between your recorded closure reserve and its own engineer’s estimate.
For the price math by segment (pure hauling, hauling plus transfer, landfill owners), see our waste hauling business valuation guide.
What multiple does a waste hauling business get from private equity?
A single regional hauler might trade at five or six times EBITDA, and a platform of 10 regional haulers stitched together can exit at nine or 10 times, according to a July 15, 2026 Waste Advantage Magazine column by Samuele Barrili. Platforms buy at the lower multiple and sell at the higher one. Your negotiating goal is to keep more of that spread.
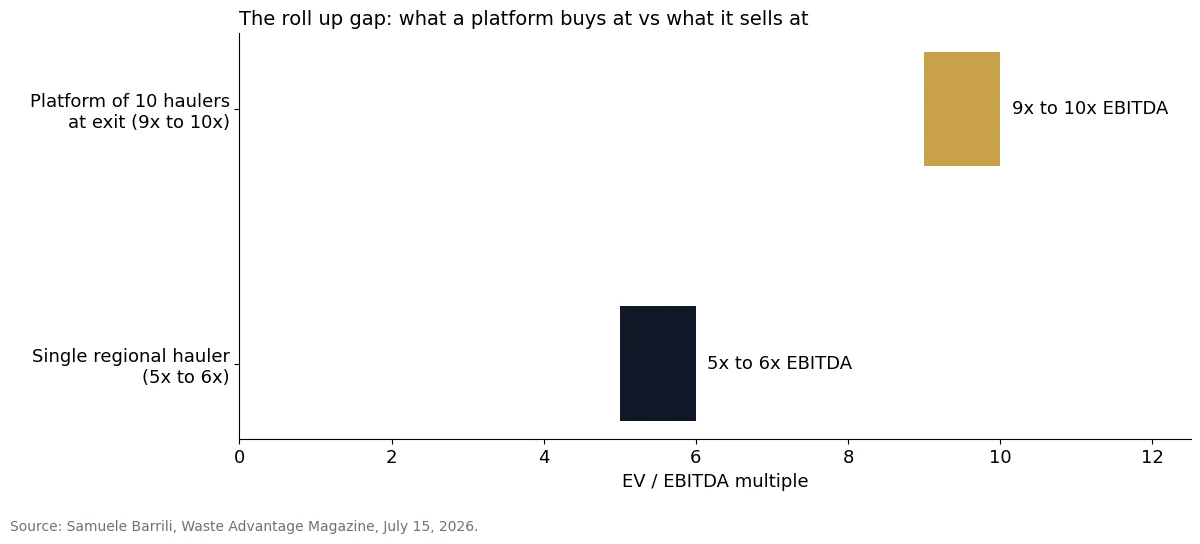
The worked example below is illustrative (CT Acquisitions estimates), using the $3.0 million EBITDA figure from the Barrili column and the midpoints of his two ranges.
| Line | Amount | Arithmetic |
|---|---|---|
| Your adjusted EBITDA | $3.0M | Given |
| Value as a standalone hauler at 5.5x | $16.5M | $3.0M x 5.5 |
| Same EBITDA inside a platform valued at 9.5x | $28.5M | $3.0M x 9.5 |
| Spread the platform captures if it pays 5.5x | $12.0M | $28.5M minus $16.5M |
| If you roll 20% of a $16.5M price | $3.3M in platform stock, $13.2M cash at close | $16.5M x 20% |
| Typical escrow of 10% (illustrative) | $1.65M held back | $16.5M x 10% |
Two levers move you up from 5.5x. The first is competition: a platform with routes next to yours, a public strategic with a landfill nearby and a second platform that wants to enter your market each value the same $3.0 million differently, and only a run process shows you the highest number. The second is the rollover: the $3.3 million you leave in platform stock shares in the exit multiple, which is how some owners recover part of the spread.
How are waste hauling private equity deals structured?
Most platform deals pay the bulk of the price in cash at closing and hold back part of it through rollover equity, escrow and sometimes an earnout. At the top of the market the same pattern holds: when GFL bought Frontier Waste in April 2026, CEO John Gustafson and other managers reinvested about $100 million of their proceeds in GFL shares, according to Waste Dive.
- Letter of intent. Price, cash versus rollover split, working capital target and exclusivity, usually 60 to 90 days. Read it as the deal: most terms rarely improve after you sign.
- Quality of earnings. The buyer’s accountants rebuild your EBITDA, route by route, and test fuel, disposal and driver pay. Our guide on reading a quality of earnings report shows what to check.
- Working capital peg. Waste receivables swing with billing cycles, so agree the average month used. See net working capital adjustments.
- Contract and permit assignment. Municipal contracts and transfer station permits often need consent or a state filing; list each one and its approval body before signing.
- Rollover, escrow and earnout. Rollover gives you platform stock; escrow covers indemnity claims; an earnout ties part of the price to post-close revenue, so define how acquired routes are counted.
- Your role after closing. Employment or consulting term, non-compete radius and length, and who runs your drivers.
Which waste hauling buyer should you call first?
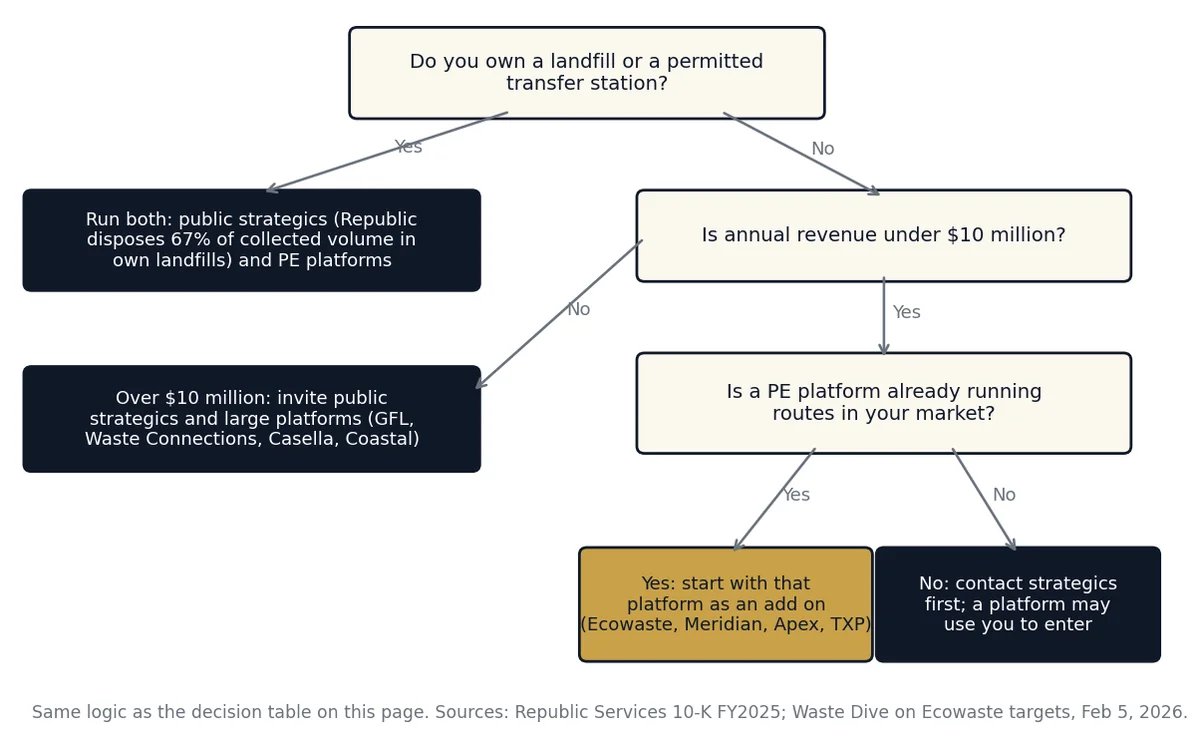
Start from what you own and where you operate. A hauler with its own landfill or permitted transfer station should invite both public strategics and platforms; a sub $10 million route business inside an active platform’s footprint usually gets its best number as an add-on to that platform. The table maps each situation to named buyers from this tracker.
| If your situation is | Then | Named buyers to approach |
|---|---|---|
| If you own a landfill or permitted transfer station | Invite public strategics and platforms together | Republic, Waste Connections, GFL, Casella; Meridian bought a landfill in 2024 |
| If revenue is under $10 million and a platform already runs routes in your market | Start with that platform as an add-on | Ecowaste (KS, OK, TX, LA, AR and more), Apex (Colorado), TXP (Texas), Meridian (Southeast) |
| If revenue is over $10 million | Run a process with large platforms and strategics | GFL, Waste Connections, Casella, Coastal, IWS, Waste Pro |
| If you run commercial routes in New York City | Call the two active NYC buyers first | IWS and Waste Connections (NYC route purchases, Nov 2025) |
| If you want a second payday from rollover | Choose a sponsor early in its hold, or get a clear exit date | Ecowaste (0.8 years), Apex (3.0); ask Meridian and WIN about timing |
| If you want all cash and a clean exit | Favor a public strategic | WM, Republic, Waste Connections, Casella |
| If most revenue is one municipal contract up for rebid within 18 months | Fix the rebid before you sell, or expect price protection | Any buyer will discount or earn out that revenue |
Owners in Texas can compare this list with our guide to selling a waste hauling business in Texas.
What should you ask a waste hauling buyer before you sign an LOI?
Ask questions that expose how the buyer will pay and what happens after closing. The eight below come from the deal terms in this tracker: who owns the buyer and for how long, where your tons will go, how your contracts transfer and what part of the price is not cash at closing. Write the answers into the LOI where you can.
- Who owns you, since when, and when does your fund or hold period end?
- Will my volume go to your landfill or transfer station, and does your price include that disposal margin?
- Which of my municipal contracts need consent to assign, and who asks the city?
- What share of the price is cash at closing, rollover, escrow and earnout?
- If I roll equity, what multiple did you pay for your platform and what happens to my stock if you are sold?
- How will you treat fleet age in the working capital or capex adjustments?
- Who will run my drivers and dispatch, and do my employees keep their pay and routes?
- How many hauling add-ons have you closed in the last 12 months, and may I call two of those sellers?
How we compiled this
We compiled this tracker from 29 documents accessed in November 2026: SEC filings and results releases from WM, Republic Services, Waste Connections and Casella; sponsor and company releases from Kinderhook, Warren Equity, Meridian, Macquarie and Littlejohn; trade reports in Waste Dive, Waste360 and Waste Advantage; Capstone Partners and Cherry Bekaert deal counts; and the federal landfill rule. We did not survey buyers or use deal-database estimates.
Corrections from the June 2026 edition: the GFL Environmental Services sale was C$8.0 billion (about US$5.6 billion), not US dollars; the Frontier price is undisclosed, and the $900 million figure is a Bloomberg report from an unnamed source; Coastal’s 2023 terms were not disclosed; the Republic Services Cumming, Georgia operations moved to Waste Pro in 2024, not 2025; Meridian now counts 35 add-ons. Hazardous waste, medical waste and waste-to-energy deals were removed to keep the focus on haulers, along with unsourced counts and multiples.
Frequently asked questions
Is private equity buying waste hauling companies?
Yes. Financial buyers made 55.1% of waste and recycling deals from January to mid August 2025, with 54 PE add-ons out of 98 deals, per Capstone Partners. Active sponsor platforms include Ecowaste Solutions (Kinderhook, Goldman Sachs Alternatives, Apollo S3), Meridian Waste (Warren Equity), TXP Environmental (NMS Capital), Apex Waste Solutions (Kinderhook) and Coastal Waste and Recycling (Macquarie).
Who owns Live Oak Environmental now?
Kinderhook Industries merged Live Oak Environmental with CARDS Recycling into Ecowaste Solutions on January 16, 2026, through a $1.0 billion continuation vehicle backed by Kinderhook Fund 8, Goldman Sachs Alternatives and Apollo S3. Ecowaste serves more than 400,000 customers in 9 states and added Gardner Disposal in the Kansas City metro in January 2026.
What multiple will private equity pay for a waste hauling business?
A single regional hauler might trade at five or six times EBITDA, while a platform of 10 haulers can exit at nine or 10 times, according to Waste Advantage Magazine in July 2026. Where you land depends on route density, contracted revenue, disposal access and fleet age, and on how many buyers compete for your routes.
Should I sell to a PE platform or to WM, Republic or Waste Connections?
Sell to whoever values your tons most. Public strategics pay for volume they can put in their own landfills: Republic disposed about 67% of collected volume at sites it owns or operates in 2025. Platforms pay for density inside their footprint and usually offer rollover equity. Inviting both types gives you the real market price.
Do I keep equity when I sell to a waste hauling platform?
Often yes. Sponsor-backed platforms usually ask owners to roll part of the price into platform stock, which pays out when the sponsor sells. Check the hold clock first: Warren Equity has held Meridian Waste for 8.6 years, against a 6.0-year typical private equity hold reported by Private Equity Info in September 2026.
Can CT Acquisitions help me sell my waste hauling business?
Yes. CT Acquisitions runs confidential sales, recapitalizations and exit planning for owners of founder-owned businesses, with a network of 500+ buyers that includes sponsor platforms and strategic consolidators. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells.
Sources
Every source below was accessed in November 2026.
- WM, fourth quarter and full year 2025 earnings release, January 28, 2026
- WM, WM Completes Acquisition of Stericycle, November 4, 2024
- Republic Services, fourth quarter and full year 2025 results, February 17, 2026
- Republic Services, Form 10-K for fiscal 2025
- Waste Connections, fourth quarter 2025 results, February 11, 2026
- Waste Connections, Form 10-K for fiscal 2025
- Casella Waste Systems, fourth quarter and fiscal 2025 results
- Concentric Equity Partners and Summer Street Capital, exit of Frontier Waste Solutions, April 1, 2026
- Waste Dive, GFL buys Frontier Waste Solutions, April 2026
- Waste Dive, GFL sets Nov. 9 deadline for take-private offers, October 29, 2026
- Waste Dive, GFL sells environmental services division to Apollo and BC Partners, 2025
- Waste360, Waste Pro 24 acquisitions in 2025, October 2025
- Waste Dive, Waste Pro 2024 acquisitions, January 2025
- Kinderhook Industries, $1.0 billion Ecowaste Solutions continuation vehicle, January 16, 2026
- Waste Dive (via Yahoo Finance), Newly formed Ecowaste Solutions looks to double size in 3 years, February 5, 2026
- Waste360, Ecowaste acquires Gardner Disposal and Baker Trash Service, January 2026
- Warren Equity Partners, Meridian Waste portfolio page
- Meridian Waste, acquisition of Evergreen Environmental Partners and ADSI, September 2024
- Waste Dive, Apex Waste Solutions and Kinderhook, 2024
- Waste360, TXP Environmental acquires Diamond Back Landfill, January 27, 2026
- Macquarie Asset Management, investment in Coastal Waste and Recycling, June 13, 2023
- Business Wire, Littlejohn welcomes Ares as investor in Interstate Waste Services, October 2023
- Waste Dive, Wheelabrator and Tunnel Hill become WIN Waste Innovations, 2021
- Waste Dive, 2025 notable waste and recycling acquisitions
- Capstone Partners, Waste and Recycling M&A Update, August 25, 2025
- Cherry Bekaert, Trash to Treasure: Why PE Is Rolling Up Waste Management Companies, July 2, 2026
- Samuele Barrili, Waste Advantage Magazine, M&A in Waste, July 15, 2026
- Private Equity Info, Six years and counting, September 7, 2026
- eCFR, 40 CFR Part 258, Criteria for Municipal Solid Waste Landfills
About the author
Christoph Totter is the founder of CT Acquisitions, an M&A advisory firm that helps owners of founder-owned businesses make the most of their exit through confidential sales, recapitalizations and exit planning, with a network of 500+ buyers. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells.
Owners weighing an offer from a platform in this tracker can book a confidential call or read how we run a waste hauling business sale.
