
Due Diligence Checklist for an Asset Purchase Agreement in 2026: 8 Categories Buyers Will Review
An asset purchase agreement checklist for sellers is the buyer’s due diligence request list mapped to the agreement: asset titles and UCC liens, contract consents, the Form 8594 allocation, state bulk-sale tax clearances, WARN notice and a Phase I report.
Key takeaways
- Buyer and seller generally both file IRS Form 8594 for the year of sale, splitting the price into 7 asset classes with goodwill (Class VII) as the residual (Form 8594 instructions).
- An allocation agreed in writing binds both parties unless the IRS finds it inappropriate (IRC Section 1060(a)).
- Bulk-sale tax notices run 10 business days before closing in New Jersey (Form C-9600) and Illinois (Form CBS-1) and 10 days in New York (20 NYCRR 537.2); California buyers who skip withholding owe up to the price (R&TC 6812).
- WARN Act notice is the seller’s duty through the sale’s effective date and the buyer’s after it, for employers with 100 or more full-time employees (29 U.S.C. 2101).
- A Phase I report must be under one year old at closing, with its interviews, lien search and site visit within 180 days (40 CFR 312.20).
What is on an asset purchase agreement checklist?
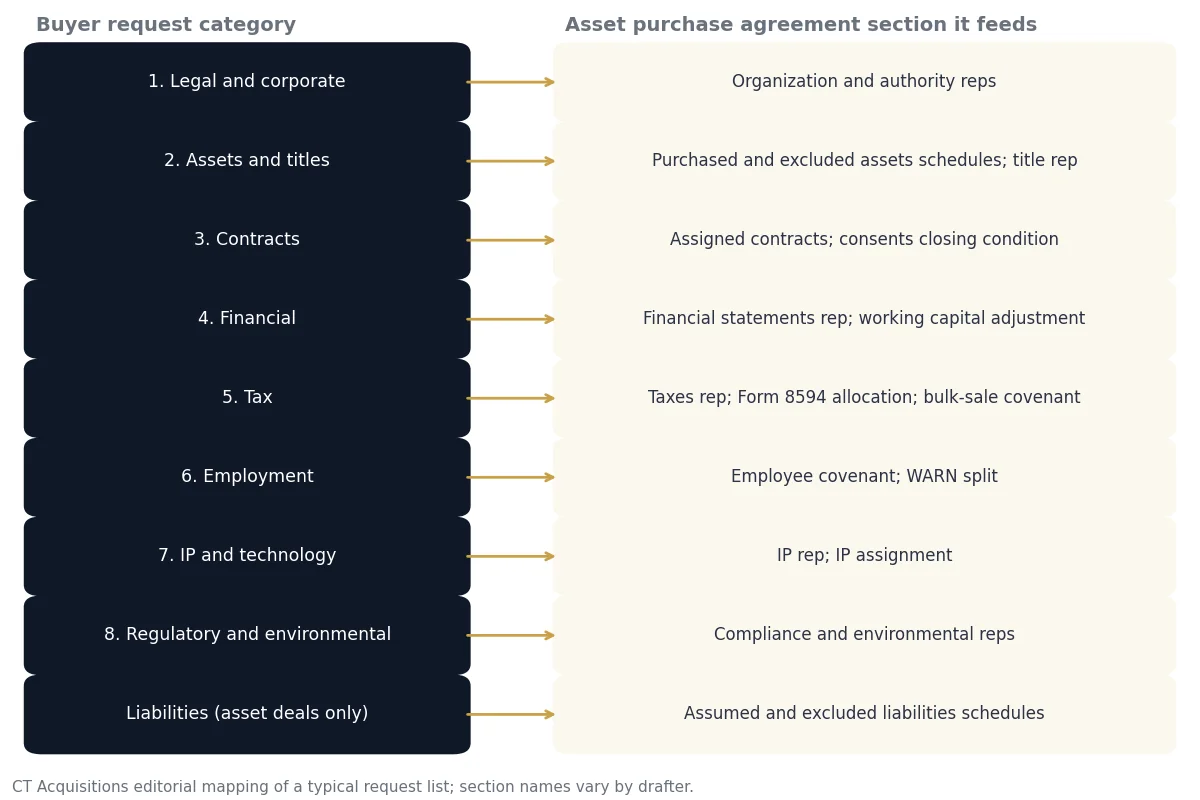
An asset purchase agreement checklist covers the 8 diligence categories a buyer requests, and each answer lands in a specific part of the agreement: a representation, a schedule of purchased or excluded assets, a closing condition or the purchase price allocation. A seller who prepares the schedule behind each request before the LOI controls how that disclosure is worded.
The mapping below is CT Acquisitions’ editorial summary of a typical request list; section names vary by drafter.
| Request category | What the buyer asks for | APA section it feeds | Seller document to prepare |
|---|---|---|---|
| 1. Legal and corporate | Formation documents, minute book (3 to 5 years), litigation | Organization and authority reps | Good standing certificate, consent approving the sale |
| 2. Assets and titles | Fixed asset register, titles, deeds, UCC lien search | Purchased and excluded assets schedules; title rep | UCC search, payoff letters, UCC-3 terminations |
| 3. Contracts | Top 20 customer, supplier, lease and license agreements | Assigned contracts; consents closing condition | Consent tracker by counterparty |
| 4. Financial | 3 to 5 years of statements, A/R and A/P aging, QoE | Financial statements rep; working capital adjustment | Reconciled monthlies, sell-side QoE |
| 5. Tax | Returns, sales tax by state, payroll filings (941s, 940s) | Taxes rep; Form 8594 allocation; bulk-sale covenant | Tax clearance requests, draft allocation |
| 6. Employment | Roster, agreements, benefit plans, 1099 contractors | Employee covenant; WARN split | Census with tenure and pay |
| 7. IP and technology | Trademarks, domains, software licenses, customer data | IP rep; IP assignment | Registration and license list |
| 8. Regulatory and environmental | Licenses, permits, OSHA history, Phase I | Compliance and environmental reps | Permit list marked transferable or not |
| Liabilities (asset deals only) | Debt schedule, accruals, warranty obligations | Assumed and excluded liabilities schedules | List split into “buyer assumes” and “seller keeps” |
For the agreement’s structure and clause order, see our explainer on what an asset purchase agreement is. The rest of this page works through the rows where asset deals differ from stock deals.
Which assets, titles and liens will the buyer verify?
The buyer verifies that the seller holds clear title to every asset on the purchased assets schedule, usually through a UCC lien search with the secretary of state, vehicle title checks and a title report on any real property. A UCC financing statement stays effective for five years after filing, and a lender can extend it only in the last six months before lapse (UCC 9-515).
- Order a UCC search in the state where the selling entity is organized and list every secured party.
- Request payoff letters with a per diem amount and a UCC-3 termination commitment.
- Confirm every vehicle title names the selling entity, not the owner personally.
- Reconcile the fixed asset register to the depreciation schedule on the last federal return; mismatches become allocation questions on Form 8594.
- Mark assets you are keeping (cash, personal vehicles, owner real estate) for the excluded assets schedule.
Which contracts need third-party consent before closing?
In an asset purchase each contract moves to the buyer by assignment, so any agreement with an anti-assignment or change-of-control clause needs the counterparty’s written consent. Customer master agreements, real estate leases, software licenses and distribution agreements are the usual list, and the buyer will make consents for the top 20 customers or the main lease a closing condition.
A seller can shorten this step by building the consent tracker before the LOI: counterparty, clause reference, whether consent or only notice is required, and who at the counterparty signs. Read each real estate lease for what the landlord may require from the assignee, such as financial statements or a personal guaranty, and send that list to the buyer early. Our guide to how long due diligence takes for a business sale shows where consents sit in the closing timeline.
How is the purchase price allocated on Form 8594?
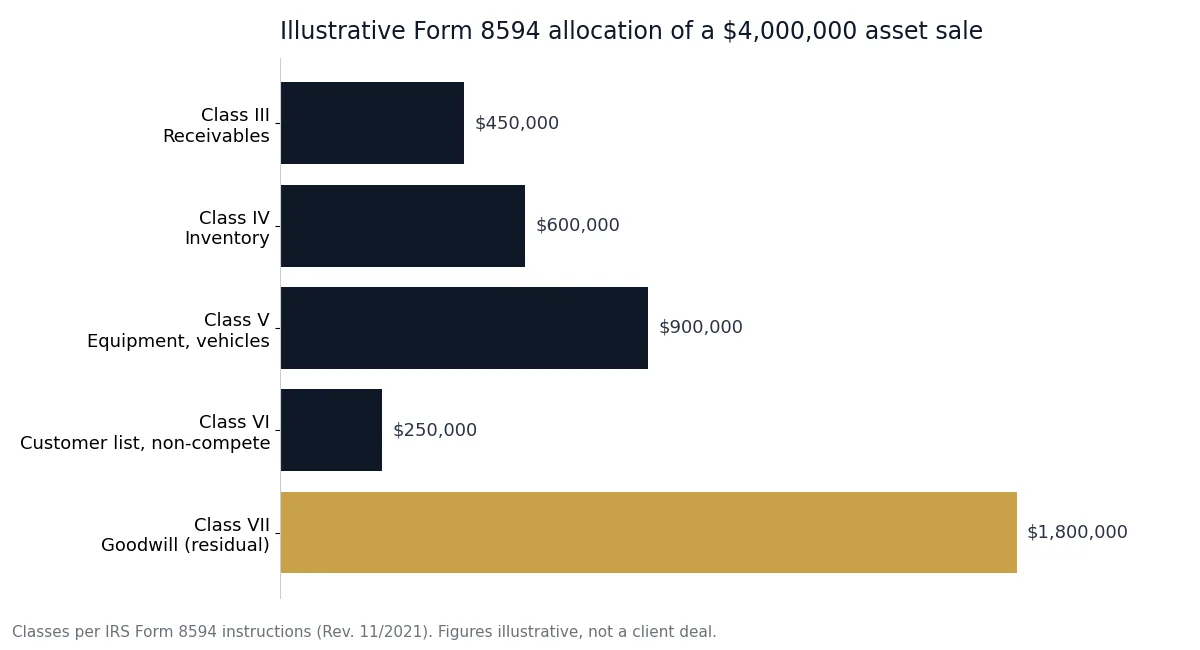
The price in an asset sale is allocated across 7 asset classes on IRS Form 8594, Asset Acquisition Statement Under Section 1060, in class order, with goodwill and going concern value (Class VII) taking whatever is left. Both buyer and seller generally attach Form 8594 to the return for the year of the sale (IRS Form 8594 instructions).
| Class | What the IRS puts in it | Illustrative allocation ($4,000,000 sale) | Source |
|---|---|---|---|
| I | Cash and general deposit accounts | None (seller keeps cash) | Form 8594 instructions |
| II | Actively traded personal property, certificates of deposit, foreign currency | None | Form 8594 instructions |
| III | Assets marked to market at least annually and debt instruments, including accounts receivable | $450,000 | Form 8594 instructions |
| IV | Inventory and property held for sale to customers | $600,000 | Form 8594 instructions |
| V | All other assets, including furniture, buildings, land, vehicles and equipment | $900,000 | Form 8594 instructions |
| VI | Section 197 intangibles other than goodwill and going concern value (customer lists, non-competes) | $250,000 | Form 8594 instructions |
| VII | Goodwill and going concern value (residual) | $1,800,000 | Form 8594 instructions |
Worked example: the residual method in four steps
Illustrative figures, not a client deal.
| Step | Calculation | Result |
|---|---|---|
| 1. Agreed purchase price | Cash at closing plus seller note | $4,000,000 |
| 2. Allocate Classes III to VI at fair market value | $450,000 + $600,000 + $900,000 + $250,000 | $2,200,000 |
| 3. Residual to Class VII goodwill | $4,000,000 minus $2,200,000 | $1,800,000 (45 percent of price) |
| 4. Later year: earnout pays $150,000 less | Decreases reduce Class VII first; both parties file a supplemental Form 8594 | Class VII $1,650,000; price $3,850,000 |
Under IRC Section 1060(a), an allocation the parties agree in writing binds both of them, so put the allocation schedule in the asset purchase agreement rather than leaving it to closing. Ask your CPA how each class is taxed to you, since the split between Class IV, Class V and Class VII changes the seller’s tax bill even when the price stays at $4,000,000. Our page on purchase price allocation in a business sale covers the negotiation.
Do bulk-sale and successor-liability rules apply to your sale?
In the five states below, the buyer must file a notice or obtain a tax clearance before closing, or it can inherit the seller’s unpaid state taxes. Expect the asset purchase agreement to hold back part of the price until the clearance arrives. California also keeps a creditor-notice bulk sale law in Commercial Code Division 6.
| State | Rule and statute | Who files | Deadline | If missed | Source |
|---|---|---|---|---|---|
| California (creditors) | Bulk sale notice, Com. Code 6105; applies to inventory sellers with assets of $10,000 to $5,000,000 (Com. Code 6103) | Notice recorded, published and sent to the county tax collector | At least 12 business days before the sale | Sale exposed to creditor claims | Cal. Com. Code 6105, 6103 |
| California (sales tax) | Successor withholding, R&TC 6811 and 6812 | Buyer requests a CDTFA certificate | CDTFA answers within 60 days of the latest of request, sale or records access | Buyer personally liable up to the purchase price; 3 years to enforce | CDTFA, R&TC 6812 |
| New York | Tax Law 1141(c); Form AU-196.10 | Buyer | At least 10 days before paying or taking possession | Buyer can be assessed the seller’s unpaid sales tax | 20 NYCRR 537.2 |
| New Jersey | N.J.S.A. 54:50-38; Form C-9600 with the contract | Buyer or buyer’s attorney | At least 10 business days before closing; Division answers within 10 business days | Buyer responsible for the seller’s state tax | NJ Division of Taxation |
| Illinois | 35 ILCS 120/5j and 35 ILCS 5/902(d); Form CBS-1 | Buyer (seller may also file) | At least 10 business days before the sale | Buyer personally liable up to the value of the property | IDOR CBS-1 instructions |
| Pennsylvania | Bulk sale clearance for transfers of more than 51 percent of assets; Form REV-181 | Seller applies; buyer must obtain the certificate | Before the transfer completes | Buyer can become liable for the seller’s Pennsylvania taxes | PA Department of Revenue |
Sellers in these states control the clock more than buyers do: Illinois issues a bulk sales release only after all taxes, penalties and interest are paid (IDOR). File any missing sales tax or payroll returns before the LOI, and ask counsel for a fixed escrow released on receipt of the certificate.
Which employee and WARN Act items does the buyer request?
The buyer requests the employee census, written employment, non-compete and contractor agreements, benefit plans and 5 years of workers’ compensation and EEOC claims. In an asset purchase the buyer rehires the seller’s staff, so the agreement must say who gives WARN Act notice and who pays accrued vacation.
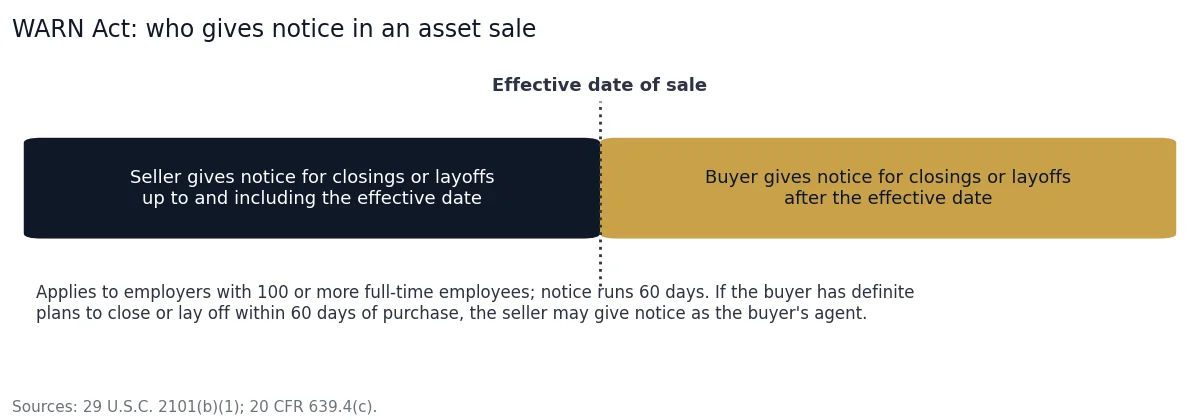
The WARN Act applies to employers with 100 or more employees excluding part-time workers, and a plant closing means 50 or more employees losing jobs at one site within 30 days (29 U.S.C. 2101). In a sale, the seller is responsible for notice up to and including the effective date; after that the buyer is. If the buyer has definite plans to close or lay off within 60 days of purchase, the seller may give notice as the buyer’s agent (20 CFR 639.4(c)).
- Roster with title, tenure and pay; I-9 files and E-Verify status.
- Contractor list with a W-2 vs 1099 classification analysis.
- Benefit plans (health, 401(k), pension, ESOP) and how each ends or transfers at closing.
Our page on seller disclosures required in a business sale lists what you must tell the buyer about employee claims.
Which financial and tax documents go on the request list?
Financial and tax requests run 3 to 5 years back: reviewed or audited statements, monthly statements for the current and 2 prior years, federal and state returns, and payroll filings (Forms 941 and 940). In an asset sale the buyer’s tax focus is narrower than in a stock sale, because the buyer acquires assets, not the entity, so the selling entity’s own tax attributes, including net operating losses, stay with the seller.
- Receivable and payable aging; inventory count, valuation method and obsolete reserves.
- Normalized working capital target for the closing adjustment.
- EBITDA add-backs (owner compensation, personal expenses, one-time items), ideally tested in a quality of earnings report.
- Customer concentration (top 20 as a share of revenue, 3 years) and supplier concentration (top 10 as a share of COGS).
- Sales and use tax filings by state and exempt-customer certificates.
What environmental, IP and regulatory items close the list?
If real property or a long-term lease is part of the deal, the buyer will order a Phase I Environmental Site Assessment, usually to ASTM E1527-21, which EPA accepts for the All Appropriate Inquiries rule (40 CFR 312.11). The report must be no older than one year at closing, and its interviews, lien search, records review and site visit must be within 180 days (40 CFR 312.20).
- Environmental: prior Phase I or Phase II reports, underground storage tank registrations, hazardous waste manifests, air and water permits, enforcement history.
- IP and technology: trademark registrations, domain names, software licenses and open-source use, source code ownership, customer data and CCPA practices.
- Regulatory: industry licenses (contractor, healthcare, professional), OSHA citation history (5 years), and which permits transfer to a new owner versus which the buyer must reapply for.
What should you do first in your situation?
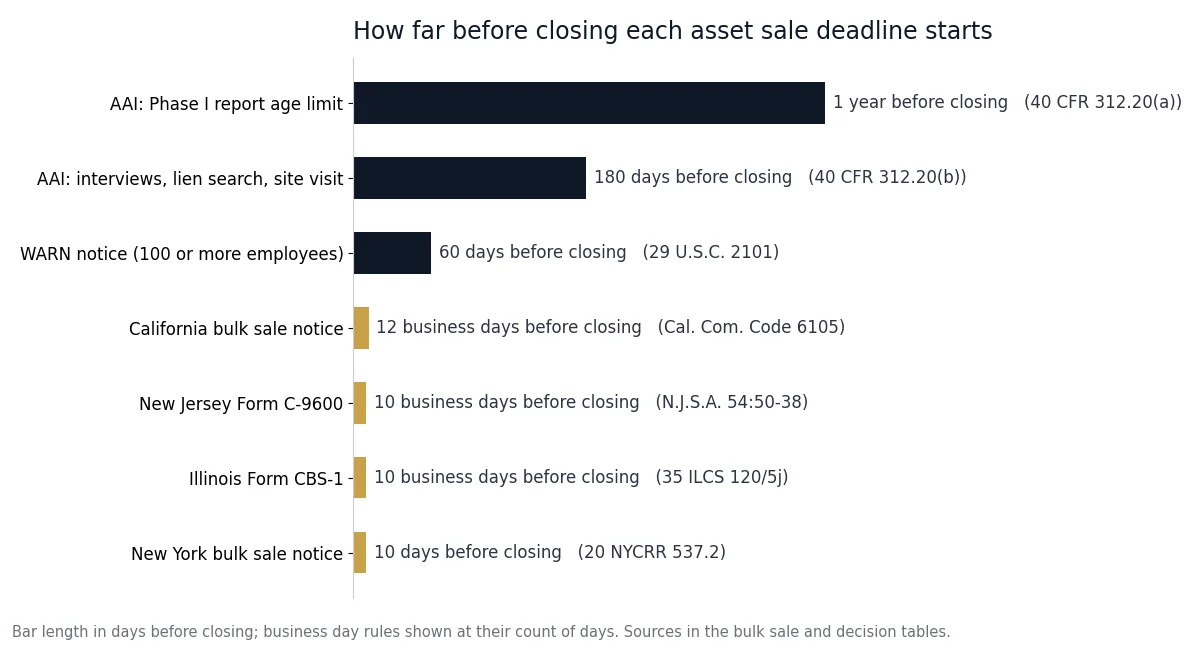
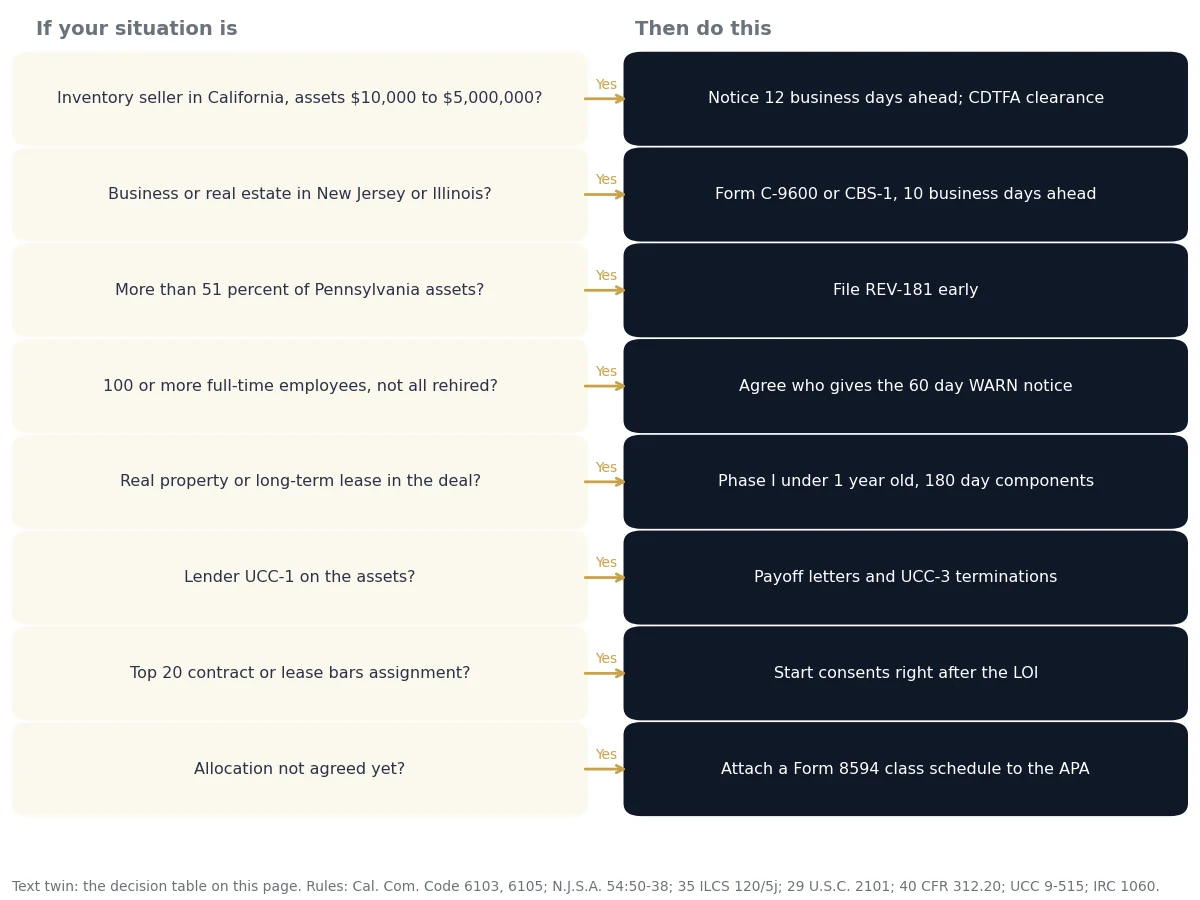
Start with the rows that carry a hard filing deadline: the California, New Jersey, Illinois and New York bulk-sale notices run 10 to 12 days before closing, and the WARN notice runs 60 days. Each row pairs a trigger from a rule cited above with the step a seller can take before the buyer’s request list arrives.
| If your situation is | Then do this | Rule |
|---|---|---|
| If you sell inventory from stock in California and the assets are worth $10,000 to $5,000,000 | Put the 12 business day notice date in the closing timeline; ask CDTFA for a tax clearance certificate | Com. Code 6103, 6105; R&TC 6812 |
| If the business or its real estate is in New Jersey or Illinois | Give the buyer what it needs to file Form C-9600 or Form CBS-1 at least 10 business days before closing | N.J.S.A. 54:50-38; 35 ILCS 120/5j |
| If you are selling more than 51 percent of Pennsylvania assets | File REV-181 early and clear any unfiled returns | PA bulk sale clearance |
| If you have 100 or more full-time employees and the buyer will not hire everyone | Agree in writing who gives WARN notice; notice runs 60 days | 29 U.S.C. 2101(b)(1); 20 CFR 639.4(c) |
| If real property or a long-term lease is in the deal | Share any prior Phase I; expect a new report under one year old, with interviews and site visit within 180 days of closing | 40 CFR 312.20 |
| If a lender has a UCC-1 on your assets | Request payoff letters and UCC-3 terminations for closing | UCC 9-515 |
| If a top 20 customer contract or your lease bars assignment | Start consent requests right after the LOI | Contract terms |
| If the allocation is not yet agreed | Attach an allocation schedule by Form 8594 class to the agreement | IRC 1060(a) |
How does CT Acquisitions help sellers prepare for an asset sale?
CT Acquisitions helps owners of founder-owned businesses make the most of their exit through a confidential sale, recapitalization or exit planning, with a 500+ buyer network. Before buyers see the business, we work through the 8 categories above with the owner and their counsel so the request list is answered from prepared schedules. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells. Owners weighing structure can start with our comparison of stock sale vs asset sale for sellers or book a confidential call.
How we compiled this
We compiled this page in November 2026 from 14 primary documents: IRS and state tax agency instructions, the statutes and regulations listed under Sources, and UCC 9-515. The allocation example is illustrative. Forum posts and competitor checklists were excluded as sources.
Frequently asked questions
What should be included in an asset purchase agreement checklist?
Eight request categories (legal and corporate, financial, tax, operational, IP and technology, regulatory, environmental, employment) plus the deal items an asset sale adds: a purchased and excluded assets schedule, an assumed liabilities schedule, third-party consents, a Form 8594 allocation schedule, UCC lien releases and any state bulk-sale tax clearance.
What is a due diligence request list?
It is the document request the buyer’s counsel sends after the LOI, usually organized by the same 8 categories as this checklist. Each answer the seller uploads to the data room later becomes a representation or a disclosure schedule entry in the asset purchase agreement, so an incomplete answer can turn into an indemnification claim after closing.
What should a seller look for in an asset purchase agreement?
Five sections decide most of the seller’s exposure: the excluded liabilities list, the purchase price allocation schedule (binding on both sides if agreed in writing under IRC Section 1060(a)), the bulk-sale escrow or holdback language, the WARN Act split at the effective date, and the indemnification cap and survival period for the representations.
Does the buyer take on the seller’s liabilities in an asset purchase?
Only the liabilities listed as assumed in the agreement, with statutory exceptions. In California a buyer that skips the CDTFA withholding becomes personally liable for the seller’s sales tax up to the purchase price under Revenue and Taxation Code Section 6812, and New Jersey and Illinois apply similar purchaser liability when the bulk-sale notice is missed.
Who files Form 8594 in an asset sale?
Generally both the buyer and the seller. Each attaches Form 8594 to its income tax return for the year that includes the sale date, using the same 7 asset classes. If the allocation changes in a later year, for example after an earnout adjustment, each party files a supplemental Form 8594 for the year of the change.
How long does asset purchase due diligence take?
The legal floors are short: 10 business days for a New Jersey or Illinois bulk-sale filing and 12 business days for a California bulk-sale notice. The slower items are lender payoff letters, landlord and customer consents, and a Phase I report whose interviews and lien search must be no older than 180 days at closing.
Sources
- IRS, Instructions for Form 8594 (Rev. 11/2021), accessed Nov 2026
- 26 U.S.C. 1060, Special allocation rules for certain asset acquisitions, accessed Nov 2026
- California Commercial Code Section 6103 and Section 6105, accessed Nov 2026
- California Revenue and Taxation Code Section 6812 (CDTFA), accessed Nov 2026
- 20 NYCRR 537.2, New York bulk sale notice, accessed Nov 2026
- New Jersey Division of Taxation, Bulk Sales FAQ, accessed Nov 2026
- Illinois Department of Revenue, Form CBS-1 instructions, accessed Nov 2026
- Pennsylvania Department of Revenue, Bulk Sales, accessed Nov 2026
- 29 U.S.C. 2101, WARN Act definitions and sale of business, accessed Nov 2026
- 20 CFR 639.4, who must give WARN notice, accessed Nov 2026
- 40 CFR 312.11 and 40 CFR 312.20, All Appropriate Inquiries, accessed Nov 2026
- UCC 9-515, duration of financing statements, accessed Nov 2026
Related resources from CT Acquisitions
- Investment manager due diligence checklist
- Buying a restaurant due diligence checklist
- Property development due diligence checklist
- Mortgage company acquisition due diligence checklist
- What is Quality of Earnings (QoE)?
- What happens during due diligence?
- Asset sale vs stock sale
- Equity rollover for founders
- Private equity in HVAC 2026
About the Author
Christoph Totter is the founder of CT Acquisitions, an M&A advisory firm that works for business owners on the sell side headquartered in Sheridan, Wyoming. We run sell-side M&A processes for founder-owned U.S. businesses ($1M-$25M EBITDA). We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells. Connect on LinkedIn · Get in touch
Selling your business in an asset sale?
CT Acquisitions helps owners of founder-owned businesses with a confidential sale, recapitalization or exit plan, with a 500+ buyer network. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells.
