
Insurance Agency and Broker M&A Multiples Report 2026: Valuation Benchmarks by Size and Segment
Insurance agency M&A multiples averaged 11.4x EBITDA in 2025 for deals with $1 million or more of EBITDA (SICA Fletcher), while smaller agencies still trade near 1x to 1.5x commission revenue, part of it paid as earnout.
Key takeaways
- Insurance brokerage deals with at least $1 million of EBITDA averaged about 11.4x EBITDA in 2025, after 11.9x in 2024 and 9.4x in 2020 (SICA Fletcher via Leader’s Edge, April 8, 2026).
- MarshBerry put the average upfront price at 11.22x EBITDA in 2024, with realistic earnouts adding 1.44x and platform firms at 14.02x (Insurance Insider US, reporting MarshBerry).
- Gallagher paid $13.45 billion for AssuredPartners, 14.3x pro forma EBITDAC or 11.3x net of tax benefits and synergies, and closed on August 18, 2025 (Gallagher SEC filing).
- OPTIS Partners counted 144 agency deals in Q3 2026, down 27% from 197 a year earlier; private equity-backed and hybrid buyers made 76% of them (Insurance Journal, October 22, 2026).
- Three trackers counted 2025 three ways: OPTIS Partners 695 deals, SICA Fletcher 714, MarshBerry 854 (MarshBerry 2025 Year in Review).
What are insurance agency M&A multiples in 2026?
Insurance agency M&A multiples sit between 11x and 12x EBITDA for agencies with $1 million or more of EBITDA: 11.9x in 2024 and about 11.4x in 2025 by SICA Fletcher’s count, and 11.22x upfront in 2024 by MarshBerry’s. Below that size, buyers still quote commission revenue, often 1x to 1.5x. Platform firms and megadeals price at 14x to 15x.
Each published number measures a different set of deals, which is why owners hear everything from 1x revenue to 16x EBITDA. The table lines up each benchmark with the deals behind it. Read the “Deals measured” column before applying any of them to your agency.
| Source | Deals measured | Multiple | Basis | Date |
|---|---|---|---|---|
| Higginbotham | Rough estimate for any agency | 1x to 1.5x | Earned commission | Accessed Nov 2026 |
| Agency Brokerage Consultants | Books of business; capital-backed buyers | 1x to 4x revenue; 7.5x to 12x or more | Commission revenue; pro forma EBITDA | Undated, accessed Nov 2026 |
| Insurance Journal (Schoeffler and Oak) | Internal and local buyers; PE buyers | 6x to 7x; 8x to 10x | EBITA | Aug 21, 2017 |
| SICA Fletcher rule of thumb | Agencies it observed | 8x to 12x | EBITDA | Apr 24, 2025 |
| MarshBerry via Insurance Insider US | All firms, upfront base price | 11.22x (2024); 10.83x (2023) | EBITDA | 2024 data |
| MarshBerry via Insurance Insider US | Realistic earnout on top of upfront | 1.44x | EBITDA | 2024 data |
| SICA Fletcher | Deals with $1.0M or more of EBITDA | 9.4x (2020); 11.9x (2024); 11.8x (H1 2025) | EBITDA | Data to Jun 30, 2025 |
| SICA Fletcher via Leader’s Edge | Deals with $1M or more of EBITDA | About 11.4x (2025) | EBITDA | Apr 8, 2026 |
| MarshBerry via Insurance Insider US | Platform firms | 14.02x | EBITDA | 2024 data |
| MarshBerry via PIA West | All firms, price at maximum earnout | 13.78x (2022); 14.85x (2023) | EBITDA | May 7, 2024 |
| Capstone Partners | Insurance distribution deals with disclosed multiples | 13.1x (2019 to 2021); 16.7x (2022 to mid 2025) | EV/EBITDA | Jun 30, 2025 |
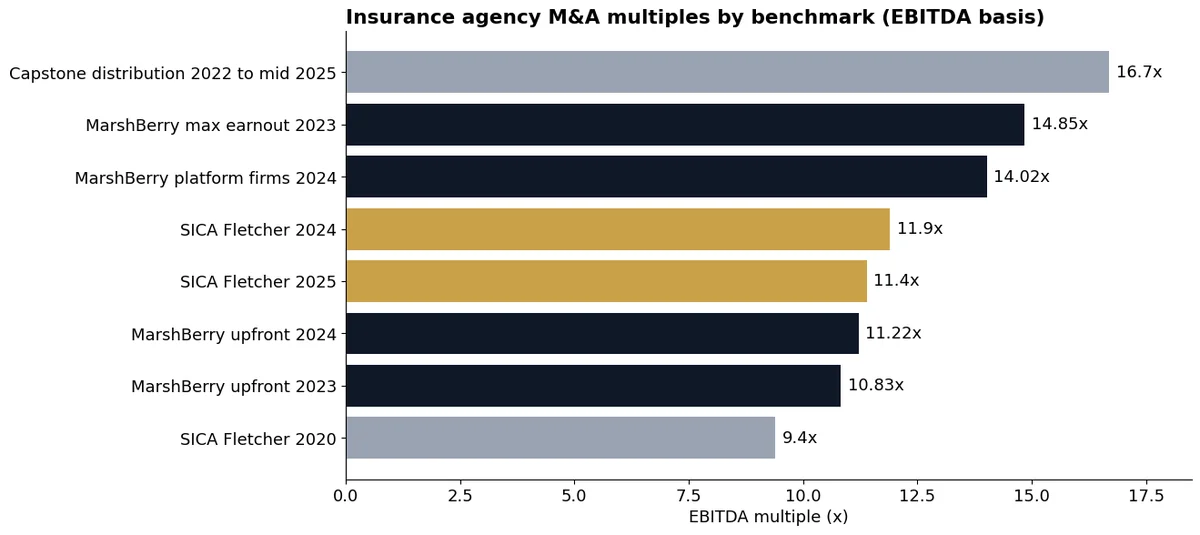
Two gaps matter. SICA Fletcher’s 11.4x covers only agencies above $1 million of EBITDA, so it does not describe a $400,000 EBITDA agency. Capstone Partners’ 16.7x is an average of deals with disclosed multiples, which skews toward large platform transactions; small agency prices are rarely published.
How do insurance agency multiples change with size?
Size moves the multiple more than any other published variable. A book folded into a buyer’s office prices on commissions (1x to 1.5x per Higginbotham); local buyers in 2017 offered 6x to 7x EBITA; an agency with $1 million or more of EBITDA averaged about 11.4x in 2025; platform firms averaged 14.02x in 2024 (MarshBerry).
| Agency profile | Typical buyer | Published multiple | Source and date |
|---|---|---|---|
| Book of business folded into a buyer’s office | Local agency, internal perpetuation | 1x to 1.5x earned commission | Higginbotham, accessed Nov 2026 |
| Small agency, owner-run | Internal and local buyers | 6x to 7x EBITA; 1.2x to 1.7x revenue | Insurance Journal, Aug 2017 |
| Small agency, owner-run | Private equity buyers | 8x to 10x EBITA; 2x to 3x revenue | Insurance Journal, Aug 2017 |
| $1M or more of EBITDA | PE-backed and public acquirers | About 11.4x (2025); 11.9x (2024) | SICA Fletcher, Apr 2026 |
| All firms MarshBerry tracked | Mixed | 11.22x upfront plus 1.44x realistic earnout (2024) | MarshBerry via Insurance Insider US |
| Platform firms | PE sponsors, public brokers | 14.02x (2024) | MarshBerry via Insurance Insider US |
| National platforms ($1.3B to $2.9B revenue) | Public brokers | 14.3x to 16.4x before tax benefits and synergies | Gallagher SEC filing; MarshBerry 2025 |
The 2017 small-agency split is old, and no newer public source splits sub-$1 million EBITDA deals by buyer type. Treat it as the floor of a negotiation, not a market average. If your normalized EBITDA is under $1 million, the next section shows how to read a commission revenue offer in EBITDA terms.
Commission revenue multiple or EBITDA multiple: how do they compare?
The two meet through margin: an EBITDA multiple equals the revenue multiple divided by the EBITDA margin. Best Practices agencies posted a 26.1% margin in the 2025 Big I and Reagan Consulting study, while MarshBerry puts the industry average at 15% to 20%. The same 1.5x revenue offer is 5.7x EBITDA for the first and 10.0x for a 15% margin agency.
| EBITDA margin | 1.0x revenue | 1.5x revenue | 2.0x revenue | 3.0x revenue | Margin source |
|---|---|---|---|---|---|
| 15% | 6.7x | 10.0x | 13.3x | 20.0x | MarshBerry industry average, low end |
| 20% | 5.0x | 7.5x | 10.0x | 15.0x | MarshBerry industry average, high end |
| 26.1% | 3.8x | 5.7x | 7.7x | 11.5x | Big I and Reagan 2025 Best Practices |
| 30.7% | 3.3x | 4.9x | 6.5x | 9.8x | Big I and Reagan 2026 update, top of range |
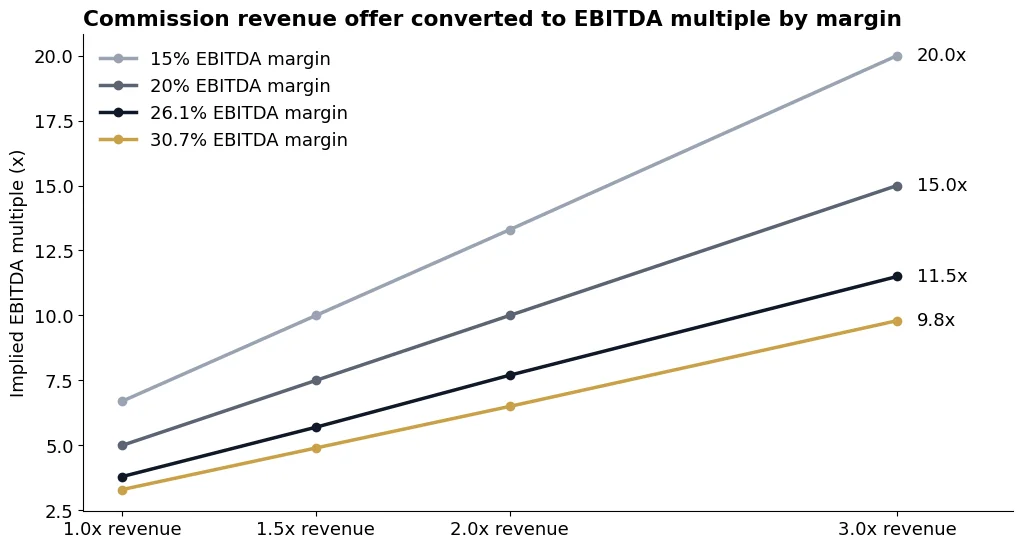
The rule that follows: if your margin is above 25%, ask every bidder to price normalized EBITDA, because a commission multiple undervalues profit you already earn. If your margin is under 20%, a commission offer from a local buyer can beat an EBITDA offer. The insurance agency valuation guide walks through normalizing owner pay and contingents before you compare.
What did the largest insurance broker deals price at?
The largest disclosed insurance broker deals of 2023 to 2025 priced at about 12x to 16.4x EBITDA and 4.6x to 6.0x revenue. Gallagher paid 14.3x for AssuredPartners, 11.3x after a $1.0 billion tax asset and synergies. Brown & Brown paid about 16.4x for Accession before synergies, 12x after (MarshBerry). These are national platforms, not small-agency comparables.
| Deal | Dates | Price or valuation | Disclosed multiple | Implied revenue multiple | Source |
|---|---|---|---|---|---|
| Gallagher buys AssuredPartners | Announced Dec 9, 2024; closed Aug 18, 2025 | $13.45 billion | 14.3x pro forma EBITDAC; 11.3x net | 4.6x ($2.9 billion revenue) | SEC Exhibit 99.1; closing release |
| Brown & Brown buys Accession (Risk Strategies, One80 Intermediaries) | Announced Jun 10, 2025 | $9.825 billion | About 16.4x; about 12x with synergies | 5.8x ($1.7 billion revenue) | Brown & Brown release via Benzinga; MarshBerry |
| Marsh McLennan buys McGriff | Announced Sep 29, 2024 | $7.75 billion cash | Not disclosed | 6.0x ($1.3 billion revenue) | Marsh McLennan release |
| Aon buys NFP | Announced Dec 20, 2023; closed April 2024 | $13.4 billion | About 15x seller-adjusted EBITDA | Not disclosed | Aon release |
| Truist Insurance Holdings sold to Stone Point and CD&R | Completed May 7, 2024 | $15.5 billion implied EV | Not disclosed | Not disclosed | Stone Point release |
| Hub International minority equity raise | May 12, 2025 | $29 billion EV ($1.6 billion raised) | Not disclosed | 6.0x ($4.8 billion 2024 revenue) | Hub release |
| Acrisure convertible preferred raise | May 21, 2025 | $32 billion valuation ($2.1 billion raised) | Not disclosed | Not disclosed | Insurance Journal |
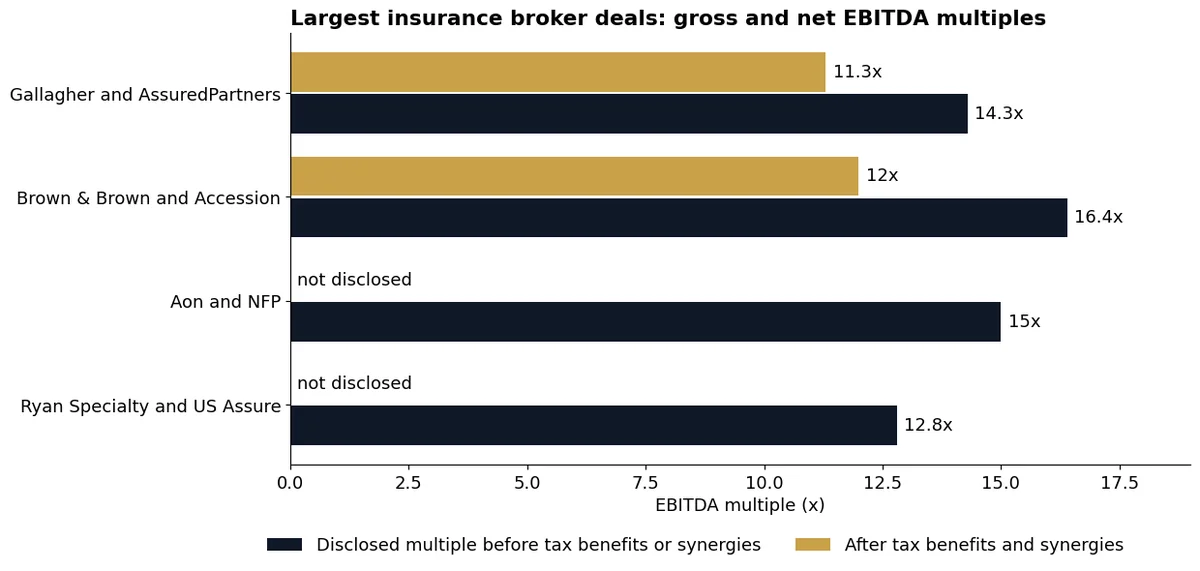
Two prints often get misdated in summaries. Aon announced NFP on December 20, 2023, not in April 2023, and the disclosed multiple was about 15x. Acrisure’s $32 billion valuation came from a $2.1 billion primary raise in May 2025 in which no existing investor sold, so it is not a secondary sale price.
The gross-to-net gap is the lesson for a small seller. Gallagher’s headline fell 3.0 turns, from 14.3x to 11.3x, once the tax asset and synergies were counted. Ask any buyer which EBITDA its multiple applies to: yours as reported, yours normalized, or a pro forma number that includes the buyer’s own savings.
How many insurance agency deals are closing?
Fewer than in 2025. OPTIS Partners counted 292 agency deals in the first half of 2026, down 15% from 342, and 144 in Q3 2026 against 197 a year earlier. MarshBerry counted 854 U.S. brokerage deals in 2025, up 0.8% from 847. The trackers disagree on totals because they count different universes.
| Tracker | What it counts | 2024 | 2025 | 2026 to date | Source |
|---|---|---|---|---|---|
| OPTIS Partners | Announced agency deals, U.S. and Canada | Not stated (2025 was down 12%) | 695 | Q1 148; Q2 138; Q3 144 | IJ Apr 2026; IJ Oct 2026 |
| SICA Fletcher | Insurance brokerage transactions | Not stated | 714 | Not published | Leader’s Edge, Apr 2026 |
| MarshBerry | Announced U.S. insurance brokerage transactions | 847 | 854 | 52 specialty deals in H1 | 2025 Year in Review; Aug 2026 update |
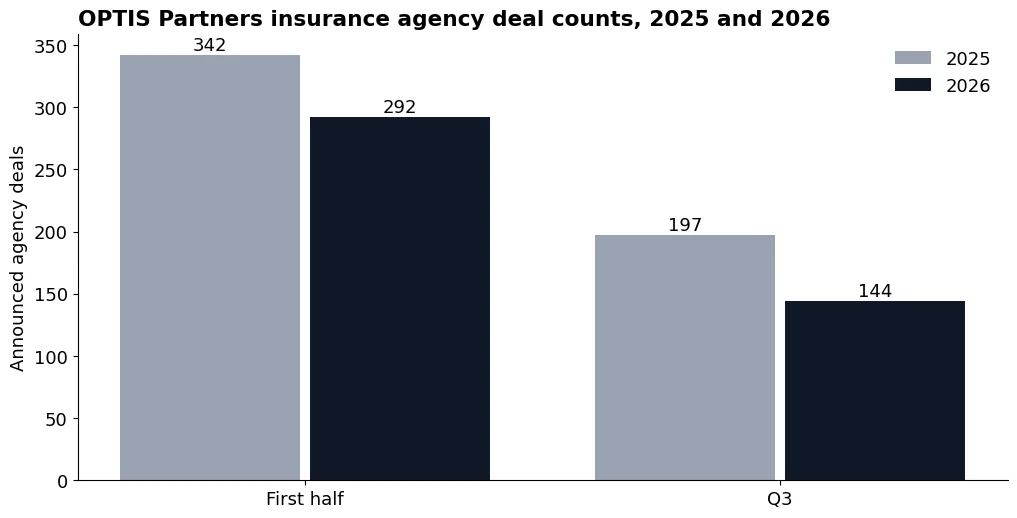
| OPTIS Partners period | 2025 | 2026 | Change | Source |
|---|---|---|---|---|
| First half | 342 | 292 | Down 15% | Insurance Business, Jul 22, 2026 |
| Q3 | 197 | 144 | Down 27% | Insurance Journal, Oct 22, 2026 |
| PE-backed and hybrid share | Not stated | 72% (Q1); 80% (Q2); 76% (Q3) | n/a | Insurance Journal; Insurance Business |
The buyers are concentrated. MarshBerry’s top three buyers in 2025 were BroadStreet Partners (65 deals), Inszone Insurance Services (44) and ALKEME (42), and the top 10 made 362 of the 854 deals, or 42.4%. Through Q3 2026 OPTIS lists BroadStreet Partners at 57 deals, Inszone at 48 and Hub International at 22. The map of who buys insurance agencies profiles each of them.
What moves an insurance agency multiple up or down?
Four factors have published, sourced effects: size of EBITDA, margin, how growth was earned and whether an advisor ran the sale. SICA Fletcher found that advisor-run deals averaged about 25% higher multiples since 2020, and OPTIS Partners said in October 2026 that rate-driven growth now earns lower multiples and larger earnouts.
| Factor | Direction | Published effect | Source |
|---|---|---|---|
| EBITDA of $1 million or more | Up | Enters the 11.4x (2025) average band | SICA Fletcher via Leader’s Edge |
| EBITDA margin above 25% | Up on EBITDA pricing | 26.1% Best Practices margin turns 1.5x revenue into 5.7x EBITDA | Big I and Reagan 2025; CT arithmetic |
| Growth mainly from carrier rate increases | Down | Lower multiples and larger earnouts | OPTIS Partners, Oct 2026 |
| Producer-led organic growth, benefits book, specialty niche | Holds | Valuations “should continue to hold steady” | OPTIS Partners, Oct 2026 |
| Sale run by an M&A advisor | Up | About 25% higher average multiple since 2020 | SICA Fletcher, 2025 |
| Large contingent commissions | Neutral after smoothing | Buyers use a 3-year rolling average | Adastra Equity |
Retention, carrier concentration and producer age also move price, but none of the sources reviewed here publishes a sourced turn value for them. The old version of this page gave turn values for those drivers without a source; they are removed until a dataset supports them.
What EBITDA multiple do wholesale brokers and MGAs get?
No public dataset reports a wholesale-only average multiple. The closest disclosed prints are Accession, which includes the One80 Intermediaries wholesale platform, at about 12x EBITDA with synergies and 16.4x without; Ryan Specialty’s US Assure at about 12.8x trailing EBITDA; and Howden Re’s 15x to 16x for diversified specialty MGA platforms.
| Deal or benchmark | Business type | Price | Multiple | Source |
|---|---|---|---|---|
| Brown & Brown buys Accession | Retail specialty plus wholesale and program manager | $9.825 billion | About 12x with synergies; about 16.4x without | MarshBerry 2025 Year in Review |
| Ryan Specialty buys US Assure | Program administrator (MGA) | $1.075 billion plus up to $400 million earnout | About 12.8x trailing EBITDA | Ryan Specialty Q2 2024 call |
| Ryan Specialty buys Velocity Risk Underwriters | Property MGA | $525 million | 6.5x revenue ($81 million) | Reinsurance News |
| Howden Re benchmark | Diversified specialty MGA platforms | n/a | 15x to 16x; monoline one to two turns lower | Howden Re, May 8, 2026 |
| MarshBerry deal count | U.S. specialty distribution | n/a | 149 deals in 2025 (17.4% of 854) | MarshBerry 2025 Year in Review |
MGA pricing depends on the carrier capacity agreement and profit commission, which a retail agency does not have. The specialty insurance MGA buyers and multiples guide covers 15 named MGA transactions and the capacity terms that move them.
How much of an insurance agency price is paid at closing?
Most of it, but not all. MarshBerry’s 2024 data put the upfront price at 11.22x EBITDA and the realistic earnout at 1.44x, so about 11% of a typical total arrived after closing. At maximum earnout in 2023 the headline reached 14.85x against 10.83x upfront: 27% of the headline was contingent.
| Scenario (illustrative, $1.2 million EBITDA) | Multiple | Value | Basis |
|---|---|---|---|
| Local buyer, midpoint of 2017 range | 6.5x | $7,800,000 | Insurance Journal, 2017 |
| Upfront at MarshBerry 2024 average | 11.22x | $13,464,000 | MarshBerry via Insurance Insider US |
| Realistic earnout on top | 1.44x | $1,728,000 | MarshBerry via Insurance Insider US |
| Upfront plus realistic earnout | 12.66x | $15,192,000 | CT arithmetic |
| SICA Fletcher 2025 average, $1M+ EBITDA | 11.4x | $13,680,000 | SICA Fletcher via Leader’s Edge |
| Headline at MarshBerry 2023 maximum earnout | 14.85x | $17,820,000 | MarshBerry via PIA West |
The gap between $13,464,000 at closing and a $17,820,000 headline is the earnout. Ask for the upfront multiple in writing, the retention or growth hurdle behind each earnout dollar, and the measurement period. The earnout benchmarks by deal size and the rollover equity benchmarks show how other sectors split the same consideration.
Producer non-competes remain a state-law question. A federal court in Texas set aside the FTC Non-Compete Clause Rule on August 20, 2024, and the FTC voted 3-1 on September 5, 2025 to drop its appeal in Ryan, LLC v. FTC. Buyers still require non-solicits from selling principals and producers; check enforceability in your state before you sign.
Which multiple applies to your agency?
Use the row that matches your agency. Each threshold comes from a source on this page; the action is what to ask a buyer before you accept a number. A buyer quoting a multiple without naming the EBITDA it applies to has not made a comparable offer yet.
| If your situation is | Then | Why |
|---|---|---|
| If normalized EBITDA is under $1 million | Expect commission revenue or local buyer pricing; convert each offer with the margin table | SICA Fletcher’s 11.4x covers only $1M+ EBITDA deals |
| If normalized EBITDA is $1 million or more | Benchmark the upfront multiple against 11.22x (2024) and the total against 11.4x (2025) | MarshBerry and SICA Fletcher averages |
| If your EBITDA margin is above 25% | Ask bidders to price EBITDA, not commission revenue | 1.5x revenue is only 5.7x EBITDA at a 26.1% margin |
| If recent growth came mostly from rate increases | Expect a lower multiple or a larger earnout; document producer-led new business | OPTIS Partners, Oct 2026 |
| If an offer quotes a headline including earnout | Ask for the upfront multiple and the hurdle for each earnout dollar | 27% of the 2023 maximum-earnout headline was contingent |
| If you run a wholesale or MGA business | Price against MGA and specialty prints, not retail agency averages | Howden Re 15x to 16x; US Assure 12.8x |
| If you sell without an advisor | Expect a lower average multiple | SICA Fletcher: about 25% higher with an advisor since 2020 |
Thinking about selling your insurance agency?
CT Acquisitions helps owners of founder-owned agencies run a confidential sale or recapitalization with a 500+ buyer network. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells.
Book a Confidential CallHow we compiled this
CT Acquisitions compiled this page in November 2026 from 31 documents: company press releases and SEC filings for 8 named transactions, the FTC release on the non-compete rule, MarshBerry, OPTIS Partners and SICA Fletcher publications, two Big I and Reagan Consulting studies, Capstone Partners and Howden Re. We did not survey owners or use forum posts, and we excluded multiples that carried no named source or date.
Frequently asked questions
What is a good EBITDA multiple for an insurance agency?
For an agency with $1 million or more of EBITDA, 11.4x was the 2025 average (SICA Fletcher, April 2026), and MarshBerry put the average upfront price at 11.22x in 2024. Smaller agencies sell lower: Insurance Journal reported local buyers paying 6x to 7x EBITA in 2017. A multiple above 12x usually includes an earnout or platform scale.
What is a good EBITDA margin for an insurance agency?
Best Practices agencies reported a 26.1% EBITDA margin in the 2025 Big I and Reagan Consulting study, and 23.2% to 30.7% across revenue bands in the August 2026 update. MarshBerry puts the industry average at 15% to 20%. Margin matters because it converts a commission revenue offer into the EBITDA multiple a buyer is really paying.
What does a 10x EBITDA multiple mean?
A 10x EBITDA multiple means the price equals ten years of normalized annual EBITDA: an agency earning $800,000 of EBITDA sells for $8 million. At the 26.1% margin from the 2025 Best Practices study, 10x EBITDA equals about 2.6x commission revenue. Ask whether the 10x is paid at closing or includes an earnout.
What EBITDA multiple do wholesale insurance brokers sell for?
No public dataset reports a wholesale-only average. The closest disclosed prints: Brown & Brown paid about 12x EBITDA including synergies (about 16.4x without) for Accession, which includes the One80 wholesale platform (MarshBerry, 2025); Ryan Specialty paid about 12.8x trailing EBITDA for US Assure; Howden Re puts diversified specialty MGA platforms at 15x to 16x.
How many insurance agency deals happened in 2025?
The count changes with the source. OPTIS Partners counted 695 agency deals in the U.S. and Canada in 2025, SICA Fletcher counted 714 brokerage transactions, and MarshBerry counted 854 U.S. insurance brokerage transactions. The gap of 159 deals between OPTIS and MarshBerry comes from what each firm includes, so compare quarters within one source only.
Are insurance agency M&A multiples falling in 2026?
Deal volume is falling: OPTIS Partners counted 144 deals in Q3 2026 against 197 in Q3 2025, down 27%. OPTIS expects agencies that grew mainly through rate increases to see lower multiples and larger earnouts, while benefits books, specialty niches and producer-led growth hold steady. None of the sources here had published a full 2026 average by November 2026.
Sources
- SICA Fletcher, 2025 valuations, interest rates, spreads and deal volume (data to June 30, 2025). Accessed November 2026.
- Leader’s Edge, Insurance Brokerage M&A 2026 (SICA Fletcher), April 8, 2026. Accessed November 2026.
- SICA Fletcher, insurance agency valuation rule of thumb, April 24, 2025. Accessed November 2026.
- Insurance Insider US, MarshBerry 2024 agency valuations. Accessed November 2026.
- PIA West, MarshBerry M&A valuations, May 7, 2024. Accessed November 2026.
- MarshBerry, 2025 M&A Year in Review: buyers, sellers and transactions. Accessed November 2026.
- MarshBerry, Q2 2026 specialty intermediary market update, August 3, 2026. Accessed November 2026.
- Insurance Journal, OPTIS Partners Q1 2026, April 27, 2026. Accessed November 2026.
- Insurance Journal, OPTIS Partners H1 2026, July 22, 2026. Accessed November 2026.
- Insurance Business, OPTIS Partners H1 2026, July 22, 2026. Accessed November 2026.
- Insurance Journal, OPTIS Partners Q3 2026, October 22, 2026. Accessed November 2026.
- Capstone Partners, Insurance Services Market Update, June 30, 2025. Accessed November 2026.
- Big I and Reagan Consulting, 2025 Best Practices Study, August 12, 2025. Accessed November 2026.
- Big I and Reagan Consulting, 2026 Best Practices Study update, August 12, 2026. Accessed November 2026.
- MarshBerry, How to think about value, April 6, 2022. Accessed November 2026.
- Insurance Journal, Schoeffler and Oak on agency valuation, August 21, 2017. Accessed November 2026.
- Higginbotham, insurance agency valuation. Accessed November 2026.
- Agency Brokerage Consultants, insurance agency valuation multiples. Accessed November 2026.
- Arthur J. Gallagher & Co., SEC Exhibit 99.1, December 9, 2024. Accessed November 2026.
- Gallagher closing release for AssuredPartners, August 18, 2025. Accessed November 2026.
- Brown & Brown agreement to acquire Accession, June 10, 2025 (Benzinga). Accessed November 2026.
- Marsh McLennan, agreement to acquire McGriff, September 29, 2024. Accessed November 2026.
- Aon, agreement to acquire NFP, December 20, 2023. Accessed November 2026.
- Stone Point Capital, Truist Insurance Holdings sale completed, May 7, 2024. Accessed November 2026.
- Hub International, minority investment at $29 billion, May 12, 2025. Accessed November 2026.
- Insurance Journal, Acrisure $2.1 billion raise, May 21, 2025. Accessed November 2026.
- Ryan Specialty, Q2 2024 earnings call transcript, August 1, 2024. Accessed November 2026.
- Reinsurance News, Ryan Specialty completes Velocity acquisition, February 4, 2025. Accessed November 2026.
- Howden Re, Filtered for quality, May 8, 2026. Accessed November 2026.
- Federal Trade Commission, accede to vacatur of the Non-Compete Clause Rule, September 5, 2025. Accessed November 2026.
- Adastra Equity, insurance agency EBITDA multiples. Accessed November 2026.
Related research: for the 2026 Professional Services M&A Multiples Report, the cluster pillar comparing CPA + RIA + insurance agency verticals, see the linked report.
Related research: for the 2026 RIA and Wealth Management M&A Multiples Report, sibling professional services spoke with AUM-band lens, see the linked report.
Related research: for the 2026 CPA and Accounting Firm M&A Multiples Report, sibling professional services spoke with Rosenberg revenue-multiple + adj EBITDA lens, see the linked report.
