
RIA Valuation Multiples: Free RIA Valuation Calculator. What’s Your Wealth Management Firm Worth in 2026?
RIA valuation multiples in 2026: the median RIA sale priced at 11.6x adjusted EBITDA in 2025 (Advisor Growth Strategies, 60 deals), small wealth managers price nearer 5.4x (Sica | Fletcher), and closing cash runs lower.
Key takeaways
- The median RIA sale in 2025 priced at 11.6x EBITDA, up over 40% since 2020 (Advisor Growth Strategies, March 2026).
- Sica | Fletcher’s 2024 index prices wealth managers at 5.4x to 7.5x EBITDA, or 1.1% to 2.3% of AUM (Sica | Fletcher).
- DeVoe & Company counted a record 322 RIA deals in 2025, with an average seller just above $1 billion of AUM (InvestmentNews, January 2026).
- Buyer equity averaged 29% of 2025 deal value, so headline price and closing cash differ (AGS RIA Deal Room).
- IRS Table III forces a 4.95% IRA withdrawal at age 80 and 8.20% at 90, AUM a buyer models as leaving (IRS Publication 590-B).
Thinking about selling your RIA?
A 15-minute confidential call gives you a valuation range and the RIA aggregators likely to compete for your firm. The call is free, with no obligation.
How does the free RIA valuation calculator work?
Enter AUM, blended fee and EBITDA margin: the calculator multiplies AUM by fee for revenue, revenue by margin for EBITDA, and EBITDA by a multiple from the tiers below. The result is a screening range, not a quality of earnings review, so check it against the worked example before quoting it to a buyer.
What are RIA valuation multiples in 2026?
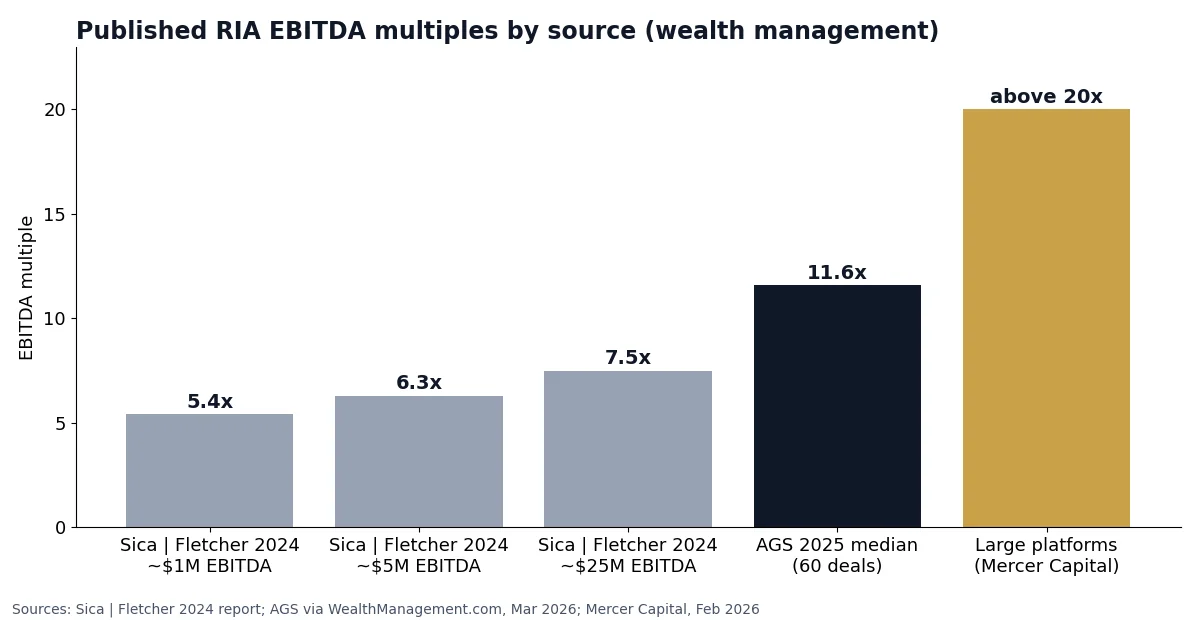
RIA valuation multiples cluster in three bands. Advisor Growth Strategies (AGS) reports an 11.6x median adjusted EBITDA for 2025 deals with an average seller near $500 million of AUM. Sica | Fletcher’s 2024 index puts wealth managers at 5.4x to 7.5x EBITDA. Mercer Capital says large platforms often trade north of 20x. Which band applies depends on size, growth and what the quote counts.
| Key number | Value | Source and date |
|---|---|---|
| Median RIA EBITDA multiple, 2025 | 11.6x (60 deals) | AGS 2026 Deal Room Report, March 2026 |
| Equity share of deal value | 29% in 2025, 33% expected in 2026 | AGS, March 2026 |
| Wealth manager EBITDA multiple | 5.4x (~$1M EBITDA) to 7.5x (~$25M) | Sica | Fletcher, 2024 |
| Wealth manager revenue multiple | 2.8x (~$3M revenue) to 4.0x (~$50M) | Sica | Fletcher, 2024 |
| Wealth manager price as % of AUM | 1.1% (~$100M) to 2.3% (~$5B) | Sica | Fletcher, 2024 |
| Large platform deals | North of 20x EBITDA | Mercer Capital, February 2026 |
The CT Acquisitions estimate (illustrative, not a published statistic): 5x to 8x EBITDA for founder-led firms under $500M AUM, 8x to 11x from $500M to $1B with a second-generation (G2) advisor bench, and 10x to 15x above $1B with 6%+ organic growth.
Why do published RIA deal counts and multiples disagree?
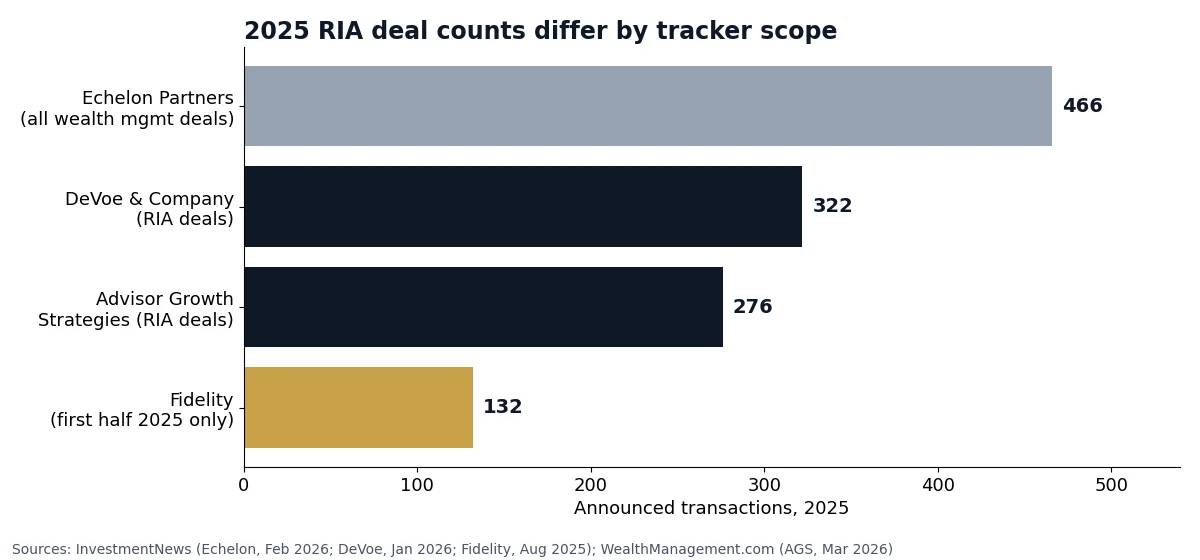
The four trackers count different things. Echelon Partners counts every announced wealth management deal, DeVoe & Company counts RIA transactions only, AGS prices a 60-deal sample, and Fidelity reports half-years. A 2025 count can read 276, 322 or 466 for the same market, and a multiple quoted on headline value runs higher than one measured on cash at close.
| Tracker | Latest count | What it measures | Source |
|---|---|---|---|
| Echelon Partners | 466 deals in 2025, up 27.3% | Announced wealth management transactions | InvestmentNews, Feb 13, 2026 |
| DeVoe & Company | 322 deals in 2025 vs 272 in 2024; sellers under $500M fell to 38% of deals from 46% | RIA transactions; average seller just above $1B AUM | InvestmentNews, Jan 21, 2026 |
| Advisor Growth Strategies | 276 RIA deals, $796.4B purchased assets; multiple from 60 deals | Deal count plus a priced sample | WealthManagement.com, Mar 25, 2026 |
| Fidelity | 132 deals in H1 2025; median deal $517M AUM; 86% PE-backed | Half-year RIA transactions | InvestmentNews, Aug 19, 2025 |
One correction: guides often cite Cerulli as saying 38% of advisors are over 55 and hold 42% of assets. The Cerulli U.S. Advisor Metrics 2023 figure is that 38% of advisors, holding 42% of assets, expect to retire within 10 years.
How do buyers value an RIA: EBITDA, revenue or percent of AUM?
Buyers price an RIA on normalized EBITDA and use revenue and percent of AUM only as checks. EBITDA is the only method that sees margin: Sica | Fletcher’s 1.6% of AUM benchmark equals 8.5x EBITDA for a firm charging 0.75% at a 25% margin but 3.6x for a firm charging 1.00% at a 45% margin.
- Reconcile AUM to Form ADV. Buyers read Item 5.F(2) of SEC Form ADV Part 1A and client types from Item 5.D.
- Split revenue. Separate recurring AUM fees from planning fees and commissions.
- Normalize EBITDA. Replace the founder’s pay with a market salary ($250K to $400K for a senior advisor) and add back personal and one-time costs.
- Apply the EBITDA multiple for your size and growth band, then cross-check with 2.8x to 4.0x revenue and 1.1% to 2.3% of AUM.
- Price the structure in cash equivalents before comparing offers.
| Blended fee | 25% EBITDA margin | 35% margin | 45% margin |
|---|---|---|---|
| 0.75% of AUM | 8.5x EBITDA | 6.1x | 4.7x |
| 1.00% of AUM | 6.4x EBITDA | 4.6x | 3.6x |
Which factors move an RIA valuation multiple up or down?
Growth, concentration, succession and client age move the multiple most. David DeVoe of DeVoe & Company says each extra point of sustained growth lifts firm value about 7%. RIA Catalyst’s example adjustments take 1x to 3x off when founder succession is unresolved and 1x to 2x off when the top 10 clients exceed 30% of revenue.
| Driver | Threshold | Effect on price | Source |
|---|---|---|---|
| Organic growth | Each +1 point a year, sustained | About +7% firm value | David DeVoe, May 2023 |
| Top 10 client concentration | Above 25% flagged; above 30% | -1x to -2x EBITDA | RIA Catalyst example |
| Founder succession | No G2 advisor on top relationships | -1x to -3x EBITDA | RIA Catalyst example |
| EBITDA margin | Above 45%; below 25% | Add-backs questioned; -1x to -2x | RIA Catalyst example |
| Client retention | Below the 97% median | Tighter retention earn-out | Schwab 2025 RIA Benchmarking Study |
| Recurring AUM fees | Below 85% of revenue | Non-recurring streams priced lower | CT Acquisitions estimate (illustrative) |
How does client age change an RIA’s value?
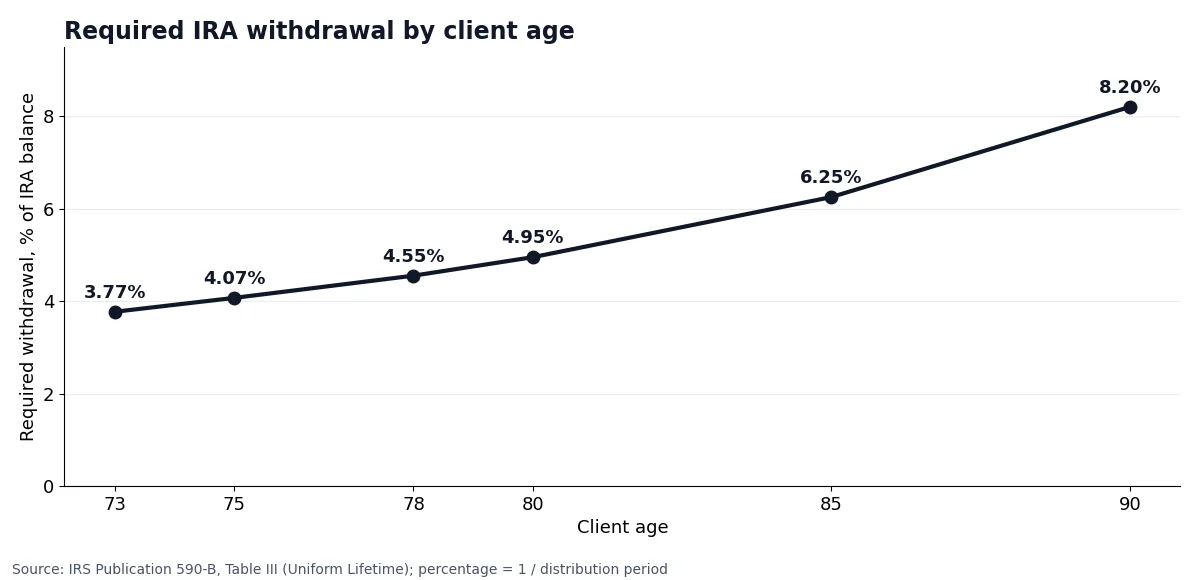
Older clients shrink AUM on a schedule the IRS sets. Required minimum distributions start at 73, and the Uniform Lifetime Table in IRS Publication 590-B divides an IRA balance by 26.5 at 73 and 20.2 at 80, a 4.95% forced withdrawal at 80. A buyer modeling a book with 30% of AUM in IRAs of 80-year-olds sees 1.49% of firm AUM required out each year (illustrative).
| Client age | IRS distribution period | Required withdrawal (% of IRA balance) |
|---|---|---|
| 73 | 26.5 | 3.77% |
| 75 | 24.6 | 4.07% |
| 78 | 22.0 | 4.55% |
| 80 | 20.2 | 4.95% |
| 85 | 16.0 | 6.25% |
| 90 | 12.2 | 8.20% |
A withdrawal is not a lost client if the cash stays in a taxable account at your firm, so report three years of RMD cash retained in house.
How much does AUM concentration cost?
Concentration is priced through the earn-out as much as the multiple. Above 25% of revenue in the top 10 households, RIA Catalyst flags the book, and CT Acquisitions estimates (illustrative) that buyers shift value into retention payments. List the top 25 households by revenue, age and lead adviser before the buyer does.
What is a $250M AUM RIA worth? A worked example
The illustrative firm below has $250M of AUM, $2.55M of revenue at a 102 bps blended fee, and $1.5M of reported EBITDA. After normalization it earns $1.43M, a 56% margin that sits above the 45% level where RIA Catalyst says buyers question add-backs. Five benchmarks price it from $2.75M to $16.59M, so the EBITDA inputs decide the outcome.
| Normalization step (illustrative) | Amount |
|---|---|
| Reported EBITDA | $1.50M |
| Founder pay reset from $200K to $325K market rate | -$125K |
| Add back personal expenses | +$35K |
| Add back one-time legal (ADV update) | +$20K |
| Normalized EBITDA | $1.43M |
| Method | Benchmark applied | Implied value |
|---|---|---|
| Percent of AUM | 1.1% to 1.6% (Sica | Fletcher) | $2.75M to $4.0M |
| Revenue multiple | 2.8x (Sica | Fletcher, small) | $7.14M |
| EBITDA, index | 5.4x (Sica | Fletcher, small) | $7.72M |
| EBITDA, CT Acquisitions estimate | 7.1x (adjustments below) | $10.15M |
| EBITDA, 2025 median | 11.6x (AGS; average seller near $500M AUM) | $16.59M |
The 7.1x starts at 7.0x, adds 1.0x for 88% recurring fees, 96.5% retention, Schwab custody and a California metro, and subtracts 0.9x for founder-held relationships, 28% top-10 concentration and 4.5% organic growth. Moving the top 10 relationships to the G2 adviser over 18 months lifts it to about 8.2x, or $11.7M.
How much of an RIA price arrives at closing?
Less than the headline. AGS found equity in the buyer averaged 29% of 2025 deal value, and the CT Acquisitions illustrative structure for the firm above is 65% cash ($6.6M), 20% rollover ($2.0M) and 15% earn-out ($1.5M). Every retention earn-out also depends on client consent, because Advisers Act section 205(a)(2) bars assignment of an advisory contract without it.
A change of control is an assignment under section 202(a)(1), and section 205(a)(2) requires client consent to it. Ask each bidder how it collects consents and whether a non-consenting client counts against your retention target.
| Input (illustrative) | Offer A: 7.1x, 65/20/15 | Offer B: 6.8x, 85% cash, 15% rollover |
|---|---|---|
| Headline value | $10.15M | $9.72M |
| Cash at close | $6.6M | $8.27M |
| Rollover after 30% haircut | $2.0M becomes $1.4M | $1.46M becomes $1.02M |
| Earn-out at 70% odds | $1.5M becomes $1.05M | None |
| Comparable value | $9.05M | $9.29M |
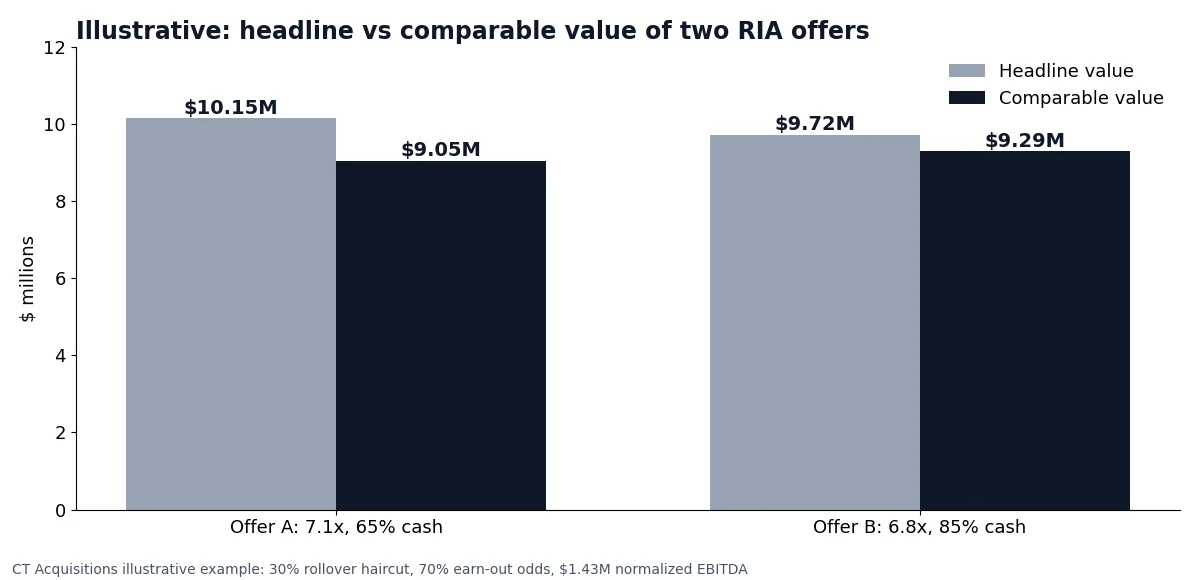
Comparable value is cash at close plus discounted rollover plus earn-out times your odds. Set the haircut after asking for the unit issue price and the debt above your equity, then halve the earn-out odds as a stress test. Our guide to rollover equity in a business sale lists the questions.
Want to know what your RIA is worth?
A 15-minute confidential call gives you a number based on what RIA aggregators pay now. The call is free, with no obligation.
Which valuation path fits your firm?
Match your firm to the first row that fits, from a state-registered practice under the $100 million SEC registration line to a firm weighing two aggregator offers. Firms that clear every threshold can go to market on the EBITDA method, using the CT Acquisitions estimate bands as a starting range.
| If your situation is | Then |
|---|---|
| Under $100M of regulatory AUM (state registered) | Expect successor advisers or a larger RIA as buyers; check the RIA valuation calculator against the 2.8x small-firm revenue multiple. |
| Recurring AUM fees below 85% of revenue | Value the fee book and the planning or commission streams separately before you quote a multiple. |
| Top 10 households above 25% of revenue | Expect a larger retention earn-out; add households before going to market. |
| Founder holds the top 20 relationships, no G2 adviser | Plan 24 to 36 months to transfer relationships, or accept a 1x to 3x discount. See how to prepare an RIA for exit. |
| More than 30% of AUM in IRAs of clients 80 and older | Report three years of RMD cash retained in house so the buyer does not model it as outflow. |
Our map of who buys RIAs in 2026 lists the active aggregators. The sale process is in how to sell an RIA, and the confidential route is on sell your wealth management firm.
How CT Acquisitions Works
- We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells.
- Confidential outreach to a 500+ buyer network, only with your approval.
- Exit options side by side: confidential sale, recapitalization or exit plan.
How we compiled this
We compiled this page in November 2026 from 15 documents: four deal trackers (AGS, DeVoe & Company, Echelon Partners, Fidelity) as reported by InvestmentNews and WealthManagement.com, Sica | Fletcher, Mercer Capital, Schwab, Cerulli, SEC Form ADV, two Advisers Act sections, RIA Catalyst and IRS Publication 590-B. We ran no survey and excluded forum threads; CT Acquisitions estimates are labeled illustrative.
Frequently asked questions
What multiples are RIAs selling for?
The median RIA sale in 2025 priced at 11.6x adjusted EBITDA across 60 deals tracked by Advisor Growth Strategies. Sica | Fletcher’s 2024 index puts wealth managers at 5.4x EBITDA near $1M of EBITDA and 7.5x near $25M, and Mercer Capital says large platforms can exceed 20x.
How are RIA firms valued?
Buyers normalize EBITDA by resetting the founder’s pay to a market salary and adding back one-time costs, then apply an EBITDA multiple. They cross-check with revenue (2.8x to 4.0x for wealth managers, Sica | Fletcher 2024) and percent of AUM (1.1% to 2.3%), but EBITDA carries the price because it sees margin.
Is a percentage of AUM a good way to value a wealth management firm?
Only as a screen. A price of 1.6% of AUM equals 8.5x EBITDA for a firm charging 0.75% at a 25% margin, but 3.6x for a firm charging 1.00% at a 45% margin. Percent-of-AUM pricing overpays for thin margins and underpays for strong ones.
Do RIA aggregators pay all cash?
Rarely. Equity in the buyer averaged 29% of RIA deal value in 2025, and buyers expect 33% in 2026, per Advisor Growth Strategies. CT Acquisitions estimates (illustrative) that aggregator offers pay 60% to 75% in cash at close, with the rest in rollover equity and a retention earn-out.
What is my RIA worth at $1B AUM?
Illustrative arithmetic: $1B of AUM at a 100 bps blended fee is $10M of revenue, and a 40% margin gives $4M of EBITDA. At Sica | Fletcher’s 6.3x mid-size multiple that is $25.2M; at the 11.6x 2025 median from Advisor Growth Strategies it is $46.4M.
Does selling an RIA need client consent?
Yes. Section 205(a)(2) of the Investment Advisers Act bars assignment of an advisory contract without the client’s consent, and section 202(a)(1) treats a transfer of a controlling block of voting securities as an assignment. A sale of control runs through consents, and retention earn-outs measure who stays.
Sources
All sources accessed November 2026.
- AGS Deal Room coverage, WealthManagement.com, Mar 25, 2026.
- Advisor Growth Strategies, RIA Deal Room.
- Sica | Fletcher, RIA Valuation Multiples: 2024 Report.
- Mercer Capital, Internal vs. External Valuations for RIAs, Feb 13, 2026.
- DeVoe & Company 2025 coverage, InvestmentNews, Jan 21, 2026.
- Echelon Partners 2025 coverage, InvestmentNews, Feb 13, 2026.
- Fidelity H1 2025 review, InvestmentNews, Aug 19, 2025.
- Schwab 2025 RIA Benchmarking Study, InvestmentNews, Jul 18, 2025.
- Cerulli U.S. Advisor Metrics 2023, InvestmentNews, Jan 16, 2024.
- David DeVoe on growth and value, WealthManagement.com, May 11, 2023.
- RIA Catalyst, How RIAs Are Valued in 2026.
- SEC, Form ADV Part 1A, Items 5.D and 5.F.
- 15 U.S.C. 80b-5 (Advisers Act section 205) and 15 U.S.C. 80b-2 (section 202).
- IRS Publication 590-B, Table III Uniform Lifetime.
General valuation information, not legal, tax or transaction advice.
About the Author
Christoph Totter is the founder of CT Acquisitions, an M&A advisory firm headquartered in Sheridan, Wyoming, that helps owners of founder-owned businesses make the most of their exit through a confidential sale, a recapitalization or exit planning. We work directly with a network of 500+ buyers, including search funders, family offices, lower middle-market PE, RIA aggregators and strategic consolidators. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells. Connect on LinkedIn · Get in touch
Want a Specific Read on Your RIA?
15 minutes, confidential, no contract, no cost. You leave with a read on your aggregator buyer pool and a likely valuation range.
