
IT Services M&A and VAR Multiples Report 2026: Valuation Benchmarks by Size and Services Mix
IT services M&A priced at a median 10.4x EV/EBITDA across 520 disclosed deals from 2015 to mid 2026, per Aventis Advisors: value-added resellers cleared a lower 7.9x because resale gross profit is thin.
Key takeaways
- Disclosed IT services control deals priced at a median 10.4x EV/EBITDA (n=520, quartiles 6.9x to 15.9x) and 1.1x revenue from January 2015 to June 2026 (Aventis Advisors, July 31, 2026).
- Value-added resellers sit at the bottom of the subsector table: 7.9x EV/EBITDA across 91 deals and 0.5x revenue across 177 deals, against 10.2x for systems integrators and 16.0x for data and analytics firms (Aventis Advisors).
- Financial buyers made 47.2% of IT services acquisitions from January to September 2026, up from 17.9% in 2015, and paid a median 11.3x against 9.8x for strategic buyers (Aventis Advisors, Nov 5, 2026).
- Computacenter agreed to pay up to $92M for US federal reseller GAI on $8M of 2025 adjusted EBITDA: $63M upfront (7.9x) and up to $29M contingent (Computacenter RNS, May 28, 2026).
- H.I.G. Capital took Converge Technology Solutions private at about 7.4x trailing adjusted EBITDA and a C$1.3 billion enterprise value (Converge, Feb 7, 2025), still the largest disclosed solutions provider multiple of the cycle.
What are IT services M&A multiples in 2026?
IT services M&A multiples average a median 10.4x EV/EBITDA and 1.1x EV/Revenue across 1,069 control deals from January 2015 to June 2026, per Aventis Advisors. The 2025 median was 9.5x, down from 12.2x in 2024. Subsector decides the band: value-added resellers sit at 7.9x, managed service providers at 9.9x, systems integrators at 10.2x and data and analytics firms at 16.0x.
Read the deal count before the median: cloud services rests on 10 disclosed EBITDA multiples, value-added resellers on 91.
| Subsector | Deals (EBITDA) | Lower quartile | Median EV/EBITDA | Upper quartile | Median EV/Revenue | Source |
|---|---|---|---|---|---|---|
| Data and analytics | 17 | 7.9x | 16.0x | 25.5x | 1.9x | Aventis Advisors |
| Cybersecurity services | 24 | 7.5x | 13.4x | 24.5x | 1.9x | Aventis Advisors |
| Digital engineering | 27 | 9.0x | 12.3x | 16.6x | 1.4x | Aventis Advisors |
| Software development | 72 | 8.2x | 11.4x | 18.4x | 1.2x | Aventis Advisors |
| Systems integration | 102 | 6.7x | 10.2x | 14.7x | 1.1x | Aventis Advisors |
| Managed service providers | 79 | 6.1x | 9.9x | 13.6x | 1.1x | Aventis Advisors |
| IT consulting | 30 | 6.8x | 9.0x | 11.9x | 1.1x | Aventis Advisors |
| Cloud services | 10 | 6.8x | 8.0x | 10.3x | 1.3x | Aventis Advisors |
| Value-added resellers | 91 | 5.4x | 7.9x | 11.7x | 0.5x | Aventis Advisors |
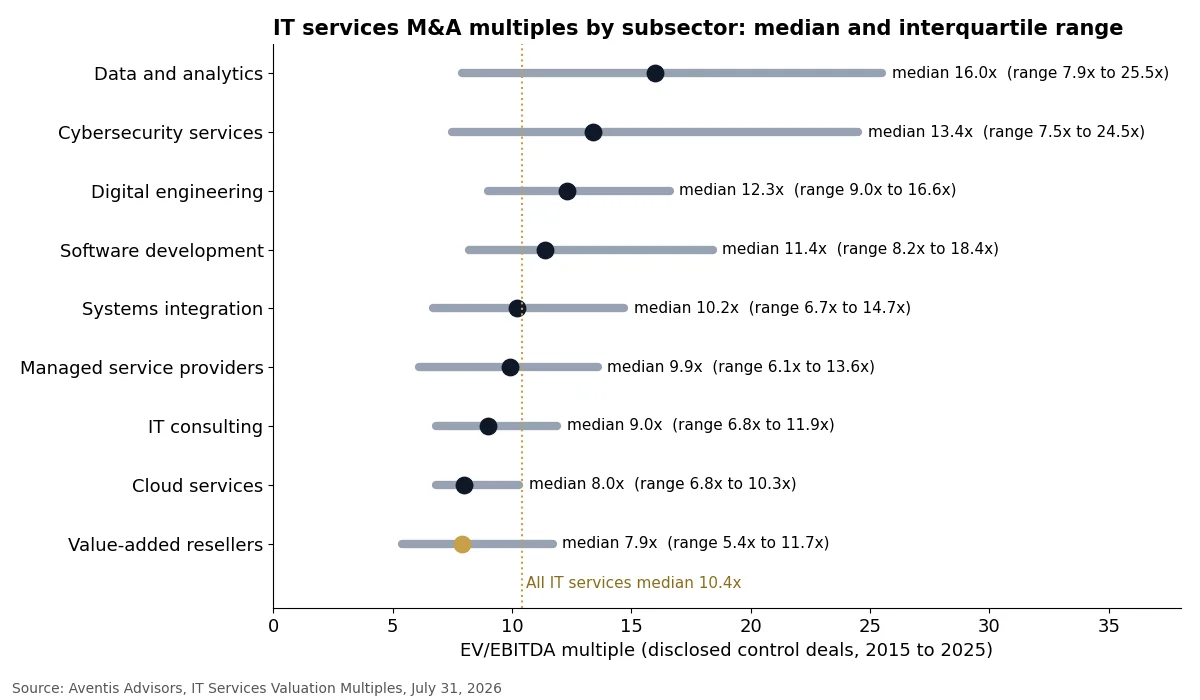
The top and bottom rows sit 8.1 turns apart. Aventis Advisors ties the premiums to proprietary data, recurring revenue and scarce talent. Disclosed deals skew large: the median reseller deal in the set was $42M, so a small reseller should test itself against the lower quartile first. Our sibling MSP M&A multiples report covers the managed services row in depth.
How does deal size change an IT services multiple?
Size adds roughly six turns from the smallest to the largest IT services deals. Aventis Advisors puts deals under $5M at a median 6.7x EV/EBITDA, $5M to $20M deals at 7.9x, $20M to $50M at 10.0x and deals above $500M at 12.7x. The step from $5M to $50M of deal value is where a reseller or integrator moves from local buyers to sponsor platforms.
| Deal size (enterprise value) | Deals | Median EV/Revenue | Median EV/EBITDA | Source |
|---|---|---|---|---|
| Under $5M | 173 | 0.6x | 6.7x | Aventis Advisors |
| $5M to $20M | 349 | 1.0x | 7.9x | Aventis Advisors |
| $20M to $50M | 165 | 1.3x | 10.0x | Aventis Advisors |
| $50M to $100M | 125 | 1.1x | 11.7x | Aventis Advisors |
| $100M to $500M | 169 | 1.3x | 11.3x | Aventis Advisors |
| $500M and above | 85 | 1.6x | 12.7x | Aventis Advisors |
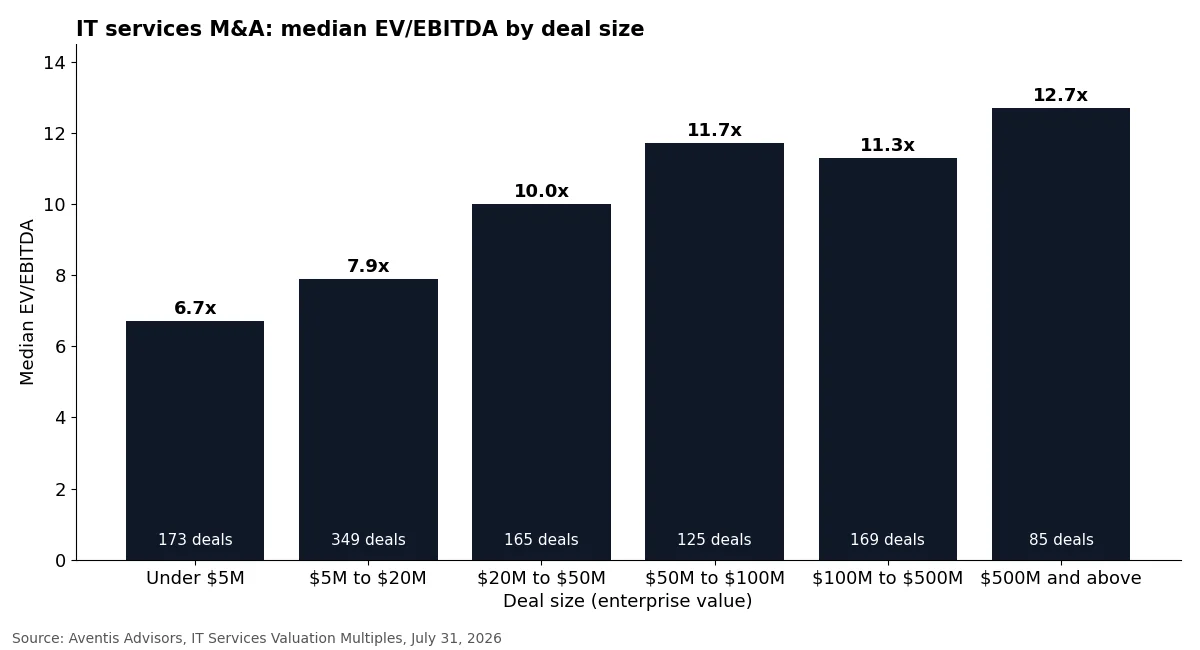
The bands describe deal value, not company revenue, and the top bands mix in subsector: seven of the 27 disclosed digital engineering deals were $1 billion or larger. North American deals priced at a median 10.9x on a median deal size of $73M, per Aventis Advisors.
Is IT services M&A activity rising or falling?
IT services M&A volume is holding near its post-2022 level while the buyer mix shifts to private equity. Aventis Advisors counted 1,565 deals in 2025 and 1,053 from January to September 2026, against a 2022 peak of 1,831. Financial buyers made 42.1% of 2025 deals and 47.2% in the first nine months of 2026.
| Year | IT services deals | Financial buyer share | Median EV/EBITDA | Source |
|---|---|---|---|---|
| 2015 | 875 | 17.9% | 10.3x | Aventis Advisors |
| 2016 | 927 | 19.6% | 9.8x | Aventis Advisors |
| 2017 | 1,059 | 21.8% | 9.3x | Aventis Advisors |
| 2018 | 1,214 | 24.2% | 11.2x | Aventis Advisors |
| 2019 | 1,363 | 26.3% | 9.6x | Aventis Advisors |
| 2020 | 1,233 | 35.1% | 8.5x | Aventis Advisors |
| 2021 | 1,553 | 39.3% | 12.0x | Aventis Advisors |
| 2022 | 1,831 | 34.0% | 10.3x | Aventis Advisors |
| 2023 | 1,460 | 35.6% | 12.7x | Aventis Advisors |
| 2024 | 1,634 | 39.4% | 12.2x | Aventis Advisors |
| 2025 | 1,565 | 42.1% | 9.5x | Aventis Advisors |
| Jan to Sep 2026 | 1,053 | 47.2% | Fewer than 10 disclosed | Aventis Advisors |
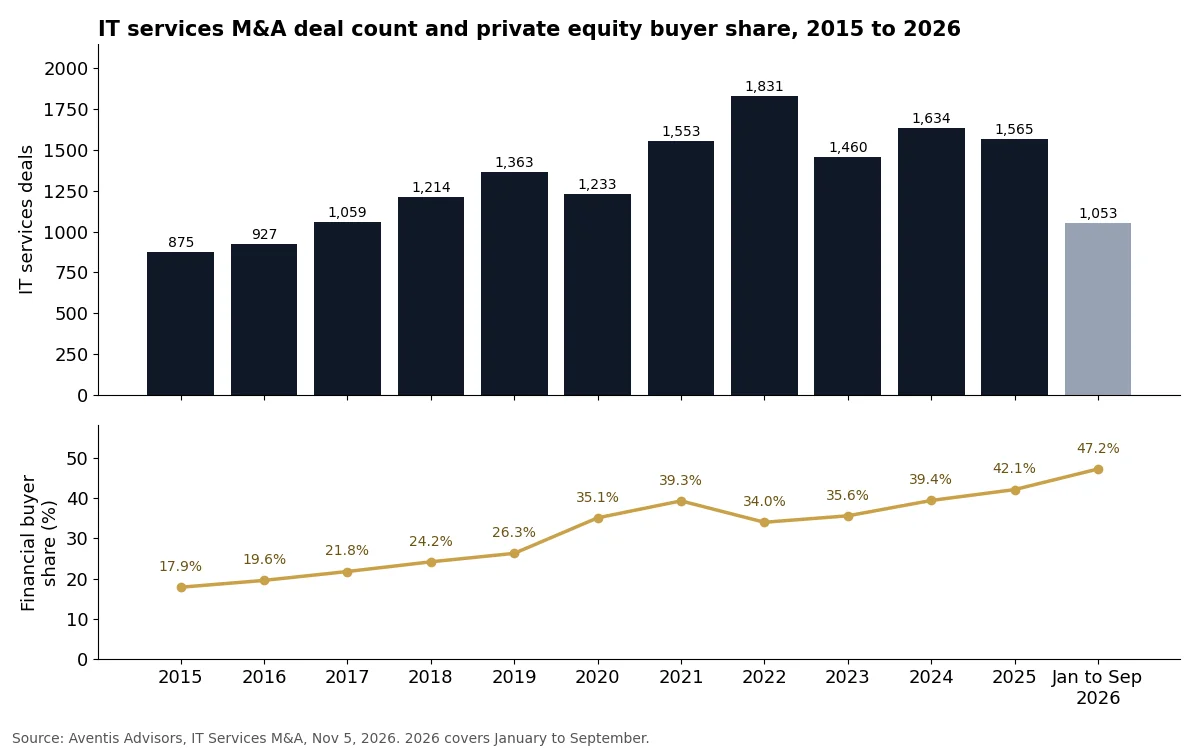
At the large end, EY’s technology services deal insights for H1 2026 counted at least 10 announced deals above US$300 million, with the seven largest worth about US$10.3 billion combined.
Which IT services mergers and acquisitions set the 2026 benchmarks?
The IT services mergers and acquisitions that set 2026 reference points are Computacenter’s purchase of GAI (up to $92M, May 2026), ScanSource’s $220.5M purchase of MicroAge (August 2026), Cognizant’s roughly $600M purchase of Astreya (April 2026) and H.I.G.’s Converge take-private at 7.4x. Only Converge and GAI disclosed enough to compute an EBITDA multiple.
| Announced | Acquirer | Target (type) | Disclosed terms | Multiple | Source |
|---|---|---|---|---|---|
| Aug 20, 2026 | ScanSource | MicroAge (VAR and MSP, 2,400+ US customers) | $220.5M all cash; close expected Sept 30, 2026 | Not disclosed | Channel Dive |
| May 28, 2026 | Computacenter | Government Acquisitions Inc (US federal VAR) | Up to $92M: $63M cash plus up to $29M by end 2027 | 7.9x upfront, 11.5x maximum, on $8M 2025 adjusted EBITDA | Computacenter RNS |
| Apr 29, 2026 | Cognizant | Astreya (AI infrastructure and data center services) | About $600M | Not disclosed | Reuters |
| Jan 8, 2026 | Computacenter | AgreeYa Solutions (professional services, circa $120M revenue) | Enterprise value up to $120M | About 1.0x revenue at the cap | IT Channel Oxygen |
| Aug 11, 2025 | Apollo funds | Trace3 (solutions provider), from American Securities | Undisclosed; closed Nov 3, 2025 | Not disclosed | Apollo, Business Wire |
| Jul 7, 2025 | Capgemini | WNS (digital operations) | About $3.3B cash, $76.50 per share | Not disclosed | Business Standard |
| Apr 7, 2025 | IBM | Hakkoda (data and AI consultancy) | Undisclosed | Not disclosed | TechCrunch |
| Feb 7, 2025 | H.I.G. Capital | Converge Technology Solutions (solutions provider) | C$5.50 per share cash, about C$1.3B enterprise value | About 7.4x TTM adjusted EBITDA to Sept 30, 2024 | Converge |
| Oct 17, 2024 | Xerox | ITsavvy (VAR, more than $400M revenue), from GenNx360 | $400M: $180M cash plus $220M secured notes | About 1.0x revenue | Xerox |
| Jun 10, 2024 | Cognizant | Belcan (engineering services) | About $1.3B: $1.19B cash plus shares worth $97M | Not disclosed | Cognizant |
| Apr 2, 2024 | CD&R funds | Presidio (majority stake from BC Partners) | Undisclosed | Not disclosed | Presidio |
| Dec 1, 2023 (closed) | Insight Enterprises | SADA (Google Cloud partner) | $410M cash plus earnout up to $390M (target $210M) through 2026 | Not disclosed | Insight 8-K |
Buyers paid for capability: Astreya for AI data center operations, Hakkoda for data consulting, SADA for a Google Cloud bench, GAI for federal contract access. H.I.G. later merged Converge with Mainline Information Systems to form Pellera Technologies, which now buys regional resellers as add-ons.
Why do value-added resellers sell for less than other IT services firms?
Value-added resellers sell for less because most of their revenue is pass-through hardware and software at thin margins. Aventis Advisors puts the reseller median at 0.5x revenue against 1.1x for the IT services set, and 7.9x EBITDA against 10.4x. Buyers size a reseller on gross profit and EBITDA, then pay more for each point of services and recurring gross profit.
Public resellers show the margin math. CDW reported 2025 net sales of $22.4 billion and a gross margin of 21.7%, down from 21.9% in 2024. Softcat reported gross invoiced income of £3.6 billion and gross profit of £494.3 million for FY2025, reported beside statutory revenue.
The GAI deal shows what happens if a seller quotes a revenue multiple. The worked table uses only figures from the Computacenter announcement.
| Step | Input | Result |
|---|---|---|
| Upfront price on EBITDA | $63M upfront / $8M 2025 adjusted EBITDA | 7.9x, level with the Aventis reseller median |
| Maximum price on EBITDA | $92M maximum / $8M | 11.5x, near the reseller upper quartile of 11.7x |
| Share of price at risk | $29M contingent / $92M | 32% |
| Price on gross invoiced income | $63M to $92M / about $390M | 0.16x to 0.24x |
| What a 1.1x IT services revenue median would imply | 1.1 x $390M | $429M, more than 4 times the real cap |
The services mix inside a reseller moves it between rows of the subsector table. The gap between the reseller median (7.9x) and the systems integration median (10.2x) is 2.3 turns, and the managed services median (9.9x) sits 2.0 turns above resellers. Owners of managed services books should use our MSP acquisitions tracker instead.
Worked example: one reseller, three prices
This illustrative example applies the Aventis quartiles to a hypothetical reseller with $2.0M of adjusted EBITDA. It shows the range a buyer can justify from public data, not a valuation of any company.
| Benchmark (Aventis Advisors) | Multiple | Enterprise value at $2.0M EBITDA | What gets a seller there |
|---|---|---|---|
| Reseller lower quartile | 5.4x | $10.8M | Single vendor line above 50% of gross profit, founder holds the top accounts |
| Reseller median | 7.9x | $15.8M | Diversified vendors, reviewed financials, some support contracts |
| Systems integration median | 10.2x | $20.4M | Services above half of gross profit, multi-year support renewals |
| Reseller upper quartile | 11.7x | $23.4M | Contract vehicles or vendor tier a buyer cannot build, competitive process |
The $4.6M gap between the reseller median and the integration median on the same $2.0M of EBITDA is the price of services mix.
Who buys IT services companies?
Private equity platforms and large integrators buy most IT services companies. Accenture made 145 IT services acquisitions from 2015 to 2025 per Aventis Advisors, followed by Evergreen Services Group with 71 and Sesa, including VAR Group, with 58. Financial buyers paid a median 11.3x EBITDA against 9.8x for strategic buyers over the same period.
| Acquirer (2015 to 2025) | IT services deals | Type | Source |
|---|---|---|---|
| Accenture | 145 | Global integrator | Aventis Advisors |
| Evergreen Services Group | 71 | PE-backed MSP and IT services platform | Aventis Advisors |
| Sesa (incl. VAR Group) | 58 | Listed reseller and services group | Aventis Advisors |
| Bechtle | 45 | Listed reseller and services group | Aventis Advisors |
| Capgemini | 39 | Global integrator | Aventis Advisors |
| Twenty (The 20 MSP) | 39 | MSP consolidator | Aventis Advisors |
| IBM | 38 | Global integrator | Aventis Advisors |
| Cognizant | 38 | Global integrator | Aventis Advisors |
The Evergreen count of 71 covers every IT services deal in the Aventis data; the narrower MSP count in our private equity MSP report is 50. Listed resellers such as Bechtle and Computacenter buy for geography and public-sector access.
The video covers valuation, buyer types and deal structure for MSP and IT services owners in 2026.
How are IT services and VAR deals structured?
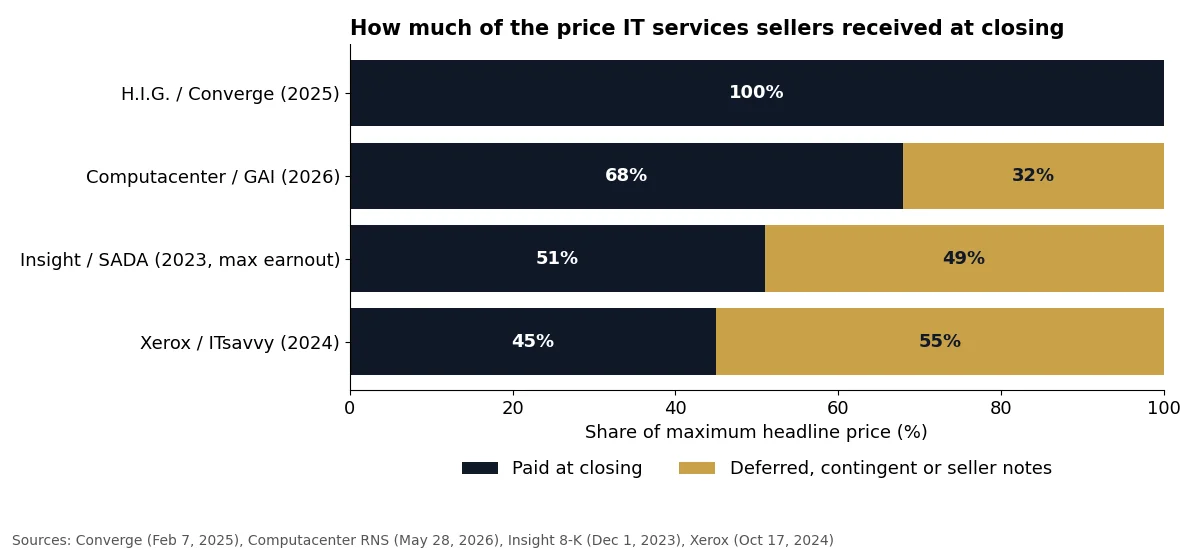
IT services and VAR deals put a large share of the price at risk after closing. In the disclosed deals, contingent pay or seller notes ran from 0% (Converge, all cash at C$5.50 per share) to 32% (GAI) and up to 49% (SADA at its maximum earnout), with Xerox paying 55% of the ITsavvy price in secured notes.
| Deal | Paid at closing | Deferred or contingent | Paid at closing / deferred, share of maximum price | Source |
|---|---|---|---|---|
| H.I.G. / Converge (2025) | C$5.50 per share cash | None for public holders | 100% / 0% | Converge release |
| Computacenter / GAI (2026) | $63M cash | Up to $29M performance payments through 2027 | 68% / 32% | Computacenter RNS |
| Insight / SADA (2023) | $410M cash | Earnout up to $390M, target $210M, through 2026 | 51% / 49% at maximum earnout; 34% deferred at target | Insight 8-K |
| Xerox / ITsavvy (2024) | $180M cash | $220M secured promissory notes | 45% / 55% | Xerox release |
A seller negotiating these terms should work through four steps in order:
- Set the earnout metric on services gross profit or EBITDA, never hardware revenue, which the buyer controls after closing through fulfillment routing. SADA’s earnout ran on EBITDA and revenue growth through 2026.
- Keep the earnout period short and dated. GAI’s contingent payments end with 2027, about 19 months after the June 1, 2026 close, and SADA’s ran through 2026.
- Ask for security on any seller paper. Xerox’s $220M of ITsavvy notes were secured, which is the standard to request.
- Agree a hardware-cycle-adjusted working capital peg before signing, with rebate receivables and in-transit product named in the definition. Our earnout benchmarks by deal size and rollover equity benchmarks give the ranges by deal size.
What should an IT services or VAR owner do before a sale?
An IT services owner should fix the facts that move a buyer between quartiles before starting a process: services share of gross profit, vendor and customer concentration, rebate dependence and EBITDA margin. Aventis Advisors finds that double-digit growth with 10% to 15% EBITDA margins supports a price above the 10.4x median, and margins below 10% pull it down.
| If your business shows | Expect | Do this before going to market |
|---|---|---|
| EBITDA margin below 10% | Pricing below the 10.4x median (Aventis) | Separate one-time hardware surges from repeat gross profit in a sell-side quality of earnings report |
| Double-digit growth and 10% to 15% margin | A case above the median (Aventis) | Run a competitive process with at least two sponsor platforms |
| One vendor line above 50% of gross profit | Reseller lower quartile, near 5.4x | Document vendor tier and deal registration transfer on change of control |
| A customer above 15% of gross profit (above 25% is structured) | Earnout or holdback tied to that account | Extend that contract before launch |
| Rebates above 25% of EBITDA | Rebate income priced at a discount or moved into an earnout | Restate EBITDA net of at-risk rebates yourself, so the buyer’s model is not the only one |
| Over half of gross profit from managed or recurring services | MSP pricing, a 9.9x median (Aventis) | Benchmark against MSP deals, not reseller deals |
| Federal or state contract vehicles | A buyer paying for access, as Computacenter did for GAI | Confirm the vehicle transfers and its recompete date is beyond 12 months |
Owner dependency cuts across every row: when the founder holds the top accounts and the vendor relationships, buyers move price into structure, as covered in how owner dependency affects valuation. A sell-side quality of earnings report settles rebates and the working capital peg before a buyer does.
Which IT services M&A figures circulate with errors?
Four IT services M&A figures circulate with errors: the SADA price, the ITsavvy date, the basis of the Converge multiple and the pure reseller band of 3x to 5x EBITDA, which the July 2026 edition of this report also carried. Each row names the primary source.
| What circulates | What the primary source says | Source |
|---|---|---|
| Insight bought SADA for about $920 million (MarketScreener) | $410M at closing plus an earnout of up to $390M, target $210M | Insight 8-K, Dec 1, 2023 |
| Xerox bought ITsavvy in 2022 | GenNx360 owned ITsavvy; Xerox announced its $400M purchase on Oct 17, 2024 | Xerox release |
| Converge sold at 7.4x 2025 EBITDA | About 7.4x adjusted EBITDA for the twelve months to Sept 30, 2024 | Converge release |
| Pure resellers sell for 3x to 5x EBITDA (July 2026 edition of this page) | Disclosed reseller deals: 5.4x lower quartile, 7.9x median, 91 deals; small private deals can still price lower | Aventis Advisors |
How we compiled this
We compiled this report in November 2026 from 19 sources: Aventis Advisors’ IT services multiples and deal-count datasets (updated July 31 and November 5, 2026), company and sponsor releases for each named deal, Insight’s SEC Form 8-K, Computacenter’s stock exchange announcement, CDW and Softcat results, and named trade reporting. Deal multiples are our arithmetic from disclosed terms. We used no CT Acquisitions client data, surveys or forum posts.
CT Acquisitions helps owners of founder-owned IT services, reseller and managed services businesses run a confidential sale, recapitalization or exit plan, with a 500+ buyer network. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells. You can book a confidential call to test your numbers against the tables above, or start with the cluster report on IT and managed services M&A multiples.
Frequently asked questions
What is M&A in the IT industry?
M&A in the IT industry means buying, selling or merging IT services companies such as resellers, managed service providers, integrators and consultancies. Aventis Advisors counted 1,565 IT services deals in 2025 and 1,053 from January to September 2026. The same phrase also describes integrating the IT systems of two merging companies, which is a post-close workstream rather than a valuation question.
What multiple do value-added resellers sell for?
Disclosed value-added reseller deals priced at a median 7.9x EV/EBITDA across 91 transactions from 2015 to 2025, with a lower quartile of 5.4x and an upper quartile of 11.7x, per Aventis Advisors. On revenue the median was 0.5x across 177 deals. Computacenter’s 2026 purchase of GAI priced at 7.9x upfront and 11.5x at its maximum.
What are some recent IT services mergers and acquisitions?
Recent IT services mergers and acquisitions include ScanSource buying reseller MicroAge for $220.5 million (August 2026), Computacenter buying federal reseller GAI for up to $92 million (May 2026), Cognizant buying Astreya for about $600 million (April 2026) and Computacenter buying AgreeYa Solutions for up to $120 million (January 2026).
Who are the Big 4 in M&A?
The Big 4 are Deloitte, PwC, EY and KPMG, the four largest accounting networks, whose transaction services teams run due diligence and valuation work on larger deals. EY’s technology services deal insights for H1 2026 counted at least 10 deals above US$300 million. Owner-led IT services sales under $50M more often pair a sector adviser with a quality of earnings firm.
Do IT services companies sell for more than MSPs?
Slightly, at the median. Aventis Advisors puts all IT services deals at 10.4x EV/EBITDA and managed service providers at 9.9x, while value-added resellers trail at 7.9x and data and analytics firms lead at 16.0x. Subsector and size matter more than the label: deals under $5M priced at a median 6.7x across all IT services.
Sources
All sources accessed November 14, 2026.
- Aventis Advisors, IT Services Valuation Multiples (July 31, 2026)
- Aventis Advisors, IT Services M&A (Nov 5, 2026)
- Computacenter, Acquisition of Government Acquisitions Inc (May 28, 2026)
- Channel Dive, ScanSource to buy MicroAge (Aug 20, 2026)
- Reuters, Cognizant to buy Astreya (Apr 29, 2026)
- IT Channel Oxygen, Computacenter and AgreeYa (Jan 8, 2026)
- Apollo, agreement to acquire Trace3 (Aug 11, 2025)
- Business Wire, Trace3 acquisition completed (Nov 3, 2025)
- Business Standard, Capgemini to acquire WNS (Jul 7, 2025)
- TechCrunch, IBM acquires Hakkoda (Apr 7, 2025)
- Converge Technology Solutions, H.I.G. agreement (Feb 7, 2025)
- H.I.G. Capital, Pellera Technologies formation
- Xerox, ITsavvy acquisition (Oct 17, 2024)
- Cognizant, Belcan agreement (Jun 10, 2024)
- Presidio, CD&R agreement (Apr 2, 2024)
- Insight Enterprises, Form 8-K on SADA (Dec 1, 2023)
- CDW, Q4 and full-year 2025 results (Feb 4, 2026)
- Softcat, FY2025 preliminary results
- EY, Technology services deal insights H1 2026
Market research compiled from public sources. Not an appraisal, a fairness opinion or investment, legal or tax advice.
Related research: for the 2026 IT and Managed Services M&A Multiples Report, the cluster pillar comparing MSP + MSSP + IT Services and VAR verticals, see the linked report.
Related research: for the 2026 MSP M&A Multiples Report, sibling spoke covering the recurring-MRR premium this report’s VAR-to-MSP conversion arbitrage targets, see the linked report.
Related research: for the 2026 MSSP and Cybersecurity Services M&A Multiples Report, sibling spoke with MDR premium analysis, see the linked report.
