
The EBITDA Multiple for Manufacturing Companies in 2026: Baseline Ranges, 4 Adjustments, and Sub-Vertical Data
The EBITDA multiple for manufacturing companies averaged 7.1x in the first half of 2026 for private equity deals valued at $10M to $500M (GF Data via Mercer Capital): smaller deals price lower, larger ones higher.
Key takeaways
- Sponsor-backed manufacturing buyouts averaged 7.1x adjusted EBITDA in the first half of 2026, up from 6.7x in 2025, per GF Data figures published in the Mercer Capital Middle Market Transaction Update, Fall 2026.
- Size moves the number more than anything else: GF Data recorded 6.4x for $10M to $25M deals and 9.7x for $250M to $500M deals in 2024 (GF Data, April 2025).
- Below about $10M of deal value the data shifts to DealStats and Bizcomps: a 4.80x median EBITDA multiple for lower middle market deals and 2.55x SDE for businesses above $1M of revenue, as summarized by IndustryWeek, November 2, 2026.
- The “6x to 12x” packaging and industrial machinery range is real but blends three things: 6.2x for listed packaging machinery peers in May 2026 (Carlsquare), 10.3x for 2025 packaging deals (Capstone Partners) and 12.4x to 15.5x for strategic equipment deals.
- Public company multiples are not your multiple: Damodaran’s January 2026 data puts listed U.S. machinery makers at 16.22x EBITDA, more than double the private manufacturing average (NYU Stern).
What is the EBITDA multiple for manufacturing companies in 2026?
Private equity buyers paid an average of 7.1x adjusted EBITDA for U.S. manufacturers in the first half of 2026, per GF Data, which tracks sponsor-backed deals valued at $10M to $500M. GF Data reported 7.3x for the first quarter alone, against 7.0x for 2025 (IndustryWeek, November 2026). Owners with $1M to $25M of EBITDA should read that average as the midpoint of a band running roughly 6x to 9x by deal size.
The table below lists the numbers buyers and their lenders quote most often, with the dataset, period and what each one measures. Use the GF Data rows for sponsor deals, the DealStats and Bizcomps rows for owner-operated shops, and the Damodaran rows only as a ceiling check.
| Metric | Figure | Period | Source |
|---|---|---|---|
| Manufacturing buyouts, average TEV / adjusted EBITDA | 7.1x (6.7x in 2025) | First half 2026 | GF Data via Mercer Capital |
| Manufacturing buyouts, average | 7.3x (7.0x in 2025) | Q1 2026 | GF Data via IndustryWeek |
| All industries, $10M to $50M deals | About 6.8x | Q2 2026 | GF Data via Mercer Capital |
| All industries, $50M to $250M deals | About 7.6x | Q2 2026 | GF Data via Mercer Capital |
| Lower middle market private deals, median EBITDA multiple | 4.80x | Latest DealStats cut | DealStats via IndustryWeek |
| Businesses above $1M revenue, average SDE multiple | 2.55x SDE | Latest Bizcomps cut | Bizcomps via IndustryWeek |
| Listed U.S. machinery companies, EV / EBITDA | 16.22x | January 2026 | Damodaran, NYU Stern |
One caution on comparisons: GF Data multiples exclude buyer transaction costs, which Mercer Capital estimates add about 0.3x to all-in cost. A buyer quoting 7.1x on paper is spending closer to 7.4x once its own legal, quality of earnings and financing fees are counted, which is one reason sponsors push back on add-backs.
How does deal size change manufacturing EBITDA multiples?
Bigger deals clear higher multiples. In GF Data’s 2024 figures, buyouts valued at $10M to $25M averaged 6.4x adjusted EBITDA, $50M to $100M deals averaged 8.3x and $250M to $500M deals 9.7x. Platform buyouts above $100M carried a 2.7 turn premium over smaller platforms across 2020 to 2024, because more buyers, cheaper debt and lower risk all scale with size.
GF Data sorts deals by total enterprise value (TEV), not by EBITDA. The right-hand column converts each band into the EBITDA range it implies at that band’s 2024 multiple, so an owner can find the row that matches the business. This is CT Acquisitions arithmetic on GF Data’s published averages.
| TEV band | 2003 to 2019 average | 2024 average | Implied EBITDA at the 2024 multiple |
|---|---|---|---|
| $10M to $25M | 5.8x | 6.4x | $1.6M to $3.9M |
| $25M to $50M | 6.5x | 6.8x | $3.7M to $7.4M |
| $50M to $100M | 7.5x | 8.3x | $6.0M to $12.0M |
| $100M to $250M | 8.2x | 8.6x | $11.6M to $29.1M |
| $250M to $500M | 9.0x | 9.7x | $25.8M to $51.5M |
| All deals | 6.6x | 7.2x | 379 completed deals in 2024 |
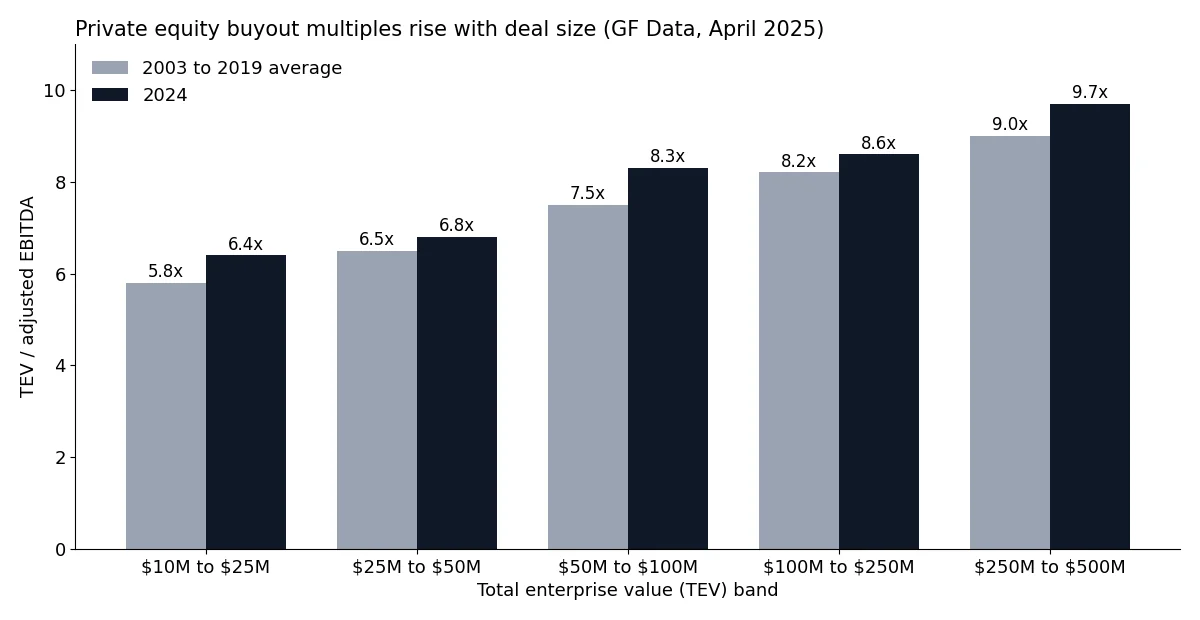
The step from the first band to the second matters to most founder-led manufacturers. Moving from 6.4x to 6.8x adds 0.4 turns; on $3.9M of EBITDA that is about $1.56M of enterprise value before any change in earnings (CT Acquisitions arithmetic, illustrative). Owners sitting just under a band edge often gain more from 12 months of earnings growth than from any negotiating tactic.
What happens below $10M of deal value?
Below the GF Data floor, buyers are search funds, independent sponsors, SBA-financed individuals and small strategics, and they price on lower multiples. DealStats shows a 3.76x median EBITDA multiple for companies under $1M of revenue and 12.49x above $100M of revenue, per Anthony Venette of Withum writing in IndustryWeek in November 2026. The same article reports a 3.81x average for companies with $1M to $5M of revenue.
For owner-operated shops, many buyers switch from EBITDA to seller’s discretionary earnings (SDE), which adds back one owner’s full pay. Bizcomps data puts the median at 2.15x SDE for main street owner-operated shops and the average at 2.55x SDE above $1M of revenue (IndustryWeek). The CT guide to how SDE is calculated and when buyers use it covers the switch point.
What do manufacturing subsectors sell for?
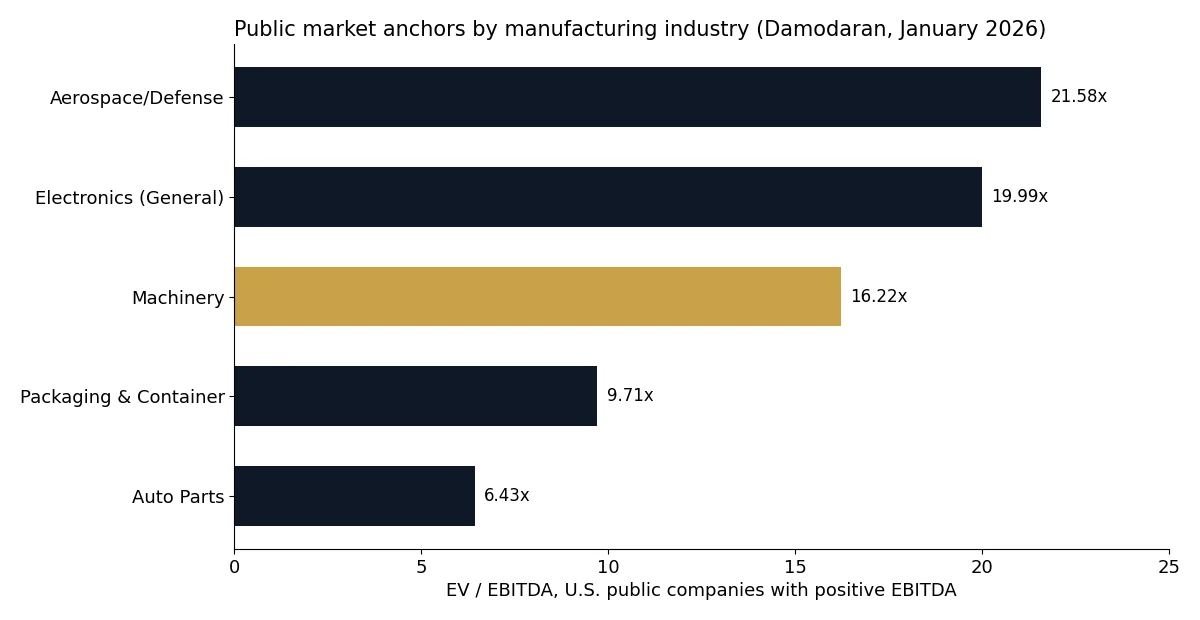
Subsector shifts a private manufacturer’s multiple by roughly 1 to 3 turns around the GF Data average. Regulated, aftermarket-heavy niches such as aerospace suppliers and food processing equipment sit at the top; capex-heavy, cyclical niches such as plastics molding and automotive Tier 2 sit at the bottom. Listed peers show the same order: Damodaran’s January 2026 data runs from 6.43x for auto parts to 21.58x for aerospace and defense.
No free dataset publishes private-deal multiples for each subsector at the $2M to $10M EBITDA size, so the CT column is labelled as an estimate. The public and deal columns are the named anchors those estimates were checked against.
| Subsector | Public anchor (EV / EBITDA) | Named deal or survey evidence | CT Acquisitions estimate, $2M to $10M EBITDA (illustrative) |
|---|---|---|---|
| Precision machining | Machinery 16.22x (Damodaran, Jan 2026) | Manufacturing buyouts 7.1x (GF Data, 1H 2026) | 5x to 7x; AS9100 work 6.5x to 9x |
| Contract manufacturing | Machinery 16.22x (Damodaran) | Manufacturing buyouts 7.1x (GF Data) | 4.5x to 6.5x |
| Packaging machinery | 6.2x, five year median 7.9x (Carlsquare, May 2026) | JBT and Bevcorp 15.5x (Baird, 2022) | 6x to 9x; strong aftermarket 8x to 10x |
| Plastics injection molding | Packaging & Container 9.71x (Damodaran) | Packaging deals 6.5x YTD 2026 (Capstone) | 4.5x to 6.5x |
| Food processing equipment | Processing machinery 10.7x (Carlsquare) | Hillenbrand and LINXIS 12.4x (Baird, 2022) | 7x to 10x |
| Aerospace and defense suppliers | Aerospace/Defense 21.58x (Damodaran) | Public acquirer median 11.85x (DealStats via IndustryWeek) | 6.5x to 10x |
| Electronics contract manufacturing | Electronics (General) 19.99x (Damodaran) | Manufacturing buyouts 7.1x (GF Data) | 5x to 7x |
| Automotive Tier 2 parts | Auto Parts 6.43x (Damodaran) | Private acquirer median 4.20x (DealStats via IndustryWeek) | 4x to 6x |
Precision machining and contract manufacturing
Job shops and build-to-print contract manufacturers price close to the GF Data manufacturing average of 7.1x when they reach $3M to $5M of EBITDA, and below it when one customer or one program dominates. AS9100 or ISO 13485 certification moves a shop toward the upper end because requalifying a supplier takes customers months. The CT pages on private equity firms buying manufacturers in 2026 name the active sponsors by niche.
Plastics injection molding
Molders carry heavy press and tooling capex, often serve automotive or appliance programs, and usually trade 0.5 to 1 turn under machining in CT Acquisitions estimates. Listed Packaging & Container companies, where many custom molders sit, trade at 9.71x (Damodaran, January 2026), well under the 16.22x for machinery. Customer-owned molds help: they keep tooling off your balance sheet, but they also make the customer easier to lose.
Food processing equipment
Processing machinery commands more than packaging machinery in every dataset checked here: 10.7x versus 6.2x for listed peers in May 2026 (Carlsquare), and 12.0x versus 8.5x in Baird’s February 2024 snapshot. Food safety rules, sanitary design and a large spare parts base make these suppliers hard to replace, and strategics such as JBT, which closed its EUR 3.4 billion Marel deal in January 2025, keep buying.
Aerospace and defense suppliers
Aerospace suppliers with AS9100, NADCAP special process approvals and multi-year agreements sit near the top of the private range, but defense exposure now carries two compliance tests. CMMC Phase 2 begins November 10, 2026, adding a Level 2 third-party (C3PAO) assessment as a condition of award on applicable contracts under 32 CFR 170.3(e), and ITAR registrants must give 60 days’ notice before a sale to a foreign buyer. The CT guide to choosing an M&A advisor for a manufacturing sale covers how to vet an advisor’s defense experience.
Packaging machinery M&A EBITDA multiples: where does the 6x to 12x range come from?
Packaging machinery companies sell for roughly 6x to 12x EBITDA, and each end of that range has a named source. The low end matches listed packaging machinery peers at 6.2x (Carlsquare, May 2026) and 2026 packaging deals at 6.5x (Capstone Partners, July 2026). The high end matches 2025 packaging deals at 10.3x and strategic equipment purchases at 12.4x to 15.5x (Baird, March 2024).
The range gets quoted without sources on many advisor sites. The table below lists every free, dated figure CT Acquisitions could verify for packaging and adjacent processing equipment, with what each one measures. Public peer multiples price listed companies on forward EBITDA; transaction multiples price whole companies, usually larger than a founder-led builder.
| Figure | What it measures | Date | Source |
|---|---|---|---|
| 6.2x | Listed packaging machinery peers, EV / 2026E EBITDA | May 8, 2026 | Carlsquare |
| 7.9x | Same peer group, five year median | May 8, 2026 | Carlsquare |
| 6.5x | Average packaging transaction, year to date | July 2026 | Capstone Partners |
| 8.5x | Listed packaging equipment peers, median EV / NTM EBITDA | February 29, 2024 | Baird |
| 9.3x | Average packaging transaction, 2018 to YTD 2026 | July 2026 | Capstone Partners |
| 10.3x | Average packaging transaction, full year 2025 | July 2026 | Capstone Partners |
| 10.7x | Listed processing machinery peers, EV / 2026E EBITDA | May 8, 2026 | Carlsquare |
| 12.0x | Listed food technology equipment peers | February 29, 2024 | Baird |
| 12.4x | Hillenbrand buys LINXIS Group, $584M | July 19, 2022 | Baird |
| 15.5x | JBT buys Bevcorp (beverage processing and packaging equipment), $290M | July 27, 2022 | Baird |
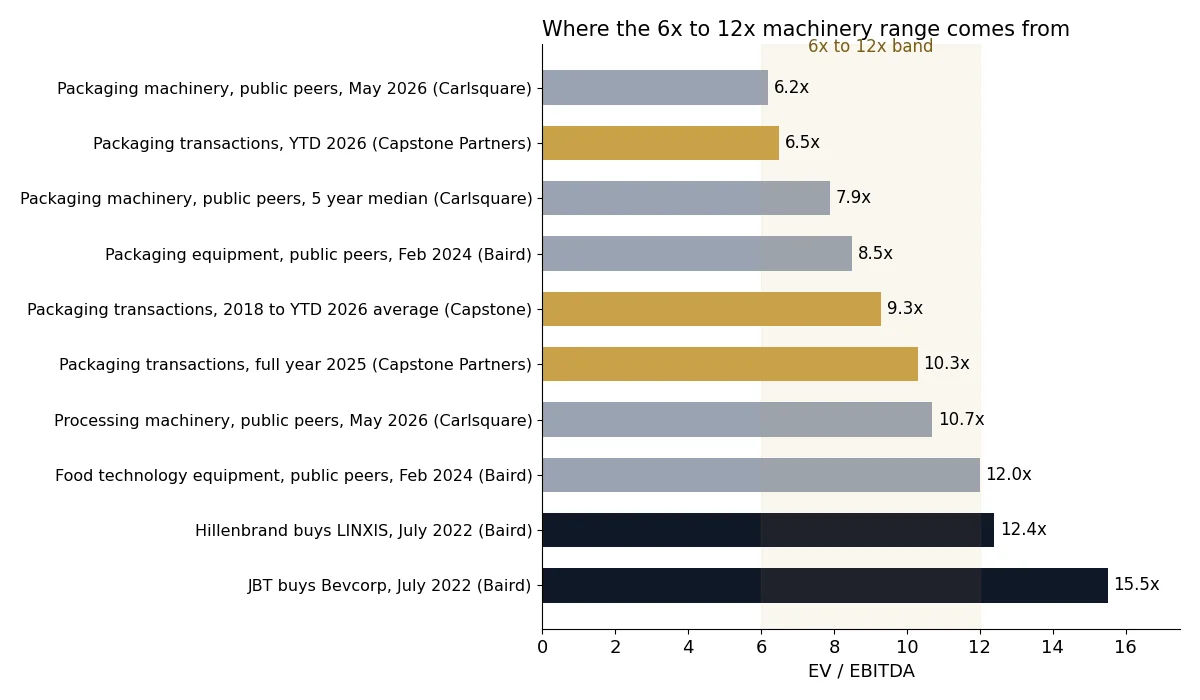
Capstone’s packaging figures cover the whole packaging sector, converters included, not only machinery builders. Its July 2026 update counted 8 print and packaging equipment deals year to date against 12 a year earlier, so the machinery sample is thin. A founder-owned builder with $2M to $5M of EBITDA should anchor on the lower half of the range unless aftermarket revenue changes the picture.
Why aftermarket revenue decides where a packaging builder lands
A packaging machinery maker is two businesses. New filling, capping, cartoning or palletizing lines are lumpy project revenue with milestone billing; spare parts, service contracts, retrofits and format change parts recur on the installed base whatever the order book does. CT Acquisitions estimates that aftermarket revenue at 30% or more of sales adds 0.5 to 1 turn, because buyers can underwrite it like a contract.
To get credit, report aftermarket as its own line with gross margin, installed base by machine model and year, and parts revenue per installed machine for 36 months. Builders that bury service inside project revenue get valued as project shops. The CT packaging business valuation guide covers converters and co-packers, which price on different drivers.
What moves the multiple up or down?
Seven drivers move a manufacturer’s multiple inside its size band: customer concentration, end-market cyclicality, capex needs and machine age, ERP and quoting discipline, owner dependence, union status and, for defense suppliers, CMMC and ITAR. GF Data’s 2024 drilldown shows the scale of the effect: deals with above-average financials averaged 7.7x and those with a post-closing management team 7.4x, against 7.2x for all deals.
| Driver | Threshold buyers test | Typical effect (CT Acquisitions estimate, illustrative) | Rule or data behind it |
|---|---|---|---|
| Customer concentration | Top customer at 10%, 25% and 40% of revenue | 25% to 40%: minus 0.5x to 1.5x; above 40%: earnout likely | ASC 280-10-50-42 flags any customer at 10% or more |
| End-market cyclicality | Share of sales to automotive, oil and gas or housing | Minus 0.5x to 1x for heavy cyclical exposure | Auto Parts 6.43x vs Aerospace/Defense 21.58x listed (Damodaran) |
| Capex and machine age | Average machine age above 15 years, deferred rebuilds | Price deduction for catch-up capex | Most machinery is 7 year MACRS property (IRS Pub 946) |
| ERP and quoting discipline | Job costing tied to the general ledger, quote win rates tracked | Plus 0.25x to 0.5x | Supports a clean quality of earnings review |
| Owner dependence | Owner quotes jobs, holds key accounts or signs off quality | Minus 0.5x to 1x | Post-closing management 7.4x vs 7.2x (GF Data, 2024) |
| Union status | Collective bargaining agreement in force | 0 to minus 0.5x | 7.7% of manufacturing workers are members (BLS, 2025) |
| Defense compliance | CMMC Level 2 status, ITAR registration | Minus 0.5x to 1x or a delayed close if gaps exist | 32 CFR 170.3(e); 22 CFR 122.4(b) |
Customer concentration
Public companies must disclose any single customer at 10% or more of revenue under ASC 280-10-50-42, and private buyers use the same 10% line to start their questions. Common-control entities count as one customer, so three plants of one OEM are one account. The CT analysis of how customer concentration cuts valuation shows how earnouts get sized against a large account.
Capex needs and machine age
Buyers price the machines they must replace in the first three years. Since Public Law 119-21 restored 100% bonus depreciation for qualified property acquired and placed in service after January 19, 2025 (IRS Publication 946), many owners have written new machines down to zero. In an asset sale, the gain on those machines up to prior depreciation is Section 1245 recapture taxed as ordinary income (IRS Publication 544), so the purchase price allocation on Form 8594 matters as much as the multiple.
ERP, quoting discipline and owner dependence
A buyer underwriting a job shop wants to see quoted margin against realized margin by job for at least 24 months. When that history lives in the owner’s head or a spreadsheet, the buyer assumes the owner is the quoting engine and discounts for the risk of the owner leaving. GF Data’s 2024 deals with a post-closing management solution averaged 7.4x against 7.2x across all deals.
Union status
Manufacturing is more unionized than the private sector: 7.7% of manufacturing workers were union members in 2025 and 8.4% were represented, against 5.9% and 6.8% for all private workers (BLS, February 18, 2026). A buyer that hires a majority of your workforce is a Burns successor that must recognize and bargain with the union, per the National Labor Relations Board. Multiemployer pension exposure, not the union itself, usually moves price.
Which EBITDA adjustments do buyers accept or reject?
Buyers accept adjustments that are documented, non-recurring or plainly personal, and reject ones that depend on future events. In CT Acquisitions’ illustrative example below, $590K of add-backs survive, a $120K negative adjustment for below-market rent cuts the other way, and $550K of claimed add-backs fail. The surviving adjusted EBITDA of $3.87M is the number the multiple gets applied to.
| Adjustment | Buyer usually | What makes it stick | Example amount (illustrative) |
|---|---|---|---|
| Owner pay above a market general manager salary | Accepts | Salary survey or recruiter quote for the replacement role | +$350K |
| One-time ERP implementation | Accepts | Invoices and a go-live date; no repeat spend | +$180K |
| Personal vehicles, family travel | Accepts | General ledger detail by account | +$60K |
| Rent on an owner-owned building below market | Deducts | Buyer resets rent to a broker opinion of market rent | minus $120K |
| Lost margin on a late project | Rejects | Rarely sticks; late projects recur in project businesses | $250K rejected |
| Price increase announced but not yet billed | Rejects | Only sticks once invoiced for a full quarter | $300K rejected |
| Deferred machine rebuilds | Deducts from price | Equipment appraisal and a three year capex plan | $600K off enterprise value |
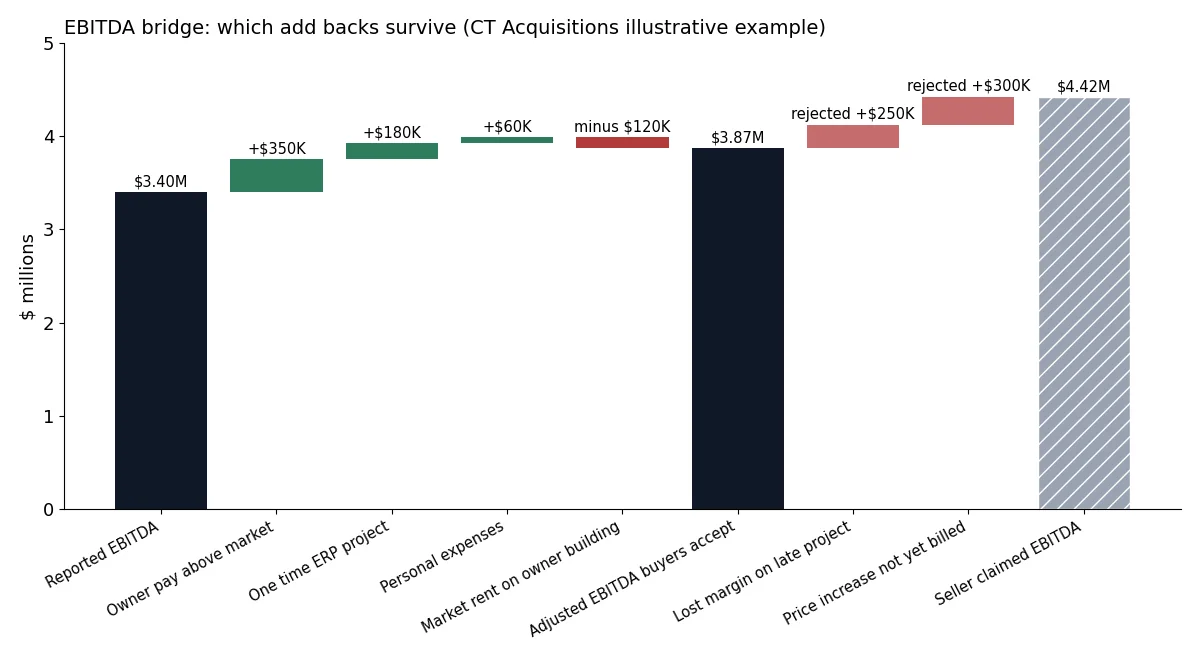
The difference is large at a 7.3x multiple: the $550K of rejected add-backs is worth about $4.0M of headline value. The CT guide to which add-backs survive a quality of earnings review lists the documentation buyers ask for by category.
Worked example: from reported EBITDA to enterprise value
This illustrative example follows a founder-led packaging machinery builder with $22M of revenue and $3.40M of reported EBITDA. Accepted adjustments lift EBITDA to $3.87M, the GF Data $25M to $50M band supplies a 6.8x starting multiple, and four adjustments move it to 7.3x. After a $600K deduction for deferred machine capex, enterprise value lands near $27.65M. It is CT Acquisitions arithmetic, not a client deal.
| Step | Input | Result |
|---|---|---|
| 1. Reported EBITDA | From reviewed financial statements | $3.40M |
| 2. Accepted adjustments | +$350K, +$180K, +$60K, minus $120K | $3.87M adjusted EBITDA |
| 3. Starting multiple | $3.87M x 6.8x = $26.32M sits in the $25M to $50M band (GF Data, 2024) | 6.8x |
| 4. Aftermarket parts and service at 35% of revenue | CT estimate | +0.75x |
| 5. Owner still runs quoting and key accounts | CT estimate | minus 0.5x |
| 6. ERP job costing tied to the ledger for 36 months | CT estimate | +0.25x |
| 7. Top customer at 18% of revenue | Below the 25% line where discounts start | No change; 7.3x working multiple |
| 8. Enterprise value | $3.87M x 7.3x | $28.25M |
| 9. Less deferred machine capex | Appraisal-backed rebuild plan | $27.65M |
| 10. Seller’s unadjusted view | $4.42M claimed EBITDA x 7.3x | $32.27M, a $4.62M gap |
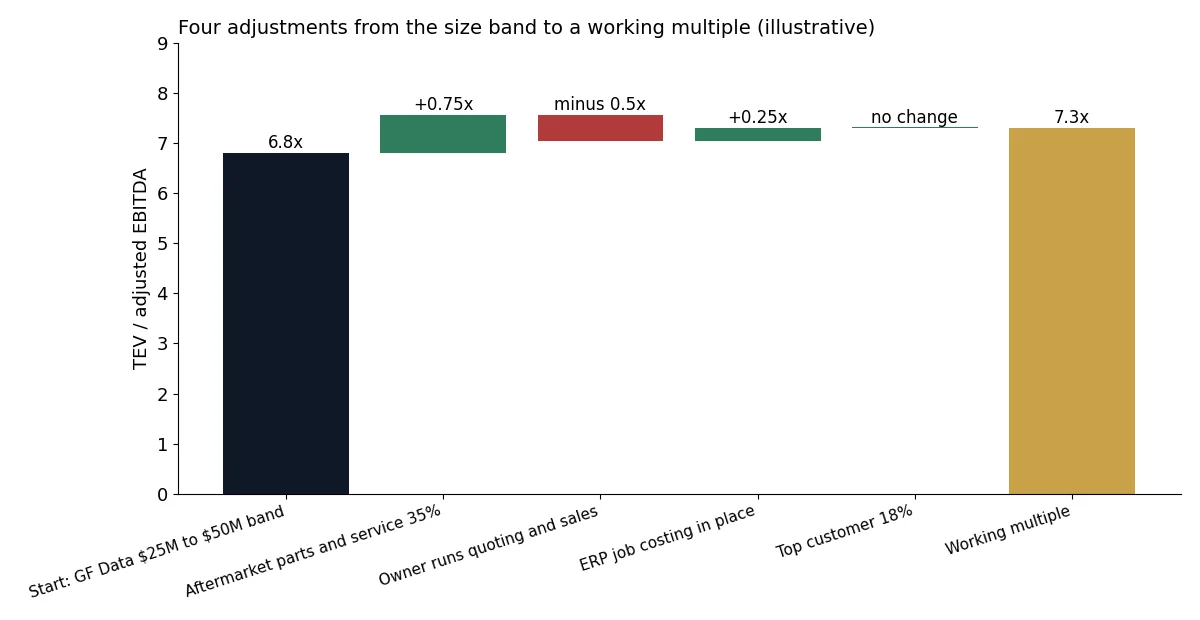
Two levers in this example are within the owner’s control before a sale: handing quoting and key accounts to a sales manager would remove the 0.5x discount, worth about $1.94M on $3.87M of EBITDA, and a funded rebuild plan would turn the $600K deduction into a documented capex history. Enterprise value is not cash at closing; working capital, debt and escrow come off next.
Want to test your manufacturing EBITDA multiple against real buyers?
CT Acquisitions helps owners of founder-owned businesses make the most of their exit through confidential sales, recapitalizations and exit planning, with a network of 500+ buyers. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells. A confidential call gives you a likely range for your plant and the buyer types that would compete for it.
What should a manufacturer do before going to market?
Fix the drivers buyers discount before the first buyer call, because each is cheaper to fix than to concede in a purchase agreement. In CT Acquisitions estimates, transferring key accounts, documenting aftermarket revenue and settling CMMC status are worth 0.5 to 1 turn each. ITAR registrants selling to a foreign buyer must also file 60 days ahead under 22 CFR 122.4(b).
| If your situation is | Do this | Why |
|---|---|---|
| EBITDA under $1.5M and you quote every job | Expect SDE pricing near 2.55x; hire or promote a general manager first | Bizcomps average above $1M revenue (IndustryWeek) |
| EBITDA of $3M to $4M | Time the sale for when trailing EBITDA clears about $3.9M | GF Data band moves from 6.4x to 6.8x |
| Top customer at 25% of revenue or more | Sign a multi-year supply agreement before marketing | Shrinks the earnout a buyer asks for |
| Aftermarket at 30% of sales or more | Report it as a separate line with margin and installed base | Buyers pay for recurring parts revenue |
| DoD contracts and no CMMC Level 2 assessment | Book a C3PAO assessment before signing a letter of intent | Phase 2 starts November 10, 2026 |
| ITAR registered and a foreign buyer is likely | Add 60 days to the closing timeline for DDTC notice | 22 CFR 122.4(b) |
| Union workforce | Share the bargaining agreement and pension filings in the data room early | Buyer may be a Burns successor |
| Average machine age above 15 years | Commission an equipment appraisal and a three year capex plan | Turns an open-ended discount into a fixed deduction |
Most of this work takes 12 to 24 months. Run it in this order:
- Close the books monthly and get reviewed statements for 36 months. Buyers test adjusted EBITDA against three years of history, and reviewed statements cut the time a quality of earnings firm spends on cash proof.
- Tie job costing in the ERP to the general ledger. Show quoted versus realized margin by job for 24 months so the buyer can see quoting discipline without interviewing the owner.
- Move key accounts and quoting to a second-tier manager. GF Data deals with post-closing management averaged 7.4x against 7.2x in 2024.
- Lock in the largest customer. Any account at 10% of revenue or more will be questioned; a signed multi-year agreement answers the question before it is asked.
- Document the fixed asset register. List each machine with model, year, condition and planned rebuild, backed by an appraisal; the CT manufacturing sale preparation checklist covers the rest of the data room.
How does the multiple turn into cash at closing?
Enterprise value is the start of the purchase price, not the wire. Debt is repaid, the working capital peg is trued up and part of the price often stays in the business as rollover: GF Data counted rollover equity in 63.6% of 2024 deals at an average of 14.5% of the price. In asset sales, Form 8594’s seven asset classes decide which dollars are taxed as ordinary income.
For a manufacturer, the machinery class carries the Section 1245 recapture and Class VII carries goodwill, usually taxed at capital gains rates. Sellers who compare two offers at the same multiple should compare after-tax proceeds under each allocation, then compare how much is cash at closing versus rollover, earnout or escrow. The CT EBITDA multiples by industry page shows how manufacturing compares with other sectors in the same market.
How we compiled this
CT Acquisitions compiled this page in November 2026 from 16 documents, 14 of them primary or first-party: GF Data figures, Carlsquare, Capstone Partners and Baird sector reports, Damodaran’s January 2026 dataset, BLS union tables, federal regulations, IRS publications and the ASC 280 summary at Deloitte. DealStats and Bizcomps figures come second-hand through IndustryWeek because both databases are paid. Rows labelled CT Acquisitions estimates are judgement, and no client deals are described.
Frequently asked questions
What is the EBITDA multiple for a manufacturing company?
Private equity buyers paid an average of 7.1x adjusted EBITDA for U.S. manufacturers in the first half of 2026, per GF Data via Mercer Capital. Size sets most of the range: GF Data’s 2024 averages ran from 6.4x for $10M to $25M deals to 9.7x for $250M to $500M deals, and smaller owner-operated shops often sell on SDE instead.
What EBITDA multiple do packaging machinery companies sell for?
Packaging machinery companies sell for roughly 6x to 12x EBITDA. Listed packaging machinery peers traded at 6.2x in May 2026 (Carlsquare), packaging deals averaged 6.5x year to date in 2026 and 10.3x in 2025 (Capstone Partners), and strategic equipment deals reached 12.4x to 15.5x (Baird). Aftermarket parts and service revenue decides which end a builder reaches.
What is a good EBITDA multiple by industry?
For sponsor-backed U.S. deals in the first half of 2026, GF Data recorded 7.1x for manufacturing, 7.7x for healthcare services, 7.5x for business services and 5.7x for technology, per Mercer Capital’s Fall 2026 update. A good multiple for a manufacturer is one at or above its size band, for example above 6.8x for a $25M to $50M deal.
Why do small manufacturers sell for lower multiples?
Smaller manufacturers draw fewer buyers, carry more owner dependence and are financed with costlier debt. DealStats shows a 3.76x median EBITDA multiple for companies under $1M of revenue against 12.49x above $100M, per IndustryWeek in November 2026. GF Data’s 2024 platform deals above $100M averaged 9.2x against 6.7x for $10M to $100M deals.
What is the EBITDA multiple for electronics and automotive parts manufacturers?
Listed electronics companies traded at 19.99x EBITDA and listed auto parts makers at 6.43x in January 2026, per Damodaran at NYU Stern. Private multiples are lower: CT Acquisitions estimates 5x to 7x for electronics contract manufacturers and 4x to 6x for automotive Tier 2 suppliers with $2M to $10M of EBITDA, before customer concentration.
Does a union workforce lower a manufacturer’s multiple?
A union workforce rarely blocks a sale, but it narrows the buyer pool and adds diligence. In 2025, 7.7% of U.S. manufacturing workers were union members (BLS). A buyer that hires most of your workforce must bargain with the union as a Burns successor, per the NLRB, and multiemployer pension liabilities usually affect price more than the contract itself.
Sources
- Mercer Capital, Middle Market Transaction Update, Fall 2026 (GF Data figures), accessed November 2026.
- GF Data, Highlights and Products, Fourth Quarter 2024, April 2025.
- IndustryWeek, EBITDA Valuations for Manufacturing Companies Aren’t What You Think (DealStats, Bizcomps and GF Data figures, secondary source), November 2, 2026.
- Carlsquare, Processing and Packaging Machinery, May 8, 2026.
- Capstone Partners, Print, Paper and Packaging Market Update, July 2026.
- Baird, Industrial Equipment Sector Update, March 2024.
- Aswath Damodaran, EV/EBITDA by industry (US), January 2026 data, accessed November 2026.
- BLS, Union Members 2025, Table 3, February 18, 2026.
- NLRB, Bargaining in good faith with employees’ union representative, accessed November 2026.
- 32 CFR 170.3, CMMC program implementation, accessed November 2026.
- McGuireWoods, DoD final DFARS CMMC rule, September 10, 2025.
- 22 CFR 122.4, ITAR notification of changes, accessed November 2026.
- Deloitte DART, ASC 280 major customer disclosures, accessed November 2026.
- IRS Publication 946 (2025), How To Depreciate Property, accessed November 2026.
- IRS Publication 544, Sales and Other Dispositions of Assets, accessed November 2026.
- IRS, Instructions for Form 8594, accessed November 2026.
About the Author
Christoph Totter is the founder of CT Acquisitions, an M&A advisory firm that helps owners of founder-owned businesses make the most of their exit through confidential sales, recapitalizations and exit planning, headquartered in Sheridan, Wyoming. We work directly with 500+ buyers, search funders, family offices, lower middle-market PE, and strategic consolidators, including direct mandates with the largest consolidators that other intermediaries cannot access. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells. Connect on LinkedIn · Get in touch
Related Guide: Manufacturing Business Valuation Multiples (2026), Multiples by sub-vertical with reasoning, sources, and ranges.
Related Guide: How to Value a Manufacturing Business, 2026 methodology, multiples, and capital-intensity math.
Related Guide: What Is My Manufacturing Business Worth?, Step-by-step valuation walkthrough by sub-vertical and size band.
Related Guide: How to Sell a Manufacturing Business, 18-24 month playbook, QoE prep, buyer types, deal mechanics.
Related Guide: SDE vs EBITDA: Which Metric Matters, How to choose the right earnings metric for your size and structure.
Want a Specific Read on Your Business?
30 minutes, confidential, no contract, no cost. You leave with a view of your local buyer market and a likely valuation range.
