
Hood Cleaning Business Valuation 2026: What Buyers Actually Pay
By Christoph Totter, Managing Partner, CT Acquisitions. Last verified October 2026. Quarterly refresh target.
A hood cleaning business valuation in 2026 turns on one question before any multiple gets quoted: how much of the revenue is code-mandated and recurring, and how much is one-off work that disappears after the invoice clears. Two kitchen exhaust companies billing the same amount in a year are frequently not worth the same to a buyer, because value here tracks the durability of the revenue rather than the top line. A book built on scheduled NFPA 96 cleaning routes and semiannual NFPA 17A suppression inspection contracts reads very differently in diligence than a book built on call-when-you-remember one-off jobs, even at identical sales.
We are CT Acquisitions, a buy-side M&A advisor. This guide walks through what buyers appear to pay for commercial kitchen hood cleaning and fire suppression businesses in 2026, why the pricing metric changes as you scale, why the regulatory backdrop makes the recurring revenue unusually sticky, and the one transfer risk that quietly reprices more of these deals than any multiple does. Because the honest comparable data here is thin and the market-size estimates disagree, we label what is a proxy, what is secondary, and where the sources conflict rather than averaging them into a tidy number no source actually publishes.
Two businesses sold under one roof
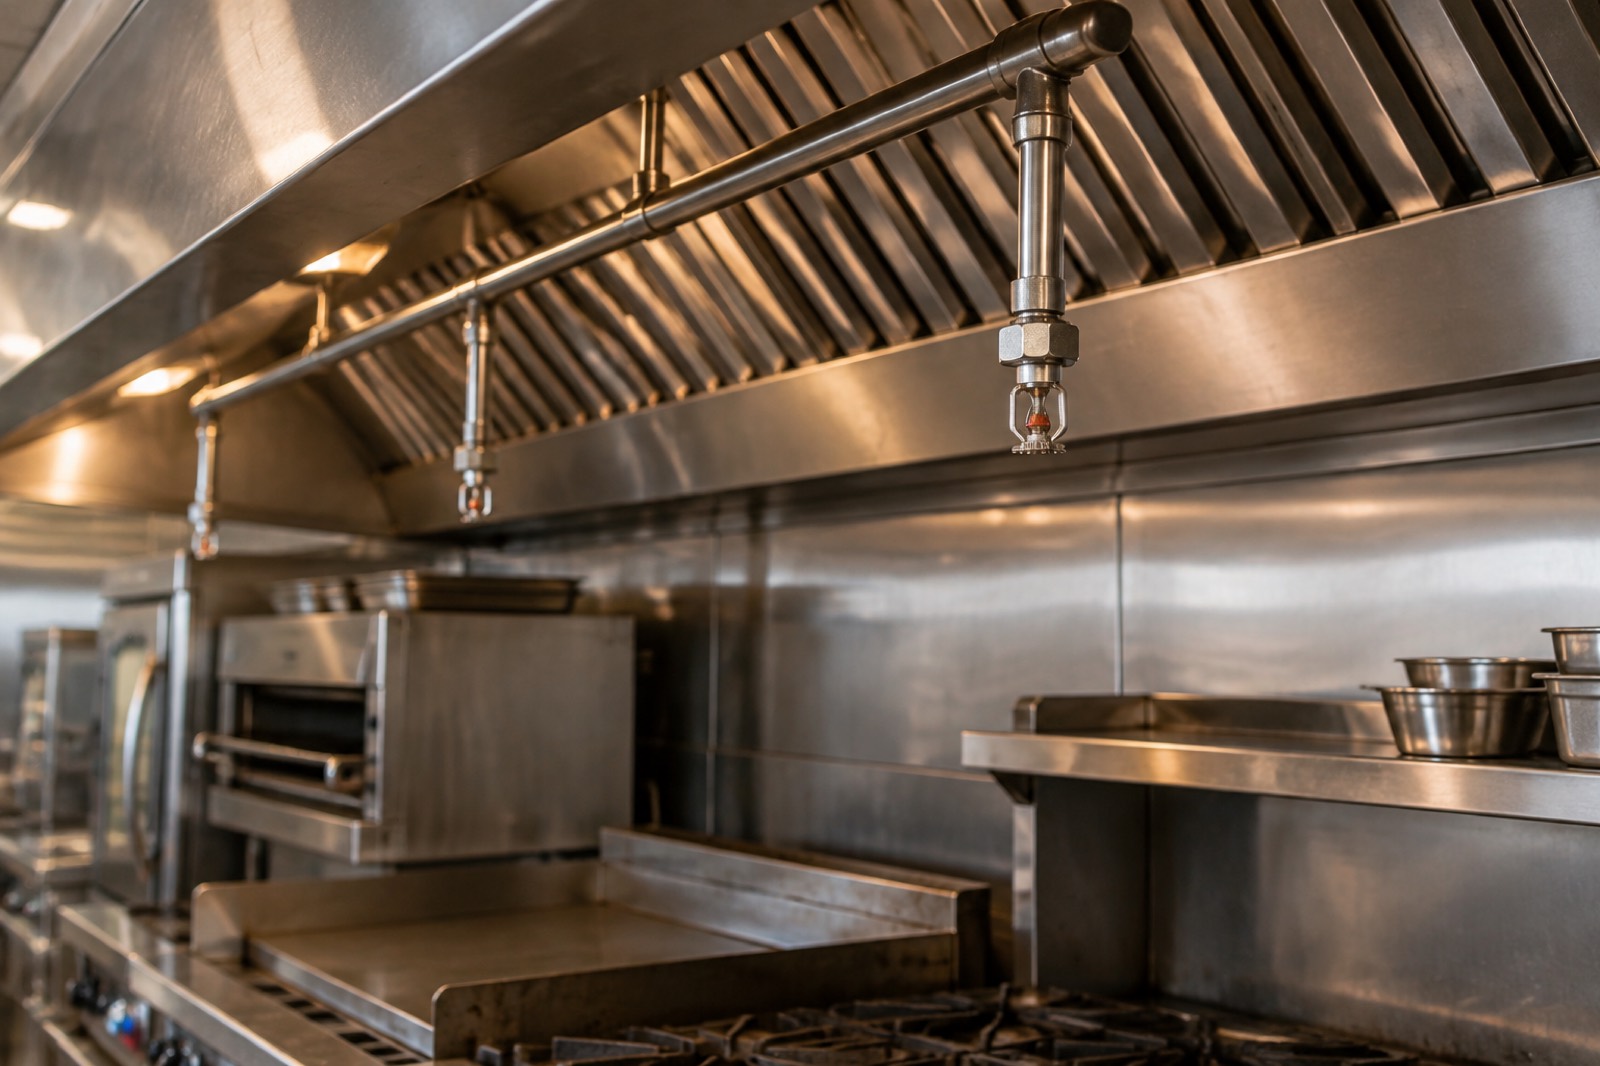
Most operators in this space run two related but distinct services, and buyers price them as two different revenue streams. The first is commercial kitchen exhaust cleaning: the physical degreasing of hoods, ducts, and fans to bare metal on a recurring schedule. The second is kitchen fire suppression service: the inspection, testing, and maintenance of the wet-chemical extinguishing system that sits over the cooking line. They are commonly sold together because the same customer needs both and the same visit can touch both, but they carry different licensing, different margins, and different buyer appeal.
The reason this split matters for valuation is that both services are tied to recurring, code-referenced schedules rather than discretionary spend, and buyers underwrite recurring compliance-driven revenue more generously than project work. An operator whose revenue is dominated by scheduled cleaning routes and semiannual suppression inspections is selling an annuity with a regulatory spine behind it. An operator whose revenue is mostly one-time deep cleans and ad hoc call-outs is selling labor, and labor without a contract underneath it is the revenue a buyer trusts least.
The code-mandated recurring revenue engine
This is the differentiator for the vertical, and it needs to be framed precisely, because the loose version of the claim is wrong and a diligent buyer will catch it. Hood cleaning and kitchen fire suppression generate code-mandated recurring revenue, but the mandate does not come from NFPA 96 or NFPA 17A on their own. NFPA 96 is a standard, and a standard is voluntary until a jurisdiction adopts it. The legal force comes from code adoption by reference: the International Fire Code (IFC) requires commercial cooking systems to be installed and maintained in accordance with NFPA 96, and the International Mechanical Code and Uniform Mechanical Code reference NFPA 96 as the primary standard for commercial kitchen exhaust (up.codes, IFC Section 904.12 text, accessed October 2026; facilitec-sw.com NFPA 96 codes guide, accessed October 2026). When a state or locality adopts the IFC and IMC, which the vast majority do, NFPA 96 and NFPA 17A become enforceable law, and fire marshals enforce them. So the accurate framing is code-mandated via IFC and IMC adoption, enforced by fire marshals, not NFPA 96 legally requires on its own.
Within that adopted code, the cleaning schedule is volume-based rather than one-size-fits-all. The requirement sets a minimum cleaning and inspection frequency that scales with how hard the kitchen cooks: solid-fuel cooking such as wood, charcoal, and char-broiling is on the most frequent schedule, high-volume and 24-hour operations next, moderate-volume full-service kitchens less often, and low-volume operations such as seasonal or occasional-use kitchens the least often (tfp1.com NFPA 96 cleaning frequency, accessed October 2026; service-techcorp.com hood cleaning, accessed October 2026). We cite the volume-based requirement rather than a specific table or section number on purpose: the editions shift, and the table numbering is not stable across them. The standard also requires cleaning to bare metal and inspection by trained, qualified personnel acceptable to the authority having jurisdiction, and that authority can require more frequent cleaning if it finds heavy contamination.
The suppression side is just as sticky and is primary-sourced. The wet-chemical extinguishing system over the cooking line must be serviced at least semiannually, roughly six months apart, by trained and qualified persons, with the fusible-link temperature-sensing elements replaced at least annually and a monthly owner inspection on top of that (NFPA 17A, Standard for Wet Chemical Extinguishing Systems, Section 7.2 through 7.3, read directly; atapars.com NFPA 17A full-text PDF, accessed October 2026). NFPA 17A also references UL 300, which is why modern restaurant suppression systems must be UL 300 listed. We cite the semiannual requirement itself rather than a specific section number, because the freely verifiable full text is an older edition and the numbering moves, though the semiannual cadence has been stable across editions.
There is a third enforcer that operates independently of the fire code: insurers. Carriers condition coverage on documented NFPA 96 compliance and deny fire claims where cleaning documentation is missing or outdated, and NFPA 17A itself names the insurance inspection department or rating bureau as a possible authority having jurisdiction (oxmaint.com NFPA 96 maintenance guide, accessed October 2026; NFPA 17A Annex A, read directly). So the recurring revenue is pushed by two forces at once, the adopted fire code and the insurance underwriter, which is structurally comparable to the recurring-inspection thesis behind NFPA 25 fire sprinklers. The practical takeaway for a seller is that documented compliance records are not paperwork, they are the asset a buyer underwrites, and the contracts attached to that cadence are the part of the business that commands a premium.
Which metric applies to you
Before anchoring on any number, understand that these businesses are not all priced the same way. There is a fork, and which side you land on depends on your earnings level, not your revenue.
Below roughly $1M in earnings, which is where most single-truck and small-route operators sit, hood cleaning and suppression businesses are priced on seller’s discretionary earnings, or SDE. The buyer pool at this level is SBA-financed individuals, local and regional operators, and search funders, and SDE is the language they and their lenders use, because the buyer is stepping into the owner’s seat and replacing the owner’s labor.
Above roughly $1M in earnings, the convention shifts to adjusted EBITDA, because the buyer pool changes to platforms and sponsor-backed consolidators who normalize owner compensation and think in EBITDA turns. That is a genuinely different buyer with a different financing structure, not a cosmetic relabeling.
We will not quote an EBITDA multiple for a business earning under $1M, and you should be wary of anyone who does. A back-calculated EBITDA multiple on a small owner-operated route is an arithmetic artifact, not a price anyone offered. It also matters to be precise that SDE and EBITDA measure different things and are not interchangeable: SDE includes the owner’s compensation and discretionary items that EBITDA strips out, so a 3x SDE figure and a 3x EBITDA figure describe different businesses and different cash flows. You cannot convert one to the other by keeping the multiple and swapping the label. We also never treat a revenue multiple as a valuation; it is a cross-check only, not a statement that your business equals revenue times a factor.
Where the bands fall in 2026
Here is the honesty problem with benchmarks for this vertical, stated plainly: there is no public BizBuySell category for hood cleaning specifically. The closest honest proxy is BizBuySell’s broad service-business aggregate, and even that we treat as secondary, because BizBuySell’s valuation-benchmarks page returned an access block on direct fetch and the figures reached us through its own indexed content via search rather than a clean on-page read. So the numbers below are a service-business proxy, labeled secondary, and they describe small service businesses generally, not hood cleaning specifically.
| Source | Metric | Figure | Tier |
|---|---|---|---|
| BizBuySell service business (proxy) | Median asking price | $350,000 | Secondary, proxy |
| BizBuySell service business (proxy) | Median revenue | $654,792 | Secondary, proxy |
| BizBuySell service business (proxy) | Median SDE | $173,205 | Secondary, proxy |
| BizBuySell service business (proxy) | Revenue multiple | 0.41x to 1.09x, median 0.72x | Secondary, proxy |
| BizBuySell service business (proxy) | SDE multiple | 1.58x to 3.61x, median 2.55x | Secondary, proxy |
How to read this. On the BizBuySell service-business proxy, the median small service business asks about $350,000 on roughly $654,792 of revenue and $173,205 of SDE, which pencils to a revenue multiple around 0.72x at the median and an SDE multiple around 2.55x at the median, with SDE multiples ranging from about 1.58x to 3.61x (BizBuySell service business benchmarks, secondary, via search; direct fetch returned an access block). Treat these as a reality check on the small end of the market, not as a hood-cleaning-specific appraisal. A well-run, contract-dense operation with genuine route density and sticky suppression inspection agreements can sit at the upper end of or above that SDE band precisely because the recurring compliance-driven revenue is what a buyer underwrites, while a one-off-heavy book sits at the bottom.
A note on platform multiples. You will see much higher turns quoted for scaled, PE-backed fire and life-safety platforms. We deliberately do not attach a headline platform multiple to this page, because the cleanest articulation of those tiers in public search traces back to sources we cannot treat as independent, and a platform-premium multiple is not comparable to what a single owner-operated route sells for in any case. If you are a small operator, the service-business proxy above is the honest anchor, not a platform number.
The qualifier-license transfer trap
This is the single most important diligence item specific to this vertical, and it is the one that most often reprices a deal after the handshake. Kitchen fire suppression work is licensed at the state and local level, and the license routinely attaches to a designated person, a qualifying individual, rather than to the company. That person has to hold a specific credential, commonly the ICC or NAFED Pre-Engineered Kitchen Fire Extinguishing Systems certification, and act as the qualifier on the contractor’s permit.
The examples are consistent across jurisdictions we checked. New Jersey requires a Kitchen Fire Suppression System Contractor to list a state-certified qualifying individual who has passed the ICC or NAFED pre-engineered kitchen systems exam (nj.gov Division of Fire Safety contractor permit form, accessed October 2026). Kentucky and Louisville require both a state and a Louisville-Jefferson County fire suppression contractor license (louisvilleky.gov fire detection and suppression permits, accessed October 2026). Colorado Springs requires an FSC-B license to design, install, service, or inspect commercial kitchen hood suppression (coloradosprings.gov 2021 IFC commercial kitchen document, accessed October 2026). Philadelphia, New York City, Pittsburgh, and Iowa all operate fire suppression contractor and worker licensing regimes built on NICET or ICC/NAFED credentials plus a qualifier (phila.gov, nyc.gov Department of Buildings, dial.iowa.gov, all accessed October 2026).
Here is why that is a valuation issue and not a footnote. If the selling owner is personally the qualifying individual, the buyer may lose the legal ability to perform suppression work the day after close, unless the buyer already employs a qualified individual or retains one. That single fact shapes the deal structure. It argues for an earn-out, a consulting or transition period that keeps the seller or a licensed employee in place while the buyer re-qualifies or hires, or a buyer who already holds the relevant state license. It also tilts the realistic buyer pool toward strategic and platform acquirers who already carry multi-state licensing and certified staff, and away from a purely financial buyer with no fire-trade footprint. In our experience, a seller who maps the qualifier question early, and ideally develops a second licensed individual inside the business well before a sale, protects the suppression revenue that is often the stickiest and highest-value part of the book.
Hood cleaning itself carries lighter licensing and in many places needs no state suppression license, but it has its own version of the same issue: the quality signal buyers value is technician certification through the International Kitchen Exhaust Cleaning Association or the Certified Exhaust Cleaning Technician credential, and those certifications attach to individuals, not to the company. Retention of certified technicians through the transition is therefore part of diligence on the cleaning side, even though the legal transfer risk is lower than on suppression.
What else buyers examine
Beyond the licensing question, buyers work through a consistent checklist, and most of it maps directly onto the recurring-revenue thesis. Route density is first: a dense cluster of recurring NFPA 96 cleaning accounts in a tight geography is worth more per dollar of revenue than the same revenue scattered across a wide area, because the drive time between jobs is the hidden cost. Contract structure is next: semiannual NFPA 17A suppression inspection agreements and scheduled cleaning contracts, in writing, with renewal history, are the sticky revenue a buyer will pay up for, versus handshake arrangements that walk when the owner does.
Documented compliance records matter in their own right, because they are the proof that the recurring revenue is real and code-driven, and they are what an insurer or fire marshal would ask to see. Certifications held in-house, both the IKECA or CECT technician certifications on the cleaning side and the state suppression license on the suppression side, reduce the buyer’s integration risk. Customer concentration cuts the other way: a book where a few chains or a single large account dominate revenue is riskier than a diversified one, and buyers discount for it. Chain, master service agreement, and multi-location relationships are a genuine positive, because they are hard to win and hard to dislodge. Running through all of it is owner dependence: if the owner is the lead technician, the dispatcher, the sales relationship, and the license qualifier all at once, a buyer discounts for the transition risk, because they are buying a business they intend to run without you.
Who is buying
The buyer picture in this vertical is specific, and it surprises owners who expect a dedicated private-equity check for a hood-cleaning route. There is no pure-play PE roll-up acquiring independent hood-cleaning operators at scale. Consolidation runs on two separate tracks, and which one fits you depends on whether your revenue leans cleaning or suppression.
On the cleaning side, consolidation happens through franchise platforms rather than buyers of standalone EBITDA. HOODZ International sits inside BELFOR Franchise Group and is the largest kitchen-exhaust cleaning network in North America, and Green Guard Services and Kitchen Guard sit under EverSmith Brands, a platform of The Riverside Company, which invested in Green Guard in April 2023 (belforfranchisegroup.com, accessed October 2026; riversidecompany.com Green Guard release, accessed October 2026). The practical implication is that for a standalone cleaning operator, the realistic exit is usually a local or regional strategic, a facilities-services buyer, or conversion into a franchise network, not a headline PE check.
On the suppression side, the real institutional money shows up through fire and life-safety platforms that absorb kitchen suppression firms as a sub-segment of their inspection, testing, and maintenance work. Pye-Barker Fire & Safety, backed by Altas Partners and Leonard Green & Partners with ADIA and GIC joining as minority investors in early 2025, has acquired commercial-kitchen suppression firms as tuck-ins; Marmic Fire & Safety was acquired by KKR in July 2024 and is described in deal materials as regulation-mandated inspection, testing, and maintenance; Summit Companies passed to BDT & MSD Partners in August 2025; and AI Fire moved to Blackstone in early 2025 (lw.com KKR and Marmic, accessed October 2026; summitcompanies.com, accessed October 2026; additional platform entries secondary). For the full named-buyer landscape, deal flow, and sponsor pairings on both tracks, see our hood cleaning and suppression PE roll-up tracker. Because kitchen suppression is itself a fire and life-safety service, owners weighing which platforms are consolidating the broader category should also read our private equity in fire and life safety guide.
The 18 to 36 month preparation sequence
The levers that pay the most in this vertical are also the ones that take the longest to build, which is why the preparation window is best measured in years rather than months. We generally think in terms of roughly 18 to 36 months.
In the first stretch, the priority is converting loose work into contracted recurring revenue: putting scheduled NFPA 96 cleaning accounts and semiannual NFPA 17A suppression inspections onto written agreements, tightening route density in your core geography, and beginning to reduce dependence on one-off deep cleans. This is the stretch that moves revenue quality, which is what the multiple ultimately rewards.
In the middle stretch, the work turns to management depth, certification bench, and diligence readiness: developing a second in-house qualifying individual for the suppression license so the business is not one person away from losing its ability to do the work, keeping IKECA or CECT certified technicians on staff and documented, building clean compliance records that a buyer or insurer could audit on sight, and reducing customer concentration where a single account dominates the book.
In the final stretch, the job is the transfer path itself, because it takes the longest and carries the most risk. Confirm exactly how the state and local suppression licenses will be handled given the likely buyer and deal structure, since the qualifier attaches to a person; diligence each chain and master service agreement for its own change-of-control and assignment terms; and make sure the compliance documentation that proves the recurring revenue is organized and current. An owner who has done this presents a materially cleaner story than one who assumes the license and the contracts simply follow the keys, and the qualifier question is the single area where a headline valuation most often erodes.
For where this vertical sits relative to other trades, see our EBITDA multiple by industry guide. To get a directional read on your own numbers, our valuation tool is a reasonable starting point.
Category context
The market-size picture here is genuinely unsettled, and we present it as a range rather than a single figure because the published sources disagree on scope. MarketResearchIntellect puts the US commercial kitchen exhaust cleaning services market at roughly $1.5 billion in 2024, projected to about $2.5 billion by 2033 at roughly a 7.3% CAGR (marketresearchintellect.com, secondary, directional). IMARC Group, measuring a narrower and differently defined commercial kitchen cleaning services market, puts it at roughly $412.8 million in 2025 at about a 6.73% CAGR (imarcgroup.com, accessed October 2026, secondary). Those two numbers are not reconcilable, because they are not measuring the same thing, so the honest statement is that estimates range from roughly $413 million to roughly $1.5 billion depending on how the category is scoped, and anyone quoting one of them as the market size has quietly chosen a scope and hidden the other.
What both sources agree on, along with the franchise and platform sponsors active in the space, is that the industry is highly fragmented, made up of a large number of independent operators ranging from local owner-operators to regional franchise networks to full-service facility-maintenance firms (hoodzfranchise.com, accessed October 2026; riversidecompany.com Green Guard release, accessed October 2026; both secondary). That fragmentation, combined with revenue that an adopted fire code and insurers both push to recur, is exactly the setup that draws the franchise expansion and the fire-ITM roll-up capital described above.
About CT Acquisitions
We are CT Acquisitions, a buy-side M&A advisor working across commercial kitchen hood cleaning, fire suppression, and adjacent home and commercial-services trades. Our network includes 500+ capital partners, and our job is to orient owners and buyers to what the market is actually doing rather than to a headline multiple.
Thinking about a sale within 18 months
No fee to you on buy-side introductions; sell-side mandates are paid on success at closing. Book a call.
Buyers and sponsors
For acquirers, we offer two services: vertical mapping that delivers targeted operators with direct contact data, or a retained search built to your thesis. Both start with a conversation. Book a call.
Frequently asked questions
What is a hood cleaning business worth in 2026?
It depends on your earnings level and on recurring-revenue quality, and the honest benchmark is a proxy. There is no public hood-cleaning-specific category, so we use BizBuySell’s service-business aggregate as a secondary proxy: median SDE multiple around 2.55x, ranging roughly 1.58x to 3.61x, on a median SDE near $173,205 (BizBuySell service business, secondary, via search). A contract-dense, route-dense operation with sticky suppression inspection agreements sits at or above the top of that band; a one-off-heavy book sits at the bottom.
Should I use an SDE or an EBITDA multiple?
Below roughly $1M in earnings, which is most of this market, use SDE; the buyer pool is SBA-financed individuals, local operators, and search funders who speak in SDE. Above roughly $1M, buyers shift to adjusted EBITDA. SDE and EBITDA multiples measure different things and are not interchangeable, so never quote an EBITDA multiple for a sub-$1M owner-operated route.
Is hood cleaning really code-mandated recurring revenue?
Effectively yes, with one honest caveat about where the mandate comes from. NFPA 96 and NFPA 17A are standards that are voluntary on their own; their legal force comes from adoption by reference through the International Fire Code and the International and Uniform Mechanical Codes, which most US jurisdictions adopt and fire marshals enforce (up.codes IFC Section 904.12; facilitec-sw.com, both accessed October 2026). Insurers independently condition coverage on documented compliance. So the accurate framing is code-mandated via IFC and IMC adoption, not that NFPA 96 legally requires it on its own.
How often is hood cleaning and suppression service required?
NFPA 96, as adopted, sets a volume-based cleaning schedule: the most frequent for solid-fuel cooking, then high-volume and 24-hour operations, then moderate-volume full-service kitchens, then low-volume operations (tfp1.com; service-techcorp.com, accessed October 2026). NFPA 17A requires the wet-chemical suppression system to be serviced at least semiannually by qualified persons, with fusible links replaced at least annually and a monthly owner inspection (NFPA 17A Section 7.2 through 7.3, read directly). We cite the requirement rather than a specific table or section number because editions shift.
What is the biggest transfer risk when selling a suppression business?
The suppression license usually attaches to a qualifying individual, a specific certified person, not to the company (nj.gov Division of Fire Safety; louisvilleky.gov; coloradosprings.gov, all accessed October 2026). If that person is the selling owner, the buyer can lose the legal ability to do suppression work at close unless they already employ or retain a qualified individual. That argues for an earn-out, a transition period, or a buyer who already holds the license, and it favors platform and strategic buyers with multi-state licensing.
Who actually buys these businesses?
Two tracks. Hood cleaning consolidates through franchise platforms such as HOODZ under BELFOR Franchise Group and Green Guard and Kitchen Guard under EverSmith Brands, a Riverside Company platform (belforfranchisegroup.com; riversidecompany.com, accessed October 2026). Kitchen suppression gets absorbed as a sub-segment by fire and life-safety ITM platforms such as Pye-Barker, Marmic under KKR, Summit under BDT & MSD, and AI Fire under Blackstone. For the full buyer map, see our hood cleaning and suppression PE roll-up tracker.
How big is the market?
Sources disagree because they scope the category differently. MarketResearchIntellect puts US commercial kitchen exhaust cleaning services near $1.5 billion in 2024, while IMARC Group puts a narrower commercial kitchen cleaning services market near $412.8 million in 2025 (both secondary, accessed October 2026). The honest statement is a range of roughly $413 million to $1.5 billion depending on scope, not a single figure.
How long does it take to prepare one of these businesses for sale?
Plan on roughly 18 to 36 months. The first stretch converts one-off work into contracted recurring NFPA 96 cleaning and semiannual NFPA 17A suppression accounts and tightens route density, the middle stretch builds management depth, a second in-house license qualifier, certified technicians, and auditable compliance records, and the final stretch cleans the license-transfer path, the change-of-control terms on chain and MSA contracts, and the compliance documentation.
Disclaimer
CT Strategic Partners LLC dba CT Acquisitions is a buy-side M&A advisor. We are not a registered investment bank, broker-dealer, or appraiser. Multiple ranges are directional observations from cited sources and active engagement observations, not point estimates; where figures are proxies or sources disagree, they are presented as such. SDE and EBITDA multiples measure different things and are not interchangeable. Regulatory, licensing, and code references are general summaries, not legal or compliance advice; requirements vary by jurisdiction and change over time. Individual outcomes vary materially. Past patterns are not a guarantee of future results.