
How Much Tax When You Sell a Business: The 2026 Tax Rate on Sale of Business Gains
The federal tax rate on sale of business gain in 2026 is 0%, 15% or 20% on long-term capital gain, up to 37% on depreciation recapture and 25% on unrecaptured Section 1250 gain, plus 3.8% NIIT only for passive owners.
By Christoph Totter, Founder of CT Acquisitions · Last reviewed: November 2026
General information for U.S. owners, not tax advice: confirm your numbers with a CPA before you sign a letter of intent.
Key takeaways
- For 2026, a married couple pays 0% on long-term gain up to $98,900 of taxable income, 15% up to $613,700 and 20% above (IRS Rev. Proc. 2025-32).
- The 3.8% NIIT starts at $250,000 of joint or $200,000 of single MAGI and does not apply to income from an active business (IRS Topic 559).
- In an asset sale, equipment gain up to prior depreciation is ordinary income taxed at up to 37%, while goodwill is capital gain (Form 8594 instructions).
- For C corporation stock acquired after July 4, 2025, QSBS excludes 50% of gain after 3 years, 75% after 4 and 100% after 5, up to $15,000,000 (Public Law 119-21, Section 70431).
- Washington taxes long-term gains at 7%, and 9.9% above $1 million from tax year 2025 (Washington DOR).
If part of the price is equity in the buyer, that slice can be deferred under Section 351 or 721, as our guide to rollover equity tax treatment explains.
Goodwill bought in an earlier acquisition is partly ordinary income on resale, which we break down in our guide to how is goodwill taxed.
What is the tax rate on sale of business gain in 2026?
There is no single tax rate on sale of business gain, because the IRS treats a sale as a sale of each asset and each slice of gain carries its own rate (IRS, Sale of a Business). Long-term capital gain is taxed at 0%, 15% or 20%, equipment recapture and inventory at ordinary rates up to 37%, and building depreciation at up to 25%.
| Type of gain | Where it comes from | Top federal rate, 2026 | Source |
|---|---|---|---|
| Long-term capital gain | Shares, LLC interests, goodwill held more than 1 year | 20% | IRS Topic 409 |
| Ordinary income | Section 1245 recapture, inventory, short-term gain | 37% | Rev. Proc. 2025-32 |
| Unrecaptured Section 1250 gain | Prior depreciation on a building the company owns | 25% | IRS Topic 409 |
| Taxable part of Section 1202 gain | QSBS gain not excluded | 28% | IRS Topic 409 |
| Net investment income tax | Passive owner’s gain, or C corporation stock gain | 3.8% on top | IRS Topic 559 |
| C corporation income tax | Gain inside a C corporation on an asset sale | 21% flat | IRC Section 11(b) |
Which capital gains bracket will the sale land in?
The sale gain stacks on top of your ordinary income, and the bracket is set by total taxable income. Rev. Proc. 2025-32 sets the 2026 ceilings below, so a seven-figure gain lands mostly in the 20% band.
| Filing status (2026) | 0% rate up to | 15% rate up to | 37% ordinary rate above |
|---|---|---|---|
| Married filing jointly | $98,900 | $613,700 | $768,700 |
| Single | $49,450 | $545,500 | $640,600 |
Does the 3.8% NIIT apply when you sell your business?
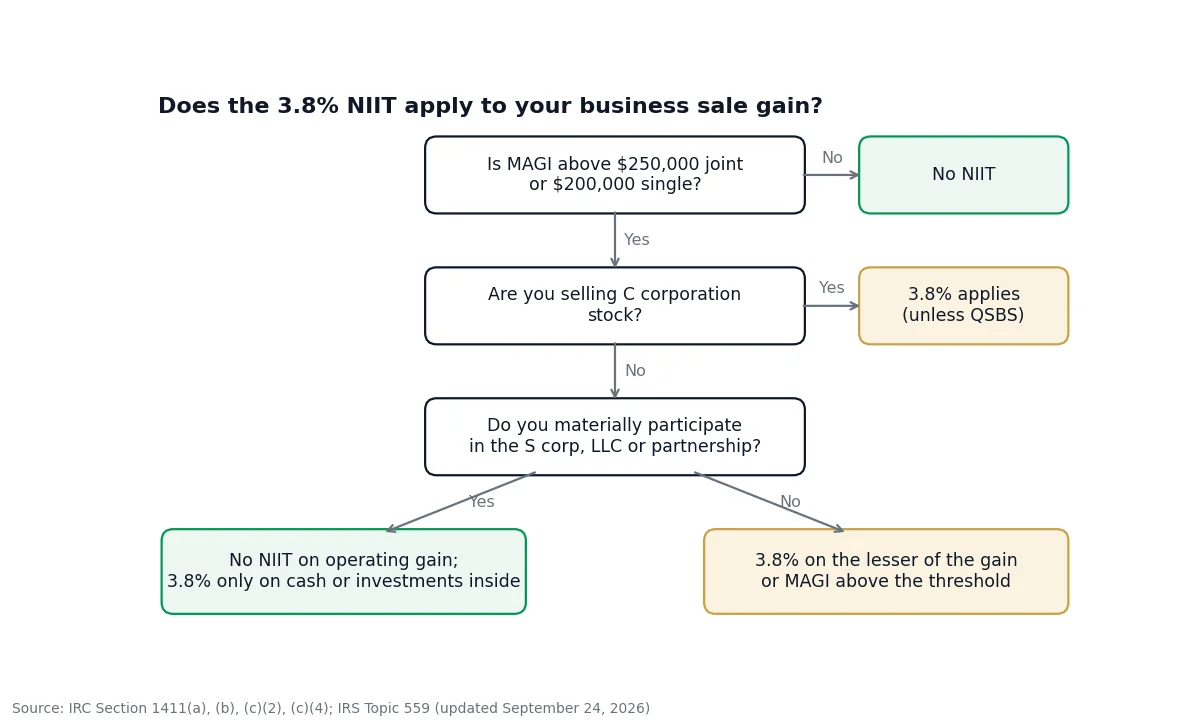
The 3.8% net investment income tax applies only above $250,000 of joint or $200,000 of single modified AGI, and only to gain that counts as investment income. Under IRC Section 1411(c), gain on property held in a trade or business is excluded unless the business is passive for you, and IRS Topic 559 says the NIIT does not apply to income from an active business.
For an S corporation, LLC or partnership interest, Section 1411(c)(4) looks through to the company’s assets, so an owner who materially participates usually owes no NIIT on operating gain. That look-through does not cover C corporation stock, so its gain is generally net investment income. The IRS NIIT questions and answers confirm the thresholds are not indexed for inflation.
| If your situation is | NIIT on the sale gain | Rule |
|---|---|---|
| MAGI at or below $250,000 joint or $200,000 single | None | Section 1411(b) |
| You materially participate in the S corporation, LLC or partnership | None on operating gain; 3.8% on cash or investments inside | Section 1411(c)(2), (c)(4) |
| You are a passive owner | 3.8% on the lesser of the gain or MAGI above the threshold | Section 1411(a)(1) |
| You sell C corporation stock | 3.8%, unless excluded as QSBS | Section 1411(c)(1)(A)(iii) |
How does an asset sale change the tax rate?
In an asset sale, the price is split across seven asset classes by the residual method, and buyer and seller each report the split on IRS Form 8594 for the year of sale. The class sets the rate: Class VII goodwill is capital gain, while Class V equipment is ordinary income up to the depreciation already claimed under IRC Section 1245(a)(1).
| Form 8594 class | What it holds | Character of seller’s gain | Top federal rate, 2026 |
|---|---|---|---|
| Class I to III | Cash, securities, accounts receivable | None on cash; ordinary on a cash-basis seller’s receivables | 37% |
| Class IV | Inventory | Ordinary income | 37% |
| Class V | Equipment, vehicles, buildings, land | Section 1245 recapture ordinary; building depreciation 25%; rest Section 1231 gain | 37%, 25% or 20% |
| Class VI | Customer lists, trademarks, other Section 197 intangibles | Usually capital or Section 1231 gain | 20% |
| Class VII | Goodwill and going concern value | Long-term capital gain | 20% |
Buyers want price in equipment, which they depreciate faster than the 15-year amortization IRC Section 197 sets for goodwill; sellers want it in Class VII. Settle the split in the letter of intent, as our guide to purchase price allocation and your taxes explains.
Why do C corporation owners pay tax twice?
A C corporation that sells its assets pays the 21% corporate rate on the gain, then the owner pays capital gains tax again when the cash is distributed in liquidation. A stock sale skips the corporate layer, which is why C corporation sellers push for one. S corporations, LLCs and partnerships pay no federal entity tax on the sale, and an S corporation can give a buyer asset treatment through an F reorganization; the full trade-off is in our asset sale vs stock sale guide.
How much tax will I pay on a $2 million or $5 million sale?
These three examples are illustrative, not client results. They use the 2026 federal tables in Rev. Proc. 2025-32 and the 2025 California schedule, the latest the California Franchise Tax Board has published, and ignore the Section 199A deduction, selling costs, entity-level state taxes and other income.
Example 1: $2,000,000 S corporation asset sale, Texas vs California
A married owner who works in the business sells all S corporation assets for $2,000,000: $300,000 to fully depreciated equipment (Section 1245 recapture, ordinary income) and $1,700,000 to Class VII goodwill with zero basis. Because the owner materially participates, NIIT is zero.
| Step (illustrative) | Arithmetic | Amount |
|---|---|---|
| Taxable income | $2,000,000 minus $32,200 standard deduction | $1,967,800 |
| Ordinary tax on $267,800 | $35,932 + 24% of ($267,800 minus $211,400) | $49,468 |
| Gain at 15% | ($613,700 minus $267,800) = $345,900 x 15% | $51,885 |
| Gain at 20% | ($1,700,000 minus $345,900) = $1,354,100 x 20% | $270,820 |
| Federal tax; net in Texas | $49,468 + $51,885 + $270,820; no Texas income tax | $372,173; net $1,627,827 (18.6%) |
| California tax | $144,439.65 + 12.3% of ($1,988,588 minus $1,485,906) after the $11,412 deduction | $206,270 |
| California 1% tax over $1,000,000 | 1% of ($1,988,588 minus $1,000,000) | $9,886 |
| Net in California | $1,627,827 minus $216,155 | $1,411,672 (29.4%) |
A passive owner would add NIIT of 3.8% on the lesser of the $2,000,000 gain or the $1,750,000 of MAGI above $250,000: $66,500. Try your own inputs in our sell my business calculator.
Example 2: $5,000,000 C corporation, stock sale vs asset sale
Stock and inside asset basis are both $500,000, and the owner’s other income already exceeds $613,700, so all gain is taxed at 20% plus 3.8% NIIT. Federal tax only.
| Step (illustrative) | Stock sale | Asset sale, then liquidation |
|---|---|---|
| Corporate tax at 21% | None | $4,500,000 x 21% = $945,000 |
| Owner’s gain | $4,500,000 | ($5,000,000 minus $945,000) minus $500,000 = $3,555,000 |
| Owner’s tax at 23.8% | $1,071,000 | $846,090 |
| Total federal tax | $1,071,000 (21.4%) | $1,791,090 (35.8%) |
| Net to owner | $3,929,000 | $3,208,910 |
The asset sale costs this owner $720,090, a gap the buyer would need to cover in price.
Example 3: the same $5,000,000 stock sale with QSBS
If the owner bought the shares at original issue in 2018, held them more than 5 years, the company runs an active non-service business and had no more than $50,000,000 of gross assets at issue, Section 1202 excludes the whole $4,500,000 gain, under the $10,000,000 cap. Federal tax is zero and the owner keeps $5,000,000.
| Illustrative scenario | Price | Tax | Tax as % of price |
|---|---|---|---|
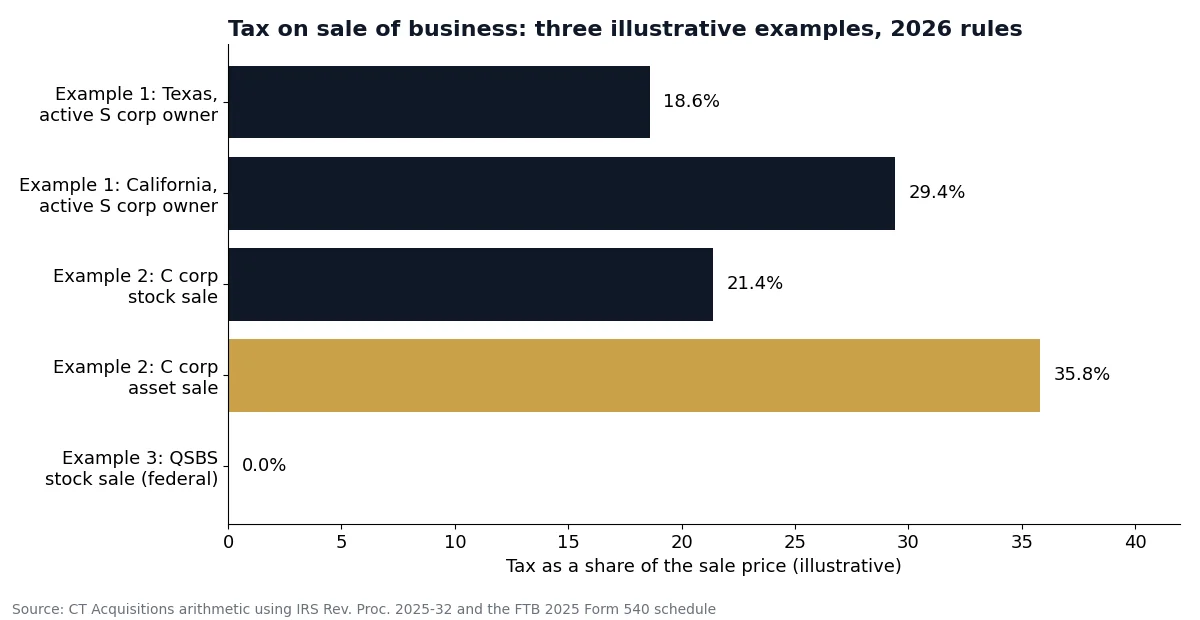
| Example 1, Texas, active S corporation owner | $2,000,000 | $372,173 | 18.6% |
| Example 1, California, active S corporation owner | $2,000,000 | $588,328 | 29.4% |
| Example 2, C corporation stock sale | $5,000,000 | $1,071,000 | 21.4% |
| Example 2, C corporation asset sale | $5,000,000 | $1,791,090 | 35.8% |
| Example 3, QSBS stock sale (federal) | $5,000,000 | Zero | 0% |
Can an installment sale lower the tax?
An installment sale defers tax because gain is reported as payments arrive, on Form 6252 (IRS Publication 537). Recapture is still taxed in the year of sale, and IRC Section 453A charges interest on deferred tax when the price exceeds $150,000 and your notes outstanding at year end exceed $5,000,000.
- Report the $300,000 of Example 1 recapture in year one on Form 4797, Part III.
- Gross profit is the $2,000,000 price minus zero basis plus the $300,000 recapture, or $1,700,000; divided by the $2,000,000 contract price, that is 85%.
- With $1,000,000 at closing and a note paid at $200,000 a year for 5 years, year one reports $850,000 of gain and each later year $170,000, plus interest taxed as ordinary income.
Spreading gain over 6 years keeps more of it in the 15% band, but you carry the buyer’s credit risk. Our installment sale tax treatment guide covers security and default.
Does QSBS make the sale tax free?
Section 1202 can exclude gain on C corporation stock bought at original issue, but Public Law 119-21, signed July 4, 2025, split the rules by date. Newer stock gets a 3, 4 and 5 year schedule, a $15,000,000 cap and a $75,000,000 gross-asset test; shares acquired on or before July 4, 2025 keep the old rules.
| QSBS rule | Acquired on or before July 4, 2025 | Acquired after July 4, 2025 | Source |
|---|---|---|---|
| Holding period | More than 5 years | 3 years (50%), 4 years (75%), 5 years (100%) | Section 70431(a) |
| Per-issuer cap | $10,000,000 or 10 times basis | $15,000,000 or 10 times basis, indexed after 2026 | Section 70431(b) |
| Gross assets at issue | $50,000,000 or less | $75,000,000 or less (stock issued after July 4, 2025) | Section 70431(c) |
Health, law, engineering, architecture, accounting and similar service companies are excluded under Section 1202(e)(3), and S corporation stock does not qualify. State conformity differs; see our state QSBS conformity matrix. A sale to an ESOP under IRC Section 1042 can defer gain if the ESOP owns at least 30% afterwards, you held the shares 3 years, and you buy replacement securities from 3 months before to 12 months after the sale.
How much state tax will you pay on a business sale?
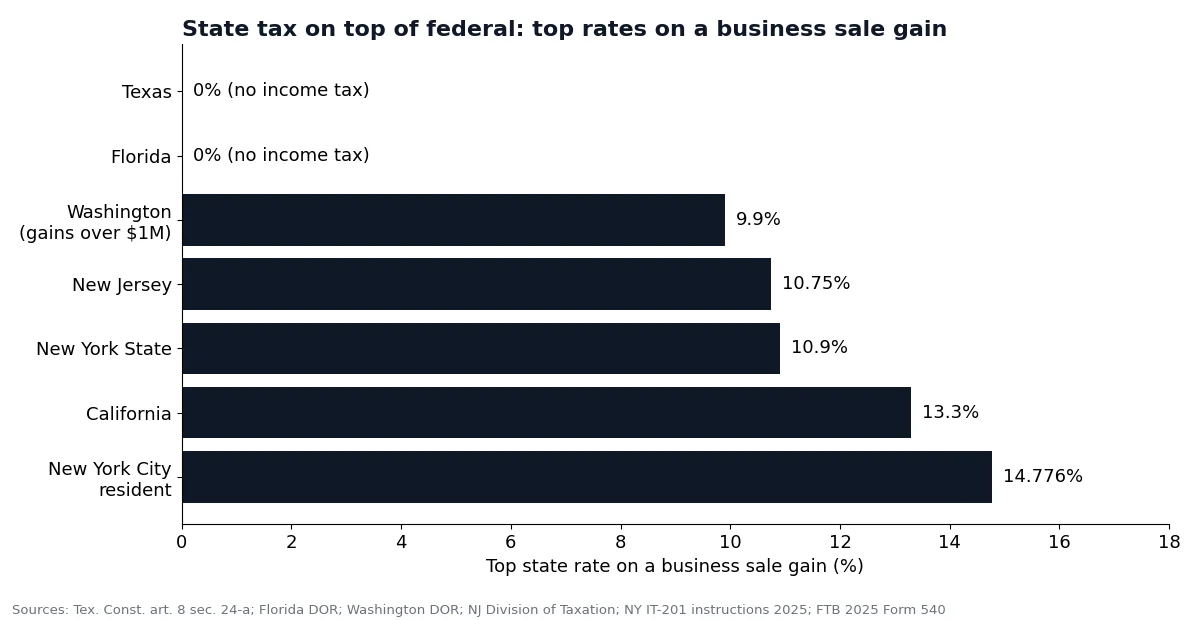
State tax follows where you live when the gain is recognized, and most states tax capital gains as ordinary income. California says it has no special rate for long-term gains, so a large sale reaches 12.3% plus a 1% tax on taxable income above $1,000,000. Texas and Florida have no personal income tax.
| State | Top rate on the gain | Note | Source |
|---|---|---|---|
| Texas | 0% | Constitution bars a personal income tax | Tex. Const. art. 8, sec. 24-a |
| Florida | 0% | No personal income tax | Florida DOR |
| Washington | 7%; 9.9% above $1 million | 2025 deduction $278,000; family-business deduction | Washington DOR |
| New Jersey | 10.75% | Top bracket | NJ Division of Taxation |
| New York | 10.9% | Above $25,000,000; 10.3% from $5,000,000 | NY IT-201 instructions (2025) |
| New York City resident | 14.776% (10.9% state + 3.876% city) | City rate above $90,000 joint | NY IT-201 instructions (2025) |
| California | 13.3% | 12.3% plus 1% Behavioral Health Services Tax | FTB 2025 Form 540 booklet |
Washington’s deduction covers a family-owned business with gross revenue of $10,000,000 or less in the prior 12 months whose owner materially participated for 5 of the last 10 years (RCW 82.87.070). Our 2026 state tax report for business sales covers residency moves and source rules.
Considering selling your business?
Structure is set in the letter of intent, so the tax math belongs before you sign one. Start with a 30-minute confidential call about your entity, your state and the structures buyers are offering. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells.
Which structure fits your situation?
Find the row that matches your company and take its governing rule to your CPA.
| If your situation is | Then | Governing rule |
|---|---|---|
| C corporation shares held more than 5 years, issued when gross assets were $50,000,000 or less | Test QSBS before agreeing to an asset sale | IRC Section 1202 |
| C corporation without QSBS, buyer asks for an asset deal | Price the gap: $720,090 on $5,000,000 in Example 2 | IRC Section 11(b), Form 8594 |
| S corporation or LLC and you work in the business | Expect no NIIT on operating gain; push price into Class VII goodwill | Section 1411(c)(4), Form 8594 |
| Price above $150,000 with a seller note | Model Form 6252 and the $5,000,000 Section 453A test | Publication 537 |
| Washington resident, revenue of $10,000,000 or less | Check the family-owned business deduction | RCW 82.87.070 |
Most of these levers must be set 2 or more years before a buyer’s letter of intent, which is the work our exit planning page lays out.
What do other guides get wrong about taxes on selling a business?
Several top-ranking guides repeat figures the primary sources no longer support (checked November 2026).
| What several guides say | What the primary source says |
|---|---|
| Every seller pays 23.8% (20% plus 3.8% NIIT) | Active owners of S corporations, LLCs and partnerships generally owe no NIIT on operating gain (IRC Section 1411(c), IRS Topic 559) |
| Washington has no tax on a business sale | 7%, and 9.9% above $1 million from tax year 2025 (Washington DOR) |
| QSBS requires 5 years and caps at $10,000,000 | True only for stock acquired on or before July 4, 2025 (P.L. 119-21, Section 70431) |
| Installment sales defer all of the tax | Recapture is taxed in the year of sale (IRS Publication 537) |
How we compiled this
We compiled this page in November 2026 from 23 primary documents: 7 IRS documents, the text of Public Law 119-21, 7 U.S. Code sections and 8 state constitutions, statutes and revenue publications. We excluded forum posts and blog summaries as sources for rates; the examples are our own arithmetic.
Frequently asked questions
How much tax will you pay if you sell your business?
For tax year 2026, most gain on a business held more than one year is taxed at 15% or 20% federal, with equipment recapture at ordinary rates up to 37%. Passive owners and C corporation shareholders add 3.8% NIIT above $250,000 of joint MAGI. State tax adds 0% in Texas and Florida and up to 13.3% in California.
Is capital gains tax 20% or 24%?
Both figures circulate because the top long-term capital gains rate is 20% and the 3.8% net investment income tax can sit on top, making 23.8%. The NIIT applies only above $250,000 of joint or $200,000 of single MAGI, and IRS Topic 559 says it does not apply to income from an active business, so many owner-operators pay 20%.
How much capital gains tax will I pay on $300,000?
For a married couple with no other income in 2026, $300,000 of long-term gain becomes $267,800 of taxable income after the $32,200 standard deduction. The first $98,900 is taxed at 0% and the remaining $168,900 at 15%, or $25,335 of federal tax. If the gain were passive, NIIT would add 3.8% of the $50,000 above $250,000, or $1,900.
How do I avoid capital gains tax on selling a business?
You can rarely avoid it entirely, but four rules cut it legally. QSBS under Section 1202 can exclude up to $10,000,000 or $15,000,000 of gain on qualifying C corporation stock. A Section 1042 ESOP sale defers it. An installment sale on Form 6252 spreads it. Living in Texas or Florida at the time of sale removes state income tax.
Sources
- IRS: Rev. Proc. 2025-32; Topics 409 and 559; NIIT questions and answers; Sale of a Business; Form 8594 instructions; Publication 537 (2025)
- Public Law 119-21, Section 70431 (July 4, 2025); 26 U.S.C. sections 11, 197, 453A, 1042, 1202, 1245 and 1411
- California FTB 2025 Form 540 booklet; NY 2025 IT-201 instructions; NJ Division of Taxation; Washington DOR; RCW 82.87.070; Tex. Const. art. 8, sec. 24-a; Florida DOR. All accessed November 2026.
About the Author
Christoph Totter is the founder of CT Acquisitions, an M&A advisory firm that helps owners make the most of their exit, headquartered in Sheridan, Wyoming. We work directly with 500+ buyers, search funders, family offices, lower middle-market PE, and strategic consolidators, including direct mandates with the largest home services consolidators that other intermediaries can’t access. Our fee is success only: nothing upfront, and you pay nothing unless the business sells. Connect on LinkedIn · Get in touch
Want a Specific Read on Your Business?
30 minutes, confidential, no contract, no cost. You leave with a view of your local buyer market and a likely valuation range.
