
IBP Acquires Old Dominion Group: What 9.3x Means for Installers
On November 12, 2026, IBP acquired Old Dominion Group, a Virginia mechanical insulation and firestopping installer, for a $698 million enterprise value: 9.3x adjusted EBITDA including synergies, to build a commercial and industrial platform.
By Christoph Totter, Founder of CT Acquisitions · Last reviewed: November 2026
Key takeaways
- Installed Building Products (NYSE: IBP) signed and closed on the same day: a $725 million base price, or a $698 million enterprise value after $27 million of transaction bonuses, per its November 12, 2026 Form 8-K.
- 9.3x is the friendliest reading: the price is 10.3x the $67.9 million of adjusted EBITDA before synergies and 11.9x the $58.9 million of GAAP EBITDA, per the 8-K press release exhibit (CT arithmetic).
- Size drives the gap: GF Data put PE-backed specialty trade deals at 5.7x EBITDA at $10 million to $25 million of enterprise value and 8.2x at $100 million to $500 million (April 2025).
- IBP paid about 1.5x to 1.7x revenue for two small mechanical insulators in 2026, Thermo-Tech ($19.5 million) and Diamond Energy ($20.9 million), close to the 1.9x it paid for Old Dominion Group, per its Q3 2026 Form 10-Q (CT arithmetic).
- IBP says Old Dominion Group will pursue more bolt-ons in the fragmented mechanical and industrial insulation market: Mid-Atlantic and Southeast insulators now face a buyer with a written mandate.
What did IBP buy, and on what terms?
IBP bought Old Dominion Group (ODG), a 45-year-old mechanical and industrial installer of insulation, firestopping and electric heat trace. ODG earned about $370 million of revenue and $68 million of adjusted EBITDA in the 12 months to September 30, 2026. The deal signed and closed on November 12, 2026, with 60% cash and 40% IBP stock.
ODG was founded in 1981 as Old Dominion Insulation by Roddy Davoud and is led by CEO Jeff Davoud, in the role since 2012, from Midlothian, Virginia, with about 1,700 employees in 18 offices, per Richmond BizSense (November 17, 2026). Jeff Davoud told the paper IBP “sought us out”: the buyer called first. He stays as CEO, leads IBP’s combined mechanical and industrial installation business, and ODG keeps its regional brands.
| Term | Figure | Source |
|---|---|---|
| Base purchase price | $725.0 million | IBP 8-K, Item 1.01 |
| Enterprise value (net of bonuses and management incentive funding) | $698.0 million | IBP 8-K, Item 1.01 |
| LTM revenue to Sept 30, 2026 | about $370 million | IBP 8-K exhibit 99.1 |
| LTM adjusted EBITDA (margin) | $67.9 million (18.4%) | IBP 8-K exhibit 99.1 |
| Expected run-rate cost synergies | $6 million to $8 million within 24 months | IBP 8-K exhibit 99.1 |
| Stock consideration | 1,381,731 IBP shares at $217.19 (10-day VWAP), about $300.1 million | IBP 8-K, Item 1.01 (value: CT arithmetic) |
| Escrows | $3.0 million indemnity, $10.0 million adjustment | IBP 8-K, Item 1.01 |
| Risk cover | Buy-side representations and warranties insurance | IBP 8-K, Item 1.01 |
| Advisors | Goldman Sachs, BofA Securities, Calfee, Halter & Griswold (IBP); William Blair, Williams Mullen (ODG) | IBP 8-K exhibit 99.1 |
It is the only one of 21 trades acquisitions we logged from November 2 to 19, 2026 with a disclosed price; see our November 2026 home services acquisitions roundup. Four days later IBP also bought Take Pride Insulation of Belgrade, Montana, with over $6 million of revenue, per its November 16, 2026 release.
How should an owner read the 9.3x multiple?
Read 9.3x as the buyer’s number. IBP divided $698 million by $74.9 million: ODG’s $67.9 million of adjusted EBITDA plus $7.0 million of synergies IBP expects to create. On ODG’s own adjusted earnings the price is 10.3x, on GAAP EBITDA 11.9x, and on the $725 million base price 10.7x (CT arithmetic from the 8-K exhibit).
| Price basis | Earnings basis | Multiple | What it tells you |
|---|---|---|---|
| $698M enterprise value | $74.9M ($67.9M adjusted EBITDA plus $7.0M synergies) | 9.3x | The headline IBP gave investors |
| $698M enterprise value | $67.9M adjusted EBITDA | 10.3x | What ODG’s earnings alone fetched |
| $725M base purchase price | $67.9M adjusted EBITDA | 10.7x | Includes $27M of bonuses and management incentive funding |
| $698M enterprise value | $58.9M GAAP EBITDA | 11.9x | Before the $8.0M share-based pay and $1.0M one-time add-backs |
Two lessons follow for a smaller owner. First, the add-backs mattered: $8.0 million of share-based compensation and $1.0 million of one-time costs lifted EBITDA from $58.9 million to $67.9 million, and every $1 million of accepted add-back was worth about $10.3 million at this multiple. Our guide to adjusted EBITDA add-backs buyers accept covers which ones survive diligence.
Second, at 10.3x standalone ODG was paid for part of the $6 million to $8 million IBP expects to save on procurement and administration. Sellers capture synergies only when two buyers can create them, which is why rival TopBuild matters.
Structure shaped the take-home. About $300.1 million arrived as IBP stock, and the parties intend the merger to qualify as a reorganization under Internal Revenue Code §368(a), which generally lets stock received in a qualifying reorganization be taxed later. $13.0 million sat in escrow, and up to 50 key non-executive employees received growth awards with a $180 million target value, vesting over three- and five-year cycles. That works like an earnout for the managers. Ask your CPA and M&A attorney whether a stock deal fits your tax basis and holding plans.
Why does size change the multiple?
Buyers pay more per dollar of EBITDA for larger trade companies: the earnings carry less risk. In GF Data’s April 2025 figures, PE-backed specialty trade contractors (NAICS 238) traded at 5.7x EBITDA at $10 million to $25 million of enterprise value, 6.3x on average and 8.2x at $100 million to $500 million. Owner-run construction businesses sold on BizBuySell from 2017 to 2025 averaged 2.54x seller’s discretionary earnings.
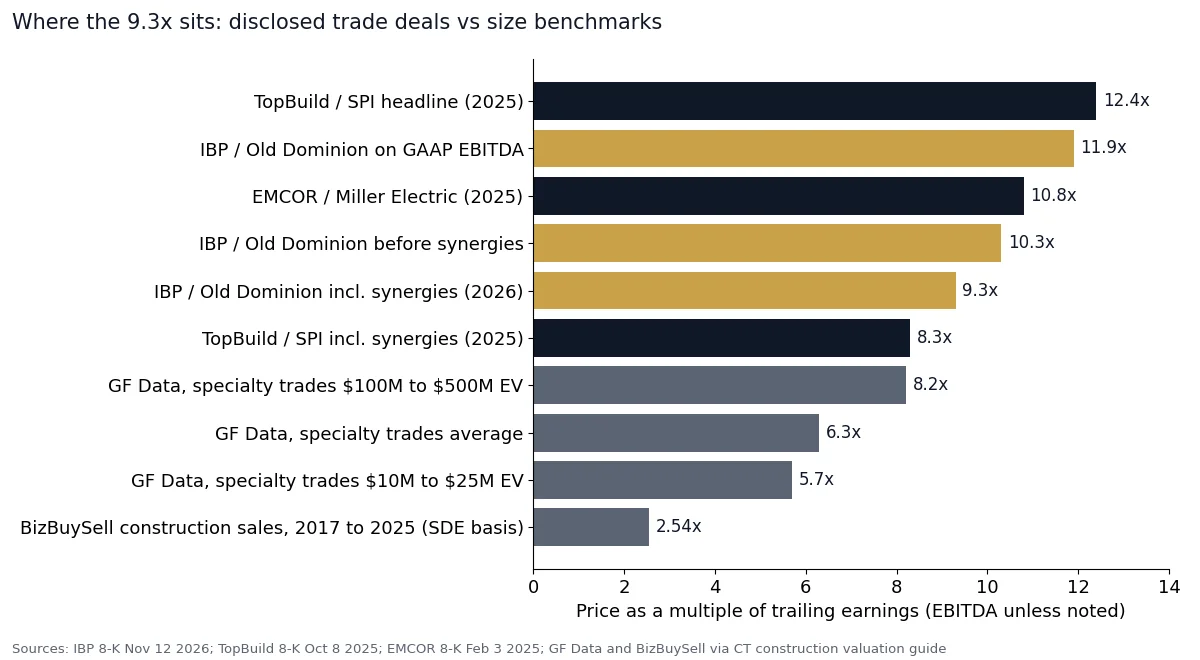
| Deal or benchmark | Size | Multiple | Source |
|---|---|---|---|
| BizBuySell construction and building sales, 2017 to 2025 | Main Street | 2.54x SDE | CT construction valuation guide |
| GF Data, specialty trades, $10M to $25M EV | Lower middle market | 5.7x EBITDA | GF Data, April 2025, via CT guide |
| GF Data, specialty trades, average | All tiers | 6.3x EBITDA | GF Data, April 2025, via CT guide |
| GF Data, specialty trades, $100M to $500M EV | Middle market | 8.2x EBITDA | GF Data, April 2025, via CT guide |
| TopBuild / Specialty Products and Insulation (SPI), Oct 2025 | about $700M revenue, $75M EBITDA | 12.4x headline, 8.3x with $35M to $40M synergies | TopBuild 8-K, Oct 8, 2025 |
| IBP / Old Dominion Group, Nov 2026 | about $370M revenue, $67.9M adjusted EBITDA | 10.3x standalone, 9.3x with synergies | IBP 8-K, Nov 12, 2026 |
| EMCOR / Miller Electric, Feb 2025 | about $805M revenue, $80M adjusted EBITDA | 10.8x ($865M cash, CT arithmetic) | EMCOR 8-K, Feb 3, 2025 |
Five ODG features explain most of the gap between 5.7x and 10.3x; a smaller installer can measure each one:
- Key-person risk. ODG has been led by someone other than its founder since 2012 and gave about 75 leaders equity. A $10 million shop where the owner bids every job carries more risk.
- Spread. 18 offices in at least 6 states and end markets IBP lists as healthcare, education, manufacturing, industrial facilities and data centers. A shop with one general contractor at 40% of revenue lacks that spread.
- Margin. An 18.4% adjusted EBITDA margin on $370 million of revenue leaves room for a buyer’s overhead.
- Platform status. IBP calls ODG a platform for further bolt-ons; see platform acquisitions versus add-ons for why platforms price higher.
- Buyer currency. A public buyer paying 40% in stock can offer a higher headline price, because the seller shares the future risk.
Our mechanical contractor M&A multiples report shows the same size pattern in Comfort Systems USA, EMCOR and Limbach deals.
What would a smaller insulation contractor be worth? A worked example
An illustrative mechanical insulation installer with $12 million of revenue and a 15% EBITDA margin, earning $1.8 million, lands between about $10.3 million and $20.4 million depending on the buyer’s lens. Benchmark multiples give the low end; a strategic buyer pricing on revenue, as IBP’s 2026 filings imply, gives the high end. These inputs are assumptions, not this deal’s price.
| Lens (illustrative) | Multiple applied | Implied value | Implied revenue multiple |
|---|---|---|---|
| GF Data specialty trades, $10M to $25M EV tier | 5.7x of $1.8M | $10.26M | 0.86x |
| GF Data specialty trades average | 6.3x of $1.8M | $11.34M | 0.95x |
| ODG standalone multiple, applied without ODG’s scale | 10.3x of $1.8M | $18.54M | 1.55x |
| Revenue multiple near IBP’s Diamond Energy price | 1.7x of $12M revenue | $20.4M (11.3x EBITDA) | 1.7x |
Why could a strategic pay the top row? Suppose an illustrative buyer saves 3% of revenue, $360,000 a year, on materials and back office. At an $11.34 million price, its effective multiple falls from 6.3x to 5.25x on $2.16 million of combined earnings. That is IBP’s 9.3x logic at small scale. At Diamond Energy’s 9.1% seller obligations ($1.9 million of $20.9 million), about $1.86 million of a $20.4 million price would be deferred.
A caution: IBP does not disclose EBITDA for its small deals. At ODG’s 18.4% margin, 1.5x and 1.74x revenue equal about 8.2x and 9.5x EBITDA (illustrative); at lower margins the implied multiple climbs, so treat revenue multiples as an upper reference.
Who is IBP and what has it bought?
IBP is a Columbus, Ohio installer of insulation and complementary products with over 250 branches in all 48 continental states. It buys several small installers each year: nine business combinations and four bolt-ons in the nine months to September 30, 2026. The 2026 pattern is mechanical insulation: Thermo-Tech in Wisconsin, Diamond Energy in Minnesota, then ODG.
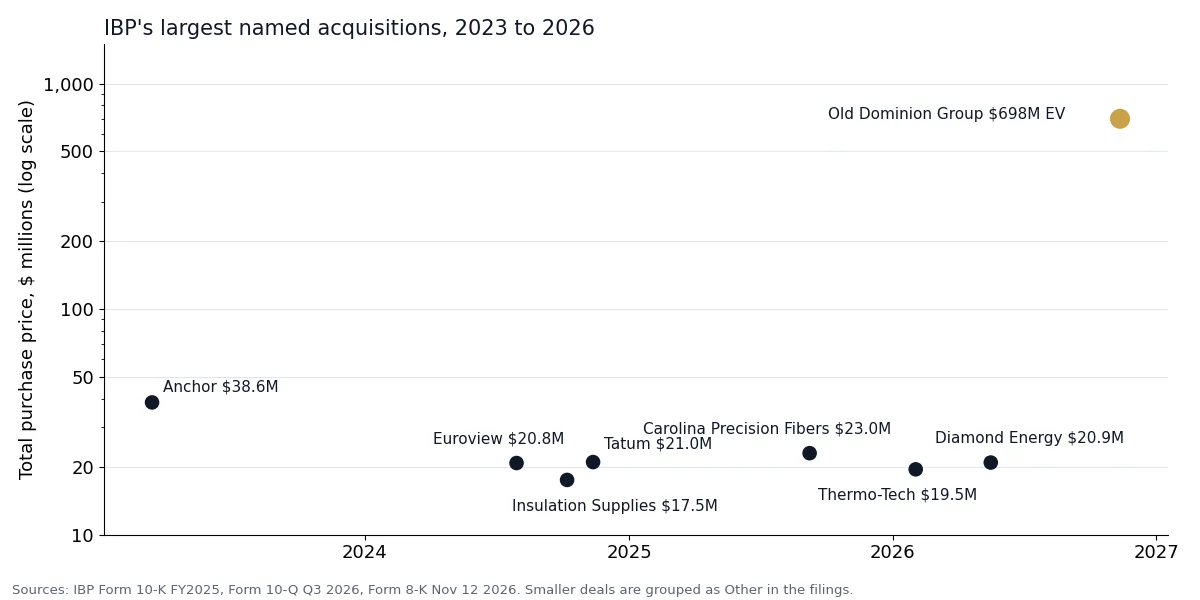
| Date | Target (base) | Business | Revenue at deal | Total price | Price / revenue |
|---|---|---|---|---|---|
| Mar 12, 2023 | Anchor | Share purchase | Not stated | $38.6M | n/a |
| Jul 29, 2024 | Euroview | Asset purchase | Not stated | $20.8M | n/a |
| Oct 7, 2024 | Insulation Supplies | Asset purchase | Not stated | $17.5M | n/a |
| Nov 12, 2024 | Tatum | Share purchase | Not stated | $21.0M | n/a |
| Sep 8, 2025 | Carolina Precision Fibers (Ronda, NC) | Cellulose insulation maker | over $20M | $23.0M | 1.15x or less |
| Feb 2, 2026 | Thermo-Tech (Watertown, WI) | Commercial and industrial mechanical insulation | about $13M | $19.5M | 1.5x |
| May 17, 2026 | Diamond Energy Systems (St. Joseph, MN) | Mechanical insulation, mostly retrofit | about $12M | $20.9M | 1.74x |
| Nov 12, 2026 | Old Dominion Group (Midlothian, VA) | Mechanical and industrial insulation, firestopping | about $370M | $698M EV | 1.89x |
| Nov 16, 2026 | Take Pride Insulation (Belgrade, MT) | Residential and commercial insulation | over $6M | Not disclosed | n/a |
Prices come from the business combination tables in IBP’s 2025 Form 10-K and Q3 2026 Form 10-Q; revenue comes from IBP’s releases for Carolina Precision Fibers, Thermo-Tech and Diamond Energy. IBP had acquired about $444 million of annual revenue in 2026 by November 16, so ODG is about 83% of it.
IBP is public with no private equity sponsor, so there is no fund-life resale. It added $250 million to its term loan, announced October 19, 2026, before the deal. In its 2026 deals to September, $7.1 million of the $70.3 million total price (10.1%) was seller obligations, not cash at closing.
What does Old Dominion Group add to IBP’s map?
ODG moves IBP’s mechanical insulation work from the Upper Midwest to the Mid-Atlantic, the Carolinas, Tennessee and Texas. Before the deal IBP had about $50 million of commercial mechanical insulation revenue; with ODG it has about $420 million, and commercial work rises from about 20% to 28% of IBP’s revenue, per the 8-K exhibit.
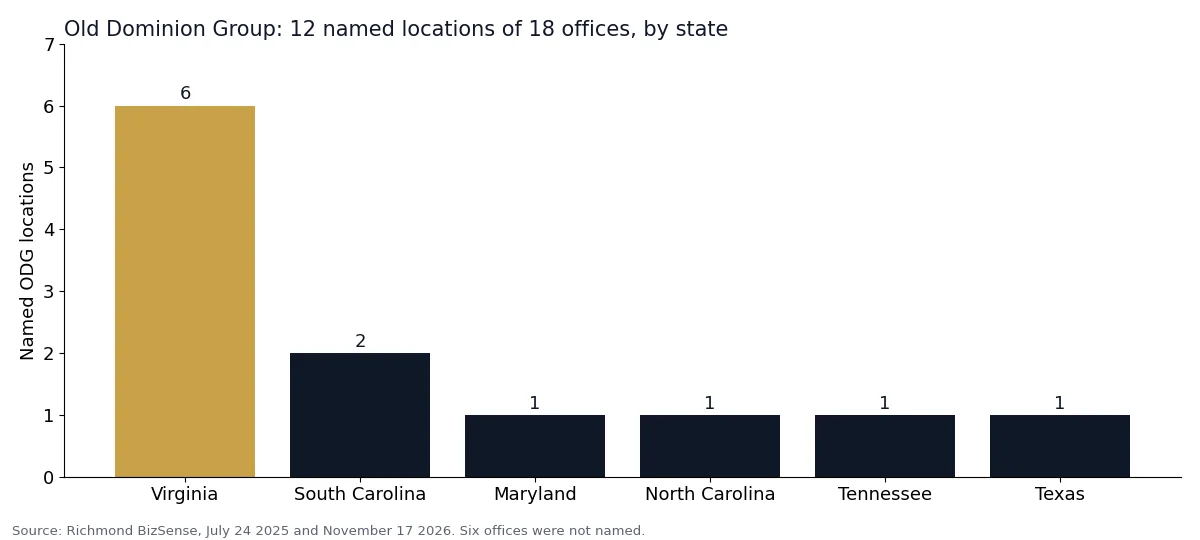
| State | Named ODG locations | NAICS 238310 establishments, 2023 | Employees, 2023 | Establishments under 20 employees |
|---|---|---|---|---|
| Virginia | 6 (Midlothian, Chesapeake, Leesburg, Mount Crawford, Hollins, Virginia Beach) | 533 | 6,397 | 446 |
| South Carolina | 2 (Charleston, Greenville) | 220 | 1,947 | 190 |
| Maryland | 1 (Baltimore) | 331 | 6,144 | 267 |
| North Carolina | 1 (Charlotte) | 602 | 5,698 | 530 |
| Tennessee | 1 (Nashville) | 287 | 3,555 | 238 |
| Texas | 1 (Houston) | 1,206 | 20,069 | 1,020 |
| United States | 18 offices in total | 20,760 | 250,758 | 18,095 |
Locations come from Richmond BizSense (July 2025 and November 2026). Counts are from the Census Bureau’s 2023 County Business Patterns for NAICS 238310, Drywall and Insulation Contractors. Nationally 87.2% of those establishments have fewer than 20 employees, and only 426 have 100 to 999.
That undercounts mechanical insulators. The BLS Occupational Outlook Handbook shows 67% of the 26,700 mechanical insulation worker jobs in 2025 sat in building equipment contractors, only 13% in drywall and insulation contractors. Their median wage was $58,340 in May 2025, against $49,120 for floor, ceiling and wall insulators. Many of the new platform’s targets sit under HVAC or mechanical codes.
Licensing is a diligence item in Virginia. Va. Code §54.1-1100 requires a Class A license for single contracts of $150,000 or more or $1 million of work in 12 months, and the insulation specialty in 18VAC50-22-30 “does not include the insulation of mechanical equipment and ancillary lines and piping.” Confirm with Virginia’s Department of Professional and Occupational Regulation which classification covers your pipe and duct work before a buyer asks.
What this means for insulation and mechanical contractors in the Mid-Atlantic and Southeast
IBP now has a funded platform, a CEO who told Richmond BizSense he wants to grow “down the East Coast, and hopefully across the country,” and a written bolt-on plan. Commercial insulators with $5 million to $50 million of revenue near ODG’s states are the next targets, and the window is widest during IBP’s 24-month synergy build.
Our reading of the map, not IBP guidance: the gaps are mechanical insulators in Georgia, Florida, Pennsylvania, Ohio and the Northeast, firestopping crews near data center clusters, and heat trace work. TopBuild, which bought SPI and reported 45 acquisitions since its 2015 spin-off as of October 2025, competes for the same sellers. Our guide to strategic versus financial buyers compares their offers.
Prepare these before taking a buyer’s call:
- Three years of revenue split by end market (healthcare, education, industrial, data center, residential) and by new construction versus maintenance; SPI’s 55% recurring maintenance and repair share was a selling point for TopBuild.
- Monthly EBITDA with each add-back documented, plus annual material spend by product, since procurement drives IBP’s synergy case.
- License numbers by state and classification, asbestos credentials and safety records.
- Top 10 customers with revenue share, and assignability of open contracts and bonds.
- A second-tier leadership chart: who runs estimating, field operations and safety without you.
The risks sit in the paperwork: stock priced on a 10-day average, escrows (ODG: $13.0 million, 1.8% of the base price), and performance awards measured over three and five years. Our guides to escrow holdbacks and indemnification and how earnouts work explain what to negotiate.
| If your company is… | Likely buyer lens | Then do this |
|---|---|---|
| If a commercial or mechanical insulator with $5M to $50M revenue near ODG’s 18 offices | Add-on for IBP’s new platform; TopBuild and PE also active | Prepare end-market and material-spend data now; IBP’s 1.5x to 1.74x revenue prints need strong margins |
| If over $10M of EBITDA with several offices and second-tier managers | Possible platform or larger add-on | Run a competitive process; ODG’s 10.3x came at $67.9M of EBITDA, so match expectations to your tier |
| If residential-heavy (new homes) with under $10M revenue | Classic IBP add-on, like Take Pride Insulation | Benchmark against GF Data 5.7x; expect about 10% of price as seller obligations |
| If owner-run, under $1M of earnings | Main Street buyers, SDE basis | Build a management layer first; the 2.54x SDE average is the realistic anchor today |
| If offered 40% or more in buyer stock | Public strategic | Ask about §368 reorganization treatment, lock-ups and resale registration (IBP agreed to file within 30 days) |
How we compiled this
We read 9 SEC documents from IBP, TopBuild and EMCOR, Census 2023 County Business Patterns files, the BLS handbook and the Virginia Code in November 2026. Locations come from Richmond BizSense; GF Data and BizBuySell figures come from CT’s construction valuation guide, not the original reports.
We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells. If IBP, TopBuild or a PE platform has called, book a confidential call before you answer.
Frequently asked questions
Who owns Old Dominion Group now?
Installed Building Products, Inc. (NYSE: IBP) owns Old Dominion Group since November 12, 2026. ODG merged into IBP Mechanical & Industrial Installation, LLC, a wholly owned IBP subsidiary. Former shareholders received about 60% cash and 1,381,731 IBP shares, and CEO Jeff Davoud stays to lead IBP’s mechanical and industrial installation business under ODG’s regional brands.
How much did IBP pay for Old Dominion Group?
IBP paid a $725 million base purchase price, or a $698 million enterprise value after $27 million of transaction bonuses and management incentive funding, per its November 12, 2026 Form 8-K. That equals 9.3x LTM adjusted EBITDA including $7.0 million of expected synergies, or 10.3x the $67.9 million of adjusted EBITDA alone.
How much is a mechanical insulation company worth?
Size moves the number most. GF Data put PE-backed specialty trade deals at 5.7x EBITDA for $10 million to $25 million of enterprise value and 8.2x at $100 million to $500 million (April 2025). IBP paid 1.5x to 1.74x revenue for two mechanical insulators with $12 million to $13 million of revenue in 2026.
Is IBP still buying insulation companies?
Yes. IBP closed Take Pride Insulation in Montana on November 16, 2026, four days after ODG, and said it had acquired about $444 million of annual revenue in 2026. Its 8-K says ODG gives it a platform for more bolt-on acquisitions in the fragmented mechanical and industrial insulation market.
Sources
- Installed Building Products, Form 8-K and exhibit 99.1 on Old Dominion Group, November 12, 2026.
- IBP, Form 10-Q for Q3 2026 (November 5, 2026) and Form 10-K for 2025 (February 26, 2026), business combinations notes.
- IBP releases: Take Pride Insulation (November 16, 2026), Diamond Energy Systems (May 19, 2026), Thermo-Tech, Biomax and CKV (February 2, 2026), Carolina Precision Fibers (September 8, 2025).
- TopBuild, SPI acquisition release (October 8, 2025) and EMCOR, Miller Electric release (February 3, 2025), SEC exhibits 99.1.
- William Blair, transaction announcement, November 13, 2026; Richmond BizSense, November 17, 2026 and July 24, 2025.
- U.S. Census Bureau, 2023 County Business Patterns; BLS Occupational Outlook Handbook, Insulation Workers (May 2025 wages).
- Va. Code §54.1-1100, 18VAC50-22-30 and 26 U.S.C. §368.
- All sources accessed November 2026.