
Core & Main Acquires Southwest Stormwater, Gajeske and KTI
On November 10, 2026, Core & Main said it had acquired Southwest Stormwater Solutions in Phoenix, Gajeske in Houston and KTI in Toronto: over $250 million of combined revenue in stormwater vaults, fusible HDPE pipe and smart water meters.
By Christoph Totter, Founder of CT Acquisitions · Last reviewed: November 2026
Key takeaways
- Core & Main closed three acquisitions between September and November 2026 that add 16 locations and over $250 million of combined annual revenue (Form 8-K, Nov 10, 2026).
- Each target fills a line Core & Main targets in its 10-K: storm drainage, fusible HDPE (Gajeske, 8 locations) and smart metering (KTI, 7 locations).
- No price, multiple, advisor or management retention term was disclosed for any of the three deals.
- Core & Main spent $769 million on 10 acquisitions in fiscal 2024 that added more than $600 million of annual sales: about 1.28 times sales at most (Q4 fiscal 2024 presentation).
- 16 of the 20 deals listed in its latest 10-K were asset purchases, and its fiscal 2025 deals carry an earnout of up to $18 million tied to two years of Adjusted EBITDA (10-Q, Aug 2, 2026).
What did Core & Main buy, and when did each deal close?
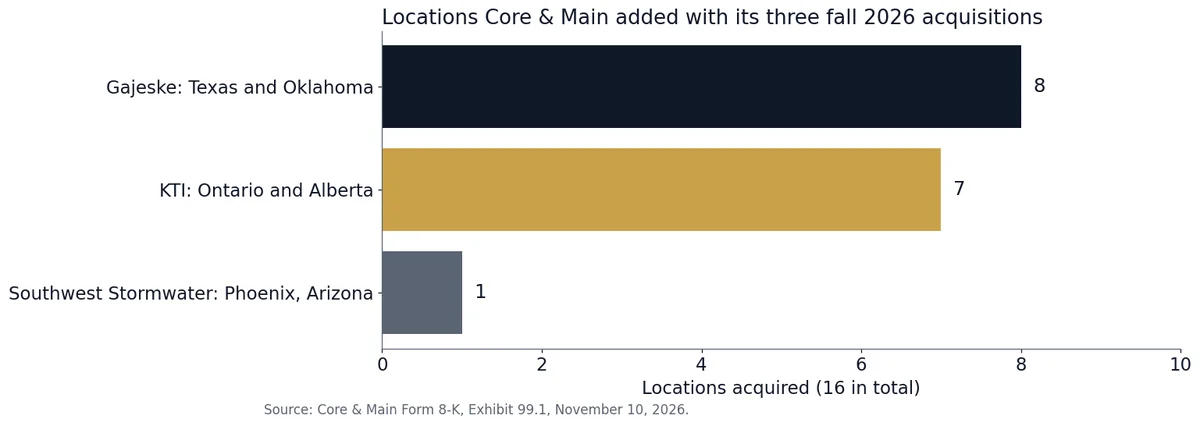
Core & Main bought three specialty distributors in three months: Southwest Stormwater Solutions in September 2026, Gajeske in October and KTI in November. All three had closed by the time the company furnished its November 10, 2026 Form 8-K, which reported them alongside preliminary third-quarter results. Together they bring 16 locations and over $250 million of combined annual revenue to a buyer with more than 370 locations.
| Target | Based in | Locations | Closed (2026) | What it does | Source |
|---|---|---|---|---|---|
| Southwest Stormwater Solutions | Phoenix, Arizona | 1 | September | Proprietary underground stormwater vault systems for municipalities, contractors and civil engineers | 8-K |
| Gajeske, LLC | Houston, Texas | 8 (Texas and Oklahoma) | October | Fusible HDPE pipe and fittings, fabrication, fusion equipment rental, field services | 8-K |
| KTI Limited and KTI Utility Services | Toronto area, Ontario | 7 (Ontario and Alberta) | November | Water meters and AMI (advanced metering infrastructure), including installation and field services | 8-K |
| Combined | 3 states, 2 provinces | 16 | Sep to Nov | Over $250 million combined annual revenue | 8-K |
The 8-K names no purchase price, no multiple, no advisors and no statement on whether founders, managers or brands stay. The full third-quarter report due December 8, 2026 is the next filing that could add detail.
Who are Southwest Stormwater Solutions, Gajeske and KTI?
All three are founder or family businesses with a narrow technical specialty, the profile Core & Main buys. Gajeske and KTI publish their histories; Southwest Stormwater Solutions has almost no public footprint beyond its one-line 8-K description and single Phoenix location.
- Gajeske. Bob Gajeske, Sr. started the business in 1986 in a Northwest Houston garage with a stock of small-diameter polyethylene pipe, and CEO Bob Gajeske, Jr. runs it today (Gajeske, Who We Are). It rents and sells McElroy fusion machines, fields McElroy-certified technicians, fabricates HDPE assemblies and runs Operator Qualification and fusion training for water, gas distribution, energy, mining, municipal and data center customers. It recently opened its first Oklahoma branch in El Reno.
- KTI. Ken Iwai founded KTI Limited on January 1, 1988; it calls itself family-owned and runs from an Aurora, Ontario head office built in 2006 with more than 34,000 square feet indoors and more than 5 acres of secured outdoor storage (KTI, About). It supplies gas, water and electric utilities, and its KTI Utility Services arm installs meters in the field.
- Southwest Stormwater Solutions. One Phoenix location selling proprietary underground stormwater vault systems to municipalities, contractors and civil engineers, per the 8-K.
What did Core & Main say about the three deals?
Chief Executive Officer Mark Witkowski tied all three deals to product strategy: “We continue to execute our strategy across multiple avenues for growth, strengthening our platform through acquisitions in storm drainage, fusible HDPE and smart utility solutions and completing another record quarter of open market share repurchases,” he said in the November 10 release. The same release reported a record eight greenfield branches opened year to date.
The backdrop: preliminary third-quarter net sales of $2.12 billion to $2.13 billion, up 3%, and a fiscal 2026 Adjusted EBITDA outlook trimmed to $950 million to $960 million from $950 million to $980 million on softer residential lot development. Acquired revenue helps fill that gap.
How often does Core & Main buy companies?
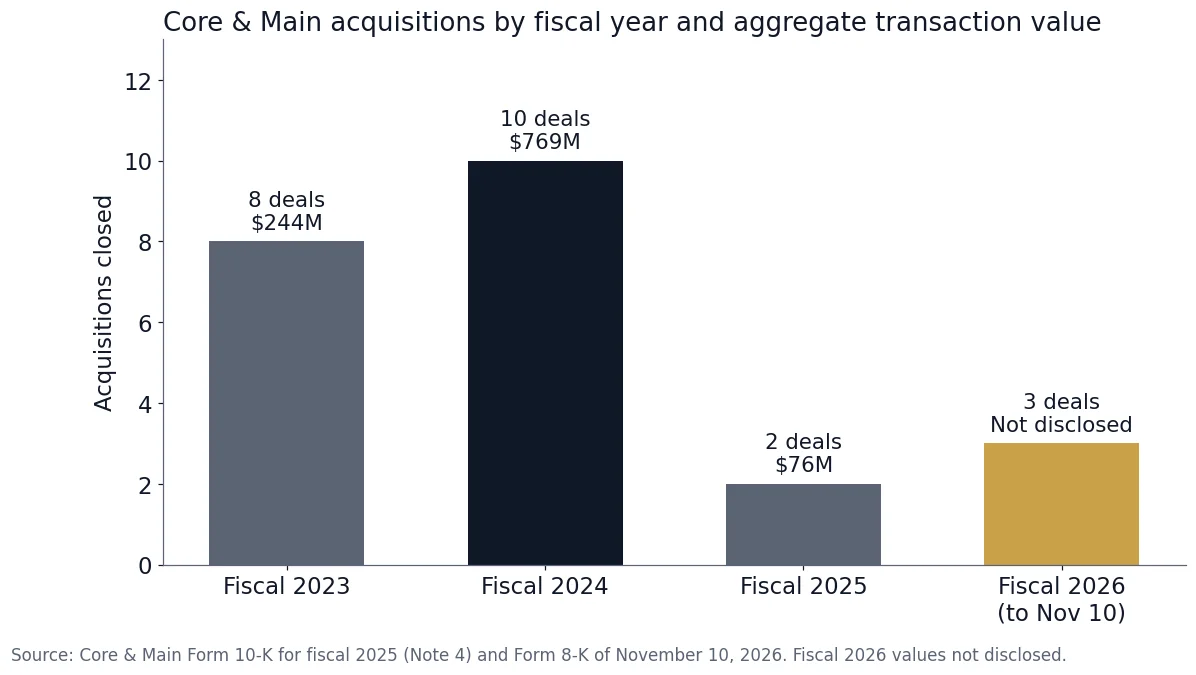
Core & Main closed 20 acquisitions from March 2023 through January 2026, then paused: its 10-Q for the quarter ended August 2, 2026 reports no acquisitions in the first six months of fiscal 2026. The three fall deals restart that pace. Aggregate transaction value was $244 million in fiscal 2023, $769 million in fiscal 2024 and $76 million in fiscal 2025, funded with cash and term loan borrowings (10-K, Note 4).
| Closed | Target | Locations | Product line | Structure |
|---|---|---|---|---|
| Nov 2026 | KTI Limited and KTI Utility Services | 7 | Meters and AMI, Canada | Not disclosed |
| Oct 2026 | Gajeske, LLC | 8 | Fusible HDPE | Not disclosed |
| Sep 2026 | Southwest Stormwater Solutions | 1 | Stormwater vaults | Not disclosed |
| Jan 26, 2026 | Pioneer Supply | 2 | Water and wastewater | Shares |
| Sep 30, 2025 | Canada Waterworks | 3 | Water and wastewater, Canada | Assets |
| Nov 7, 2024 | ARGCO Northeast | 1 | Fire protection | Assets |
| Oct 30, 2024 | Eastcom Associates | 1 | Underground utility protection | Assets |
| Sep 16, 2024 | Green Equipment Company | 1 | Underground utility protection | Assets |
| Sep 9, 2024 | GroGreen Solutions Georgia | 4 | Geosynthetics | Assets |
| Aug 12, 2024 | HM Pipe Products | 2 | Water and wastewater, Canada | Assets |
| May 6, 2024 | Geothermal Supply Company | 1 | Fusible HDPE | Assets |
| Apr 30, 2024 | EGW Utilities | 1 | Underground utility infrastructure | Assets |
| Apr 1, 2024 | NW Geosynthetics (ACF West) | 6 | Geosynthetics | Shares |
| Mar 7, 2024 | Dana Kepner | 21 | Water, wastewater, storm drainage | Membership interests |
| Feb 12, 2024 | Eastern Supply | 2 | Storm drainage with fabrication | Assets |
| Jan 16, 2024 | Lee Supply | 4 | Fusible HDPE, fusion rental, fabrication | Assets |
| Dec 4, 2023 | Granite Water Works | 1 | Water, wastewater, storm drainage | Assets |
| Nov 28, 2023 | Enviroscape | 1 | Geosynthetics, erosion control | Assets |
| Jul 12, 2023 | J.W. D’Angelo Company | 3 | Fire protection and waterworks | Shares |
| Jul 10, 2023 | Precast and drainage distributor (named in 10-K) | 7 | Precast, pipe, drainage | Assets |
| Apr 17, 2023 | Midwest Pipe Supply | 1 | Drainage and waterworks | Assets |
| Apr 10, 2023 | UPSCO | Not stated | Utility infrastructure products | Assets |
| Mar 6, 2023 | Landscape & Construction Supplies | 2 | Geosynthetics | Assets |
Two patterns stand out. First, Gajeske is the third fusible HDPE specialist in under three years, after Lee Supply (4 locations, January 2024) and Geothermal Supply Company (1 location, May 2024); with 8 branches it is the largest of the three. Second, KTI is the third Canadian deal after HM Pipe Products in August 2024, which Core & Main said opened “a new multi-billion-dollar addressable market opportunity in Canada” (Q2 2024 release), and Canada Waterworks in September 2025.
Why does Core & Main want stormwater, fusible HDPE and meter businesses?
Core & Main buys product lines its branches can sell to existing customers. Its fiscal 2025 10-K names smart metering, fusible HDPE, treatment plant solutions, fabrication and geosynthetics as underpenetrated categories it wants to grow, and all three new targets sit inside that list. In fiscal 2025 the company sold $1,194 million of storm drainage products and $716 million of meter products.
The market is fragmented enough to support years of buying. Core & Main estimates its addressable market at about $44 billion, holds roughly 17% of it, and competes nationally with only one other distributor; hundreds of regional, local and specialty niche distributors serve the rest. Its sales split about 44% municipal, 38% non-residential and 18% residential, so municipal water and stormwater budgets drive much of demand.
Its own investor deck spells out the funnel. The Q4 fiscal 2025 presentation lists hundreds of acquisition targets, 50+ actionable opportunities, about 12 in the pipeline at any point in time and a $1B+ sales opportunity over 5 years, with “clear strategic and financial criteria focused on geographic and product line expansion” and a “flexible integration approach that preserves local operating model.” The Q2 fiscal 2026 release adds that treatment plants and data centers delivered strong growth, and Gajeske already markets HDPE piping to data center builders.
How big is the distributor market in Texas, Oklahoma and Arizona?
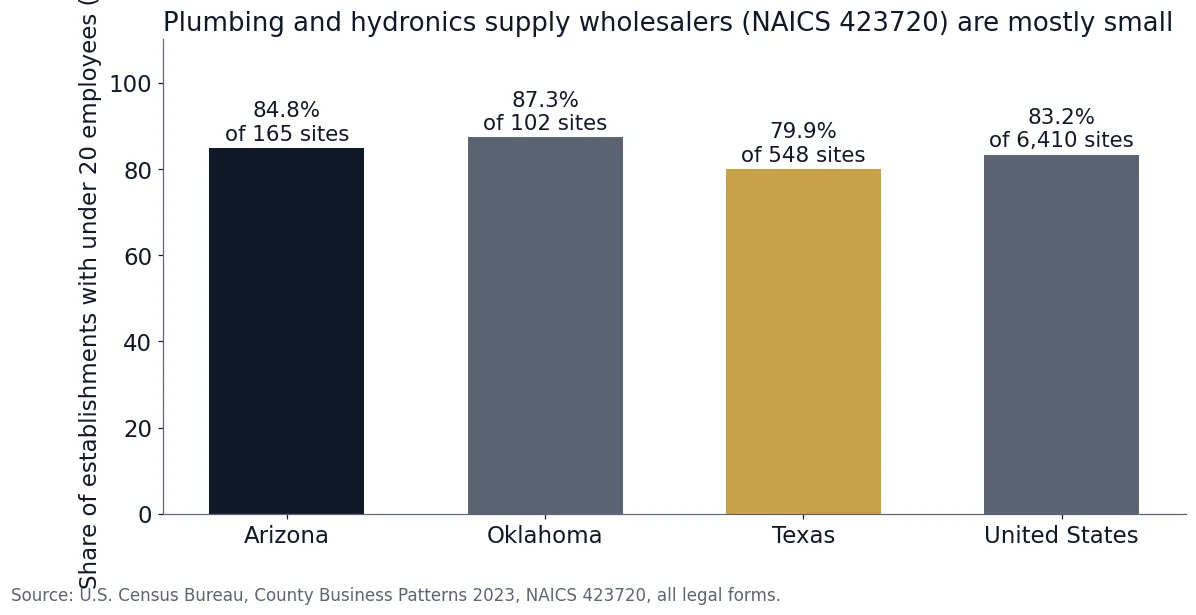
The closest Census industry code for waterworks and pipe distributors, NAICS 423720 (plumbing and heating equipment and supplies merchant wholesalers), counted 548 establishments in Texas, 165 in Arizona and 102 in Oklahoma in County Business Patterns 2023. Roughly 4 in 5 have fewer than 20 employees. The code also includes HVAC and hydronics wholesalers, so it overstates the pure waterworks count, but the size mix shows how fragmented the field is.
| Area | Establishments | Employees | Annual payroll | Under 20 employees | Payroll per employee | Source |
|---|---|---|---|---|---|---|
| Texas | 548 | 6,867 | $587.2 million | 438 (79.9%) | About $85,500 | CBP 2023 |
| Arizona | 165 | 1,745 | $140.7 million | 140 (84.8%) | About $80,600 | CBP 2023 |
| Oklahoma | 102 | 843 | $60.2 million | 89 (87.3%) | About $71,400 | CBP 2023 |
| United States | 6,410 | 84,257 | $7.16 billion | 5,330 (83.2%) | About $84,900 | CBP 2023 |
Texas is the deep pool: 90 of its NAICS 423720 establishments employ 20 to 49 people and 17 employ 50 to 99, the band where Gajeske-sized targets sit. Gas distribution work adds a regulatory layer: crews on pipeline facilities must hold operator qualification under 49 CFR 192.801 (Subpart N, Qualification of Pipeline Personnel), which is why Gajeske’s OQ training program is a sellable asset, not a side service.
What is a waterworks or HDPE distributor worth?
Core & Main does not disclose per-deal prices, so the useful benchmarks are its aggregate filings and disclosed deals elsewhere. Its fiscal 2024 acquisitions cost $769 million and added more than $600 million of annual net sales, which works out to about 1.28 times sales at most. CT’s industrial distribution M&A multiples report cites KPMG’s July 2026 list of disclosed distribution deals at 6.0x to 11.9x EBITDA, with a 9.4x mean.
Core & Main’s own margin gives the translation between the two yardsticks. Fiscal 2025 Adjusted EBITDA was $931 million on $7,647 million of net sales, a 12.2% margin. A target with a thinner margin than that looks expensive on an EBITDA basis at the same revenue multiple, which is why revenue and EBITDA multiples can tell different stories about the same deal.
Worked example (illustrative, not this deal’s price). Assume a fusible HDPE distributor with $30 million of revenue and a 9% EBITDA margin.
| Step | Calculation | Result (illustrative) |
|---|---|---|
| EBITDA | $30 million x 9% | $2.7 million |
| Low end of KPMG range | $2.7 million x 6.0 | $16.2 million |
| KPMG mean | $2.7 million x 9.4 | $25.38 million |
| High end of KPMG range | $2.7 million x 11.9 | $32.13 million |
| If 20% of the mean price is an earnout | $25.38 million x 20% | $5.076 million at risk |
| Cash at close in that case | $25.38 million less $5.076 million | $20.304 million |
| Revenue check at the fiscal 2024 Core & Main ratio | $30 million x 1.28 | $38.4 million (implies a margin well above 9%) |
The last row is the warning: a strategic buyer’s blended revenue ratio overstates the value of a lower-margin business. Margin quality, product exclusivity and how much of the customer book follows the owner decide where a company lands between $16.2 million and $32.13 million.
What does this mean for pipe, stormwater and meter distributor owners?
Core & Main has now shown three times that it will pay for a specialist line rather than another generalist branch. An owner of a fusible HDPE, stormwater product or metering business in a state or province where Core & Main lacks that specialty is the profile its 10-K describes, and the fall 2026 deals show the M&A team is active again after a quiet first half.
Who Core & Main is likely to want next
- Fusion and HDPE specialists outside Texas. Gajeske adds 8 branches in Texas and Oklahoma on top of Lee Supply and Geothermal Supply Company; a fusion distributor in a neighboring state fills the next gap on that map.
- Metering and AMI installers. KTI adds field installation, not only product. Meter products were $716 million of fiscal 2025 sales, so installation crews with utility contracts fit a category already that size.
- Proprietary stormwater products. Southwest Stormwater Solutions had one location; its value was the vault system line. A one-branch company with an exclusive or proprietary product can matter more than a five-branch commodity house.
- Canadian waterworks. KTI is the third Canadian deal after HM Pipe Products and Canada Waterworks. CT’s Canada PE buyer landscape lists the sponsors competing for the same companies.
Decision table: if your company is…, then…
| If your company is… | Then… |
|---|---|
| A fusible HDPE or PE pipe distributor with fusion rental and certified techs | Expect strategic interest; document technician certifications, fleet hours and rental utilization before any call |
| A stormwater or drainage supplier with a proprietary or exclusive product line | Check whether supplier and licensing agreements survive a change of control; that clause can carry most of the value |
| A meter or AMI installer with multi-year utility contracts | Map contract terms, assignment consent and remaining backlog; a buyer prices the contracted years, not last year |
| A generalist waterworks branch where Core & Main already has locations | Expect a lower premium from Core & Main and test regional distributors and sponsors too |
| An underground utility contractor rather than a distributor | Different buyers and multiples apply; see CT’s underground utility valuation guide |
| Under 20 employees with the owner as lead salesperson | Plan for key-person questions and a likely earnout; build a second sales layer before going to market |
What to prepare before a strategic buyer calls
- Three years of revenue and gross margin by product line, so a buyer can see the specialty margin separately from commodity pipe.
- Supplier agreements, exclusivities and change-of-control clauses, with renewal dates.
- Customer concentration: top 10 customers as a share of sales, and which are municipalities under bid contracts.
- Certifications held by employees (fusion, OQ under 49 CFR Part 192 Subpart N, meter installation), with who holds them.
- Equipment register for rental fleets: purchase dates, hours and maintenance logs; plus yard leases and whether owned real estate is in the sale.
Risks to price in
Three risks show up in Core & Main’s own filings. Earnouts: the fiscal 2025 deals carry up to $18 million of contingent consideration tied to two years of Adjusted EBITDA, valued at $14 million at closing and $12 million by August 2, 2026 (see how earnouts work). Structure: 16 of 20 deals were asset purchases, which can change the seller’s tax bill, especially for a C corporation, so ask your CPA to model asset versus stock sale before signing a letter of intent. Key people: Core & Main valued acquired customer relationships at a 12.4% annual attrition rate, so a buyer expects some customers to leave and will want the people who hold them.
Core & Main pays cash from its own balance sheet and term loans, so a sale to it is usually a clean exit with no rollover equity. Private equity platforms more often ask founders to roll part of their proceeds into the new company, which is the main trade-off covered in strategic buyer vs financial buyer. Other buyers active in adjacent trades this month, including SiteOne in erosion control, are in the November 2026 home services acquisitions roundup; utility contractors should start with the underground utility contracting valuation guide.
How we compiled this
We compiled this from 7 Core & Main SEC filings and exhibits on EDGAR, the Gajeske and KTI websites, 49 CFR 192.801 and the Census County Business Patterns 2023 files, all accessed in November 2026. We excluded press coverage that repeated the release, and we had no contact with the parties.
If you own a pipe, stormwater or metering business and want to know which of these buyers would compete for it, book a confidential call. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells.
Frequently asked questions
Who owns Gajeske now?
Core & Main, Inc. (NYSE: CNM) owns Gajeske. Core & Main reported in its November 10, 2026 Form 8-K that it acquired Gajeske, LLC of Houston, Texas in October 2026. Gajeske distributes fusible HDPE pipe and fittings and offers fabrication and fusion equipment rental from eight locations across Texas and Oklahoma.
Who bought KTI Limited?
Core & Main bought KTI Limited and KTI Utility Services in November 2026, according to its November 10, 2026 Form 8-K. KTI supplies and installs water meters and AMI systems from seven locations across Ontario and Alberta. KTI Limited describes itself as family-owned since January 1, 1988, with its head office in Aurora, Ontario.
How much did Core & Main pay for Southwest Stormwater, Gajeske and KTI?
Core & Main did not disclose a price for any of the three deals. Its November 10, 2026 Form 8-K says only that the three businesses represent over $250 million in combined annual revenue.
Is Core & Main still buying distributors?
Yes. Core & Main’s fiscal 2025 investor presentation describes hundreds of acquisition targets, 50+ actionable opportunities and about 12 in its pipeline at any point in time, with criteria focused on geographic and product line expansion. The three fall 2026 deals were its first closings of fiscal 2026, after none in the six months to August 2, 2026.
How much is a waterworks or pipe distributor worth?
There is no single number. CT’s industrial distribution report cites KPMG’s July 2026 list of disclosed distribution deals at 6.0x to 11.9x EBITDA, with a 9.4x mean. Core & Main’s fiscal 2024 deals cost $769 million for more than $600 million of acquired sales, about 1.28 times sales at most.
Sources
- Core & Main, Form 8-K Exhibit 99.1: Preliminary Third-Quarter Fiscal 2026 Results and Multiple Acquisitions, November 10, 2026, accessed November 2026.
- Core & Main, Form 10-K for fiscal year ended February 1, 2026 (Note 4, Acquisitions), March 24, 2026, accessed November 2026.
- Core & Main, Form 10-Q for quarter ended August 2, 2026, September 9, 2026, accessed November 2026.
- Core & Main, Q2 fiscal 2026 earnings release, September 9, 2026, accessed November 2026.
- Core & Main, Q4 fiscal 2025 investor presentation, March 24, 2026, accessed November 2026.
- Core & Main, Q4 fiscal 2024 investor presentation, March 25, 2025, accessed November 2026.
- Core & Main, Q2 fiscal 2024 earnings release, September 4, 2024, accessed November 2026.
- Gajeske, Who We Are, undated, accessed November 2026.
- KTI Limited, About, undated, accessed November 2026.
- 49 CFR 192.801, Scope of Subpart N, Qualification of Pipeline Personnel (Cornell LII), current, accessed November 2026.
- U.S. Census Bureau, County Business Patterns 2023 datasets, NAICS 423720, released 2025, accessed November 2026.