Free Landscaping Business Valuation Calculator: What’s Your Landscaping Business Worth in 2026, by Business Model and Contract Mix?
Landscaping business valuation in 2026: small owner-run firms sell for about 1.5x to 4x SDE and larger commercial firms for 3x to 7x EBITDA (Singleton Valuations, April 2026); public BrightView trades near 5.8x.
By Christoph Totter, Founder of CT Acquisitions · Last reviewed: November 2026
Thinking about selling your landscaping business?
Skip the formulas. A 15-minute confidential call gives you a valuation range and tells you which buyers would compete for your contract book: a PE-backed commercial platform, a regional operator or an individual buyer. No cost, no obligation.
Landscaping business valuation calculator
Enter your revenue, EBITDA or SDE, and the share of revenue under recurring maintenance contracts. The calculator places you on the published ranges in the table below and returns a starting range in under a minute. It is a screening estimate, not a Quality of Earnings report. The same tool runs on its own page as the landscaping valuation calculator.
How CT Acquisitions Works
- How we are paid. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells.
- Confidential sale. Your company is never publicly listed, and buyers see its name only after signing an NDA.
- 500+ buyers. Our network includes PE-backed commercial landscaping platforms, regional operators and family offices, so you can compare a full sale, a recapitalization or a later exit.
Key takeaways
- Smaller landscaping companies trade at 1.5x to 3x SDE or 2x to 5x EBITDA, and larger ones at 2.5x to 4x SDE or 3x to 7x EBITDA (Singleton Valuations, April 16, 2026).
- BrightView Holdings (NYSE: BV), the largest US commercial landscaper, earned $328.9 million of Adjusted EBITDA on $2,712.6 million of revenue in fiscal 2026 (BrightView 8-K, November 10, 2026); at the November 11, 2026 close its enterprise value was about 5.8x that figure (CT arithmetic below).
- First Page Sage lists 9.9x to 12.2x EBITDA for commercial landscapers with $500K to $10M of EBITDA (First Page Sage, February 6, 2025), well above the public benchmark, so treat it as an outlier, not a target.
- Landscaping and groundskeeping workers were 89,013 of the 232,434 H-2B positions certified in FY2025, or 38.3% (US Department of Labor), so buyers review visa dependence in diligence.
- Livingstone Partners counted more than 30 PE platforms in commercial landscaping as of November 1, 2024, with most noteworthy PE exits over the prior decade at 7x to 15x EBITDA (Livingstone Partners).
What is a landscaping business worth in 2026?
A landscaping business is worth a multiple of its normalized earnings. Owner-run firms are priced on SDE at roughly 1.5x to 4x, firms with a manager and over $3,000,000 of revenue on EBITDA at roughly 3x to 7x (Singleton Valuations, April 2026; MidStreet, February 2021), and multi-state platforms higher. The multiple moves with maintenance contract share, size and owner dependence.
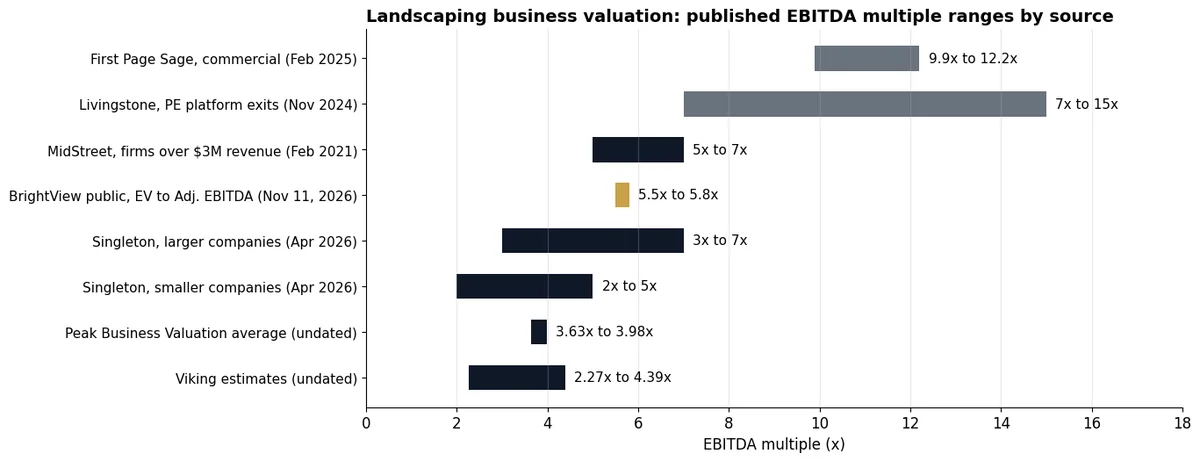
No government dataset publishes landscaping sale multiples, so every private-company range below is an advisor or broker estimate, shown with its date and sample. BrightView is the only figure computed from public filings.
| Source | Published range | Earnings basis and scope | Date and sample |
|---|---|---|---|
| Singleton Valuations | 1.5x to 3x SDE, 2x to 5x EBITDA (smaller); 2.5x to 4x SDE, 3x to 7x EBITDA (larger) | Landscaping companies by size | April 16, 2026; proprietary data, no sample size |
| Peak Business Valuation | 2.76x to 3.21x SDE; 3.63x to 3.98x EBITDA; 0.67x to 0.89x revenue | Average across its own landscaping data | Undated; no sample stated |
| Viking Mergers & Acquisitions | 2.27x to 4.39x EBITDA | Labelled estimates | Undated; no deal count on the page |
| MidStreet Mergers & Acquisitions | 2x to 4x SDE, or 5x to 7x EBITDA | EBITDA basis for firms over $3,000,000 of revenue | February 15, 2021 |
| BrightView Holdings (CT arithmetic) | 5.8x FY2026 Adjusted EBITDA; 5.5x FY2027 guidance midpoint | Public company, $2,712.6 million revenue | Market close November 11, 2026 |
| Livingstone Partners | Most between 7x and 15x EBITDA | Noteworthy PE exits of platforms over the last decade | November 1, 2024 |
| First Page Sage | 9.9x, 11.1x, 12.2x EBITDA (commercial); 7.8x, 9.1x, 9.7x (residential) | EBITDA bands $500k-1M, $1-3M, $3-10M | February 6, 2025; reports, PE networks and interviews |
What several guides say vs what the primary source says
Three figures circulate on landscaping valuation pages, including an earlier version of this one, with the wrong source or scope attached. The corrections below come from reading each publisher’s own page in November 2026.
| What guides repeat | What the source says | Why it matters to your price |
|---|---|---|
| “Commercial maintenance trades at 6x to 9x EBITDA, per First Page Sage” | First Page Sage shows 9.9x to 12.2x for commercial firms, built from interviews, not closed-deal data | Its smallest band (9.9x at $500K to $1M EBITDA) sits above BrightView’s 5.8x as a public company, the reverse of the usual size discount |
| “Landscapers sell for 7x to 15x” | Livingstone’s 7x to 15x describes noteworthy PE exits of platforms over a decade | It is a platform-exit range, not a range for a single-market firm |
| “5x to 7x EBITDA” as a general landscaping multiple | MidStreet applies EBITDA only above $3,000,000 of revenue, in an article dated February 15, 2021 | Below that size MidStreet prices on SDE at 2x to 4x |
How is a landscaping business valued, step by step?
Buyers value a landscaping business by normalizing earnings, choosing SDE or EBITDA, splitting revenue into maintenance, installation and snow, testing the contract book and fleet, then applying a multiple and adjusting for debt, working capital and deferred capex. MidStreet uses EBITDA above $3,000,000 of revenue and warns that lenders avoid deals below $350,000.
- Normalize earnings. Start from tax returns and the monthly close. Add back owner pay above a market manager salary, personal expenses and one-time costs that a buyer will accept; the add-backs buyers reject are covered in which EBITDA add-backs buyers accept.
- Pick the earnings basis. Use SDE if the owner runs crews and sells the work; use EBITDA once a general manager runs operations or revenue passes $3,000,000 (MidStreet threshold).
- Split revenue by line. Separate recurring maintenance, enhancements, design/build installation and snow. BrightView reports maintenance and development separately because they behave differently: in fiscal 2026 maintenance rose 6.0% while development fell 9.4%.
- Rebuild the contract book. List every maintenance contract with customer, annual value, start date, renewal history and price escalator, then compute the share of revenue held by your top 10 customers.
- Price the fleet. Prepare a 3-year forward capex schedule for mowers, trucks, trailers and specialty equipment; buyers deduct deferred replacement from the price.
- Normalize snow. Average snow revenue over several winters. BrightView guides its fiscal 2027 snow revenue to $210 to $230 million, which it describes as an approximate 5-year average.
- Apply the multiple and adjust. Multiply normalized earnings by the multiple for your size band, then subtract debt and any working capital shortfall to reach the cash you receive.
What does BrightView’s stock price say about landscaping multiples?
BrightView, the one public pure-play US landscaper, was valued at about 5.8x its fiscal 2026 Adjusted EBITDA of $328.9 million at the November 11, 2026 close: a $900.14 million market cap plus $1,013.9 million of net financial debt. That is a large, multi-state company with 12.1% margins, so it marks the upper middle of the range, not a floor.
| Line | Figure | Source |
|---|---|---|
| Fiscal 2026 revenue (year to September 30, 2026) | $2,712.6 million | BrightView 8-K, November 10, 2026 |
| Maintenance Services revenue | $2,004.6 million, up 6.0% (about 74% of revenue) | BrightView 8-K |
| Development Services revenue | $714.9 million, down 9.4% | BrightView 8-K |
| Adjusted EBITDA and margin | $328.9 million; 12.1% | BrightView 8-K |
| Net financial debt; ratio to Adjusted EBITDA | $1,013.9 million; 3.1x | BrightView 8-K |
| Market cap at November 11, 2026 close ($9.87 per share) | $900.14 million | Stock Analysis |
| Enterprise value (market cap plus net financial debt) | $1,914 million | CT arithmetic |
| EV / fiscal 2026 Adjusted EBITDA | 5.8x | CT arithmetic |
| EV / fiscal 2027 guidance midpoint ($345 million) | 5.5x | CT arithmetic; guidance $335 to $355 million |
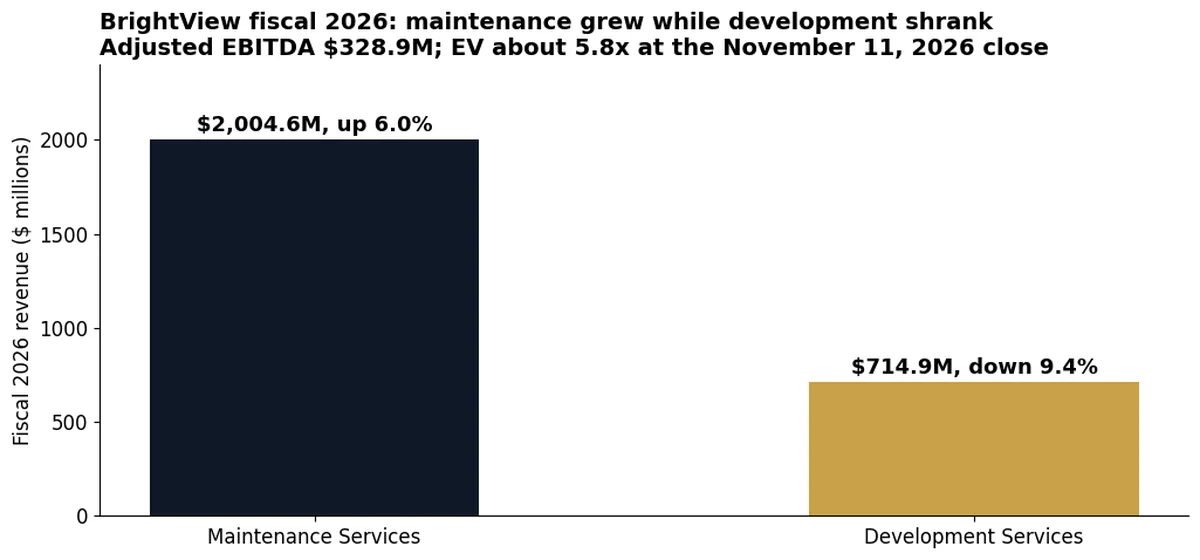
Stock Analysis lists a $1.99 billion enterprise value for the same date, which works out to 6.1x. The gap comes from what each method counts as debt; either way the public market prices the largest US landscaper near 6x, not 9x to 12x. The 8-K also shows why buyers pay more for maintenance: it grew while installation work shrank.
Who is buying landscaping companies in 2026?
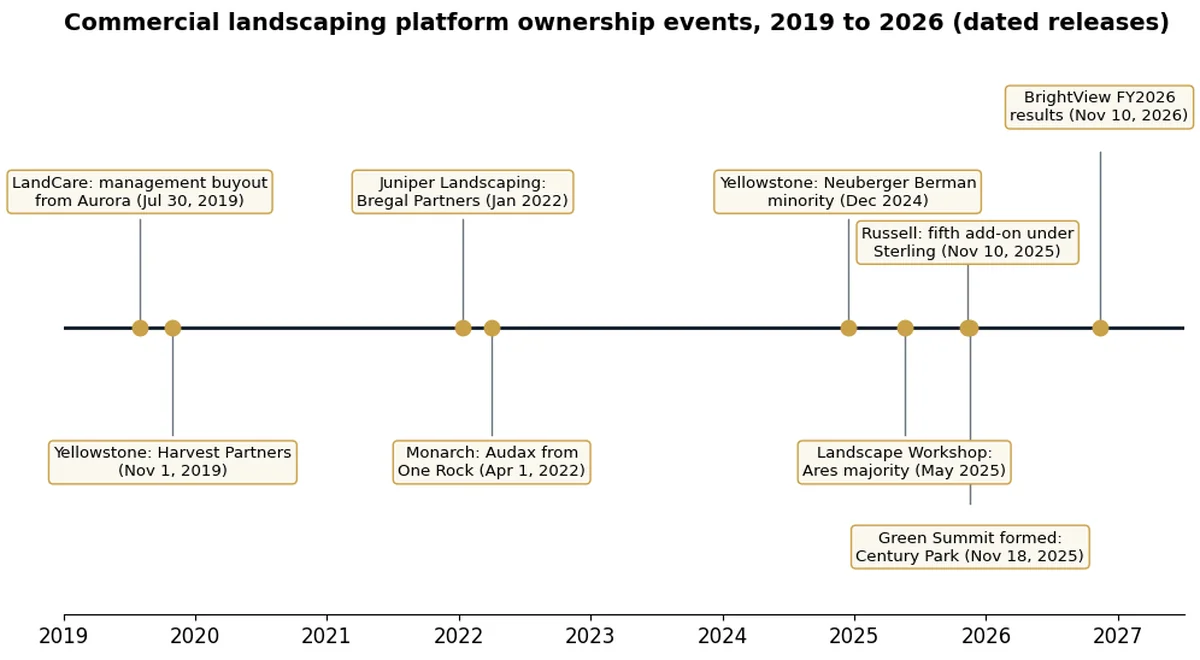
Commercial landscaping buyers in 2026 are mostly PE-backed platforms adding regional firms: Yellowstone (Harvest Partners), Juniper Landscaping (Bregal Partners), Monarch (Audax), Landscape Workshop (Ares), Russell (The Sterling Group) and Green Summit (Century Park), plus public BrightView. Livingstone counted more than 30 PE platforms as of November 2024. Each row below is tied to a dated release.
| Platform | Owner or backer | Date | What the release says |
|---|---|---|---|
| BrightView Holdings | Public, NYSE: BV | November 10, 2026 | $2,712.6 million fiscal 2026 revenue (8-K) |
| Yellowstone Landscape, Palm Coast, Florida | Harvest Partners, bought from CIVC Partners | November 1, 2019 | 40 branches, more than 5,000 customers (Harvest release); Neuberger Berman minority stake, December 2024 (Ropes & Gray) |
| Juniper Landscaping, Fort Myers, Florida | Bregal Partners | January 11, 2022 | $101 million 2020 revenue, 15 branches (Landscape Management) |
| Monarch Landscape Companies, western US | Audax Private Equity, bought from One Rock Capital Partners | April 1, 2022 | Formed by One Rock in 2015; ten acquisitions (One Rock release) |
| Landscape Workshop, Southeast | Ares Management (majority), bought from Carousel Capital | May 2025 | 38 locations (K&L Gates) |
| Russell Landscape Group, Sugar Hill, Georgia | The Sterling Group Foundation Fund (2024) | November 10, 2025 | Fifth acquisition (Utz Environmental Services, Austin); 16 regional operations in six states (Sterling release) |
| Green Summit Landscape Group | Century Park Capital Partners | November 18, 2025 | Platform formed with its first acquisition (Century Park release) |
| LandCare | Management and investors led by Scott Brickman, bought from Aurora Resurgence | July 30, 2019 | 50 branches in 20 states and Washington DC (Aurora release); not PE-owned since |
Only BrightView discloses its numbers; none of the private releases above states a price or multiple. Tree care has its own set of sponsors, tracked in the tree service PE roll-up tracker, and deal-level multiples by size band are in the landscaping M&A multiples report.
Which factors move a landscaping multiple up or down?
Four factors move a landscaping multiple most: the share of revenue under recurring maintenance contracts, how much of the work depends on the owner, H-2B and labor compliance, and fleet condition. MidStreet notes installation-heavy and fully residential firms sell lower, and BrightView’s fiscal 2026 split shows maintenance growing 6.0% while development fell 9.4%.
| Factor | What buyers check | Evidence |
|---|---|---|
| Maintenance contract share | Recurring maintenance vs installation and enhancement revenue | MidStreet: installation-reliant firms carry higher risk; BrightView maintenance up 6.0%, development down 9.4% in fiscal 2026 |
| Commercial vs residential mix | HOA, property manager and commercial accounts vs homeowners | MidStreet: commercial firms sell for higher multiples; a fully residential book hurts value |
| Owner dependence | Who sells, prices and holds the top 10 accounts | MidStreet: EBITDA pricing applies once management runs the firm; owner-run firms are priced on SDE |
| H-2B labor | Certification history, wage and housing compliance, returning workers | DOL: 38.3% of FY2025 certified H-2B positions were landscaping; statutory cap 66,000 per year (8 U.S.C. 1184(g)(1)(B)) |
| Snow and winter revenue | Multi-winter average vs one heavy season | BrightView guides snow to an approximate 5-year average |
| Fleet and capex | Equipment age and a 3-year forward capex schedule | Deferred replacement is deducted from price |
The statute caps new H-2B visas at 66,000 per fiscal year, 33,000 per half (Congressional Research Service R44306, May 14, 2026), plus 64,716 supplemental visas released for FY2026. Buyers use the program too: Landscape Workshop had 1,840 positions certified in FY2025 and Brightview Landscapes 1,178.
If you run snow, read the snow removal business valuation guide for how buyers average winter revenue, and the guide to service agreements and business value for contract terms that hold up in diligence.
How much is a landscaping business with $1 million in sales worth?
Price follows earnings, not sales. As an illustrative case, a residential firm with $1 million in sales and $200,000 of SDE lands between $300,000 and $800,000 on the Singleton and MidStreet SDE ranges. A commercial firm with $6M of revenue and $1,105,000 of normalized EBITDA lands between $3,315,000 and $7,735,000 on Singleton’s larger-company range.
Both cases are illustrative: hypothetical inputs, published multiples from the ranges table.
| Step | Case A: residential, $1M sales | Case B: commercial, $6M revenue |
|---|---|---|
| Reported earnings | $200,000 SDE | $1M reported EBITDA |
| Add-backs | Included in SDE | +$40K owner pay above a $140K replacement GM; +$40K personal expenses; +$25K one-time costs |
| Normalized earnings | $200,000 SDE | $1,105,000 EBITDA |
| Low multiple | 1.5x SDE (Singleton, smaller) = $300,000 | 3x EBITDA (Singleton, larger) = $3,315,000 |
| Middle reference | 2.76x to 3.21x SDE (Peak) = $552,000 to $642,000 | 3.63x to 3.98x (Peak) = $4,011,150 to $4,397,900; 5.8x (BrightView) = $6,409,000 |
| High multiple | 4x SDE (MidStreet) = $800,000 | 7x EBITDA (Singleton, larger) = $7,735,000 |
| Who buys at this size | Individual buyer; MidStreet says lenders avoid deals below $350,000 | PE-backed platform or regional operator |
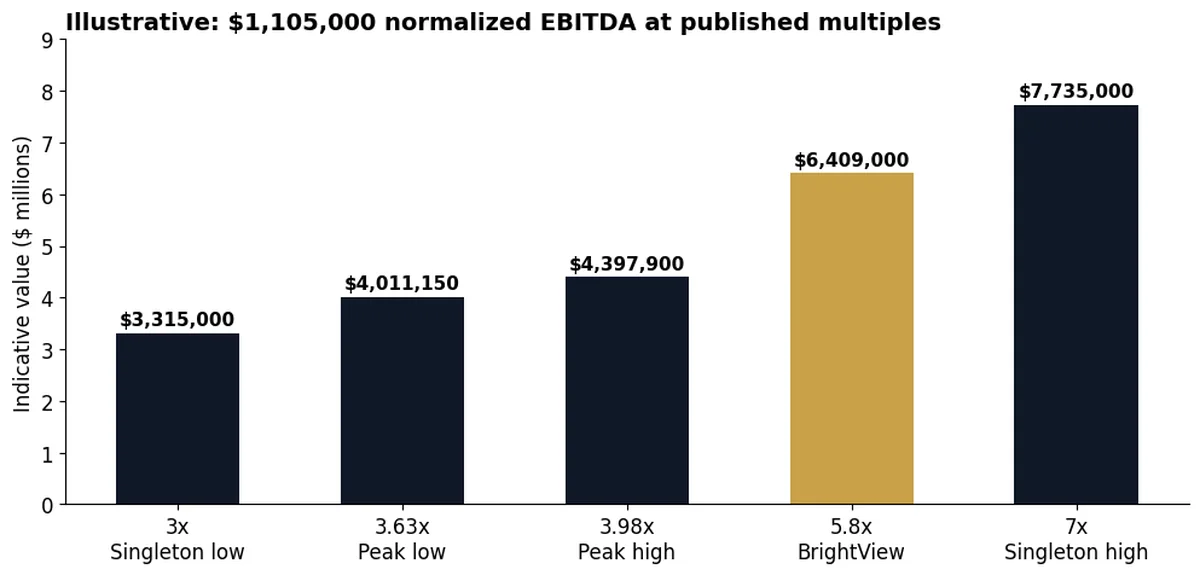
Case B shows why the same truck count can be worth $3,315,000 or $7,735,000. Buyers pay the top of Singleton’s range for a firm where a general manager holds the commercial accounts and most revenue renews each year, and the bottom for one where the founder sells every large contract. A $300,000-a-year owner on SDE sits between $450,000 at 1.5x and $1,200,000 at 4x.
What happens to the price after the multiple is applied?
The headline price is not what you keep. Most landscaping sales are asset sales, and IRS Form 8594 splits the price across seven asset classes. Equipment sold above its depreciated tax basis is taxed as ordinary income under IRC Section 1245, while goodwill in Class VII is usually taxed as capital gain, so the allocation changes your after-tax result.
| Item | Rule | Effect on a landscaping seller |
|---|---|---|
| Purchase price allocation | IRS Form 8594, Class I to Class VII; buyer and seller both file | Agree the allocation in the purchase agreement, not after closing |
| Equipment recapture | 26 U.S.C. 1245 | Illustrative: $400,000 allocated to mowers and trucks with a $50,000 tax basis creates $350,000 of ordinary income |
| Net investment income tax | 26 U.S.C. 1411, 3.8% | Generally excludes gain from a business in which you materially participate; ask your CPA how it applies to a passive co-owner |
| Stock vs asset structure | Buyer usually prefers assets for the stepped-up basis | Compare both after tax; see asset sale vs stock sale |
Want to know what your landscaping business is worth to today’s buyers?
Published ranges give you a band. A 15-minute confidential call places your contract book within it and names the buyers likely to compete for it. No cost, no obligation.
Which buyer and timeline fit your landscaping business?
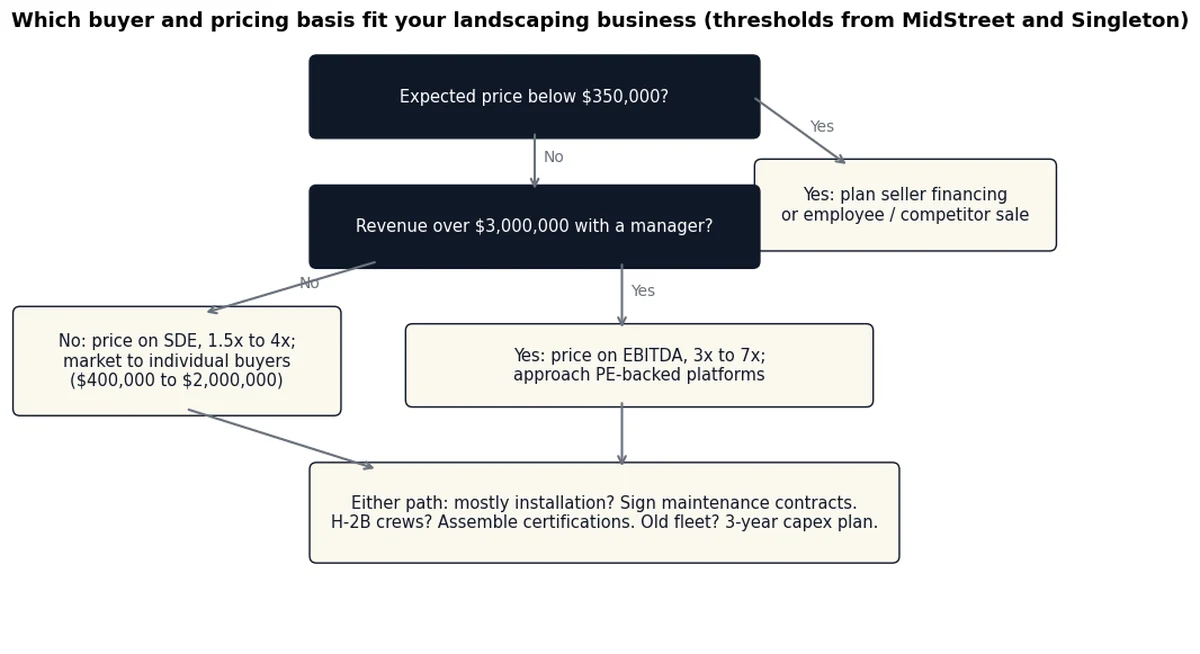
Match the buyer to your size and mix. Below $350,000 of expected price, plan for seller financing because MidStreet says lenders shy away; from $400,000 to $2,000,000 an individual buyer is most likely; above $3,000,000 of revenue with a manager in place, a PE-backed platform pricing on EBITDA becomes realistic. Use the decision table below.
| If your situation is | Then do this | Basis |
|---|---|---|
| If expected price is below $350,000 | Plan for seller financing or a sale to an employee or competitor | MidStreet: lenders shy away below $350,000 |
| If value is $400,000 to $2,000,000 and you run the crews | Price on SDE (1.5x to 4x) and market to individual buyers | MidStreet; Singleton, April 2026 |
| If revenue is over $3,000,000 and a manager runs operations | Price on EBITDA and approach PE-backed platforms in your region | MidStreet threshold; buyer table above |
| If most revenue is design/build installation | Sign maintenance contracts with install clients for 12 to 24 months before selling | MidStreet: installation reliance raises risk; BrightView development down 9.4% |
| If you rely on H-2B crews | Assemble certifications, wage and housing records for each season | DOL FY2025: 38.3% of certified H-2B positions were landscaping |
| If equipment is past its replacement cycle | Prepare a 3-year capex schedule and model the price deduction | Buyers deduct deferred capex |
Owners preparing over 12 to 24 months can follow the landscaping exit preparation checklist, and lawn care route owners should read how to sell a lawn care business. State-level buyer data is on the landscaping seller hub.
How we compiled this
We read 21 primary documents in November 2026: BrightView’s fiscal 2026 8-K, sponsor and company press releases for each platform in the buyer table, the US Department of Labor H-2B statistics for FY2025, the CRS report on the H-2B cap, IRS and US Code tax sections, and the pages of six valuation publishers. Multiples from advisors and brokers are labelled with their publisher, date and sample. We excluded forum posts, deal databases behind a login and any figure we could not open at its source.
Frequently asked questions
How much is a landscaping business with $1 million in sales worth?
Price follows earnings, not sales. In an illustrative case, a residential landscaping company with $1 million in sales and $200,000 of SDE would sell for about $300,000 to $800,000, using 1.5x SDE from Singleton Valuations (April 2026) at the low end and 4x SDE from MidStreet at the high end. Commercial contracts and a manager push it toward the top.
How much is a business worth that makes $300,000 a year?
If the $300,000 is seller’s discretionary earnings from a landscaping company, published SDE ranges of 1.5x to 4x (Singleton Valuations, April 2026) put it between $450,000 and $1,200,000. Peak Business Valuation’s average of 2.76x to 3.21x SDE points to the middle. A recurring commercial maintenance book and a crew leader who runs the routes move it up.
Is lawn care business valuation different from landscaping valuation?
The method is the same, but the inputs differ. First Page Sage lists lawn service firms at 8.6x to 10.5x EBITDA and commercial landscapers at 9.9x to 12.2x (February 2025), which shows the ordering even though both are high. Lawn care routes with recurring treatments are priced on route density and churn; landscaping adds installation and snow, which buyers average.
How accurate is a landscaping business valuation calculator?
A calculator gives a screening range, not a price. It cannot see contract terms, customer concentration, fleet age or H-2B records, and buyers adjust for all of them. Published inputs also disagree: Viking lists 2.27x to 4.39x EBITDA and First Page Sage 9.9x for small commercial firms. Use the result to decide whether to request a buyer-tested valuation.
Does H-2B labor affect a landscaping business valuation?
Yes. Landscaping and groundskeeping workers were 38.3% of the 232,434 H-2B positions certified in FY2025 (US Department of Labor), and the statutory cap is 66,000 visas per fiscal year. Buyers ask for every season’s certifications, wage records and housing arrangements, because a denied petition removes crews. A clean multi-year history reduces that diligence risk.
How long does it take to sell a landscaping business?
MidStreet puts the average at six to eight months to sell, while 51% of owners expect five months. Preparation adds time: moving accounts from the founder to a manager or growing maintenance contracts takes 12 to 24 months. Many owners aim to close after the busy season, so the trailing 12 months includes a full growing year.
Sources
- BrightView Holdings, Form 8-K Exhibit 99.1, fourth quarter and fiscal 2026 results (November 10, 2026), accessed November 2026.
- Stock Analysis, BrightView Holdings market cap (November 11, 2026 close), accessed November 2026.
- Singleton Valuations, Q1 2026 Landscaping Business Valuation Levels Update (April 16, 2026), accessed November 2026.
- Peak Business Valuation, Valuation Multiples for a Landscaping Company (undated), accessed November 2026.
- Viking Mergers & Acquisitions, Selling a Landscaping Business (undated), accessed November 2026.
- MidStreet Mergers & Acquisitions, How to Value and Sell a Landscaping Business (February 15, 2021), accessed November 2026.
- First Page Sage, EBITDA Multiples for Landscaping Companies (February 6, 2025), accessed November 2026.
- Livingstone Partners, Commercial Landscaping: An Owner’s Guide to Private Equity Activity and Valuation Considerations (November 1, 2024), accessed November 2026.
- Harvest Partners, acquisition of Yellowstone Landscape (November 1, 2019), accessed November 2026.
- Ropes & Gray, Yellowstone Landscape minority investment from Neuberger Berman Capital Solutions (December 2024), accessed November 2026.
- Landscape Management, Juniper Landscaping partners with private equity firm (January 11, 2022), accessed November 2026.
- One Rock Capital Partners, sale of Monarch Landscape Companies to Audax Private Equity (April 1, 2022), accessed November 2026.
- K&L Gates, Carousel Capital sale of majority interest in Landscape Workshop to Ares (July 24, 2025), accessed November 2026.
- The Sterling Group, Russell Landscaping completes fifth acquisition (November 10, 2025), accessed November 2026.
- Century Park Capital Partners, formation of Green Summit Landscape Group (November 18, 2025), accessed November 2026.
- Aurora Resurgence, sale of LandCare to company management (July 30, 2019), accessed November 2026.
- US Department of Labor, OFLC H-2B Selected Statistics FY2025 (data as of September 30, 2025), accessed November 2026.
- Congressional Research Service, The H-2B Visa and the Statutory Cap, R44306 (May 14, 2026), accessed November 2026.
- IRS, Instructions for Form 8594, accessed November 2026.
- 26 U.S.C. 1245, gain from dispositions of certain depreciable property, accessed November 2026.
- 26 U.S.C. 1411, net investment income tax, accessed November 2026.
This page is general valuation information, not legal, tax, accounting or transaction advice.
About the Author
Christoph Totter is the founder of CT Acquisitions, an M&A advisory firm that helps owners of founder-owned businesses make the most of their exit through confidential sales, recapitalizations and exit planning, headquartered in Sheridan, Wyoming, with a network of 500+ buyers, including PE-backed commercial landscaping platforms and regional operators. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells. Connect on LinkedIn · Get in touch
