
Med Spa Valuation and M&A Multiples Report 2026: Benchmarks by Size and Model
Med spa valuation in 2026: about 3x to 6x EBITDA for spas under $4M of revenue, 5x to 8x at $4M to $20M and 7x to 12x above $20M, per AmSpa’s May 2026 M&A review.
Key takeaways
- Size sets the band: med spas under $4M of revenue traded at 3x to 6x EBITDA in 2025, and regional platforms above $20M at 7x to 12x, per AmSpa and Xite (May 15, 2026).
- Quality sets the spot inside the band: premium assets command multiples 30% to 100% higher than undifferentiated peers, per the Skytale Group and Guidepoint Qsight report (December 2025).
- Skytale’s investor screen: annual EBITDA above $1 million, gross profit above 65%, adjusted EBITDA margin above 20% and 50% retention of new patients.
- Most deals pay about 60% cash at close and 40% rollover equity, rising to 80% cash and 20% rollover, per AmSpa and Xite.
- No Q3 2026 med spa deal disclosed a price: CT’s Q3 2026 deal file counted 19 transactions and 0 priced, and PitchBook reported on October 14, 2026 that LaserAway’s sale process is no longer active.
What is a med spa worth in 2026?
A med spa is worth its normalized earnings times a market multiple. The three named sources that publish bands agree on the shape: 3x to 6x EBITDA for small spas, 5x to 8x for mid-size groups and 7x to 12x for regional platforms. Small owner-run spas listed for sale ask about 2.92x SDE. Only scaled national brands reach double digits.
| Size or segment | Earnings basis | Multiple | Source and date |
|---|---|---|---|
| Revenue under $4M (single site, small) | EBITDA | 3x to 6x | AmSpa / Xite, May 15, 2026 |
| Revenue $4M to $20M (multi-site) | EBITDA | 5x to 8x | AmSpa / Xite, May 15, 2026 |
| Revenue over $20M (regional platform) | EBITDA | 7x to 12x | AmSpa / Xite, May 15, 2026 |
| Revenue under $5M | EBITDA | 3x to 6x | Scope Research, January 23, 2025 (updated May 5) |
| Revenue $5M to $20M | EBITDA | 5x to 8x | Scope Research, 2025 |
| Revenue over $20M | EBITDA | 7x to 12x | Scope Research, 2025 |
| High-growth national platforms | EBITDA | 10x to 20x (a handful of precedent deals) | Scope Research, 2025 |
| Owner-run listings for sale (164 US listings, asking) | SDE | 2.92x median ask | Main Street Index, October 5, 2026 |
| LaserAway sale talk (219 clinics) | EBITDA, derived | about 13.3x ($2 billion over about $150 million) | Reuters via Private Equity Wire, June 2026; process ended per PitchBook, October 14, 2026 |
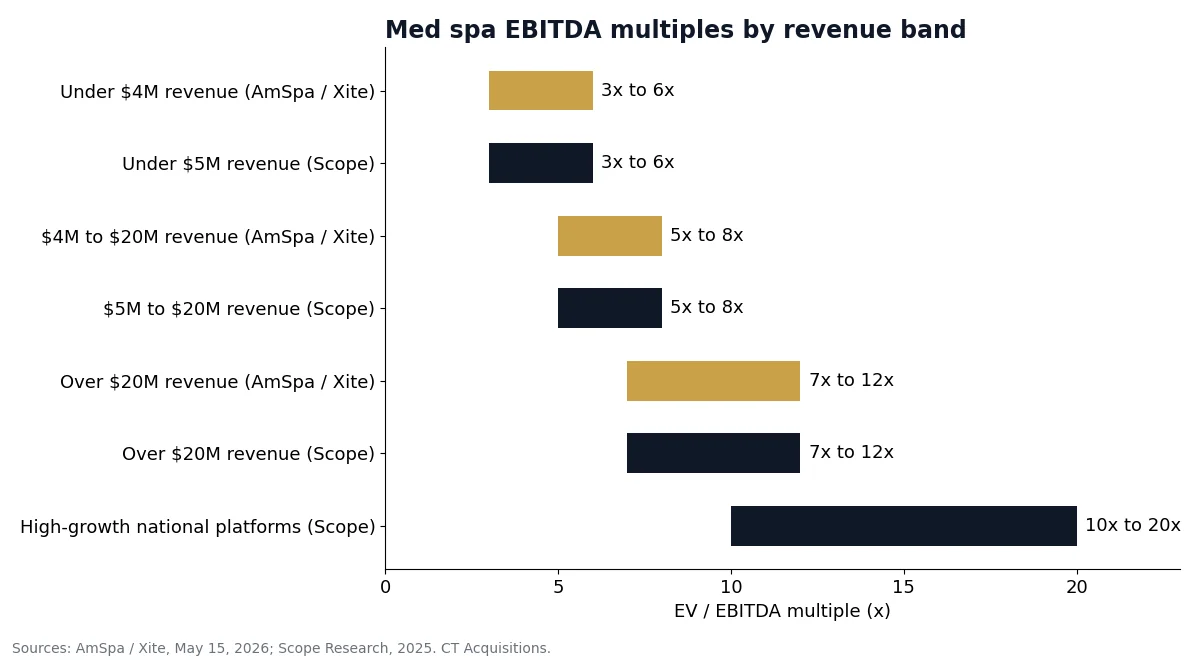
Two cautions on the table. The AmSpa and Scope bands are set by revenue, not by EBITDA, so a $3M spa with a 25% margin and one with a 10% margin sit in the same band at very different values. The Main Street Index figure is an asking multiple on 164 listings with a median SDE of $192K, not a closing price; listings that named a medical director asked 2.85x against 2.96x without one.
The LaserAway number is derived, not reported. Reuters said on June 4, 2026 that a sale could value the chain above $2 billion, the roughly $150 million EBITDA figure came from trade write-ups, and PitchBook reported on October 14, 2026 that the process is no longer active. Treat 13.3x as a ceiling for a 219-clinic national brand, not a comp for a single spa.
Is a med spa valued on SDE or EBITDA?
Owner-run single-site spas are priced on seller’s discretionary earnings (SDE), which adds back one owner’s full pay. Groups with a manager and several injectors are priced on adjusted EBITDA, after a market salary for every provider, owner included. The same spa can show $550,000 of SDE and $380,000 of adjusted EBITDA, so always name the basis before quoting a multiple.
| Item | SDE | Adjusted EBITDA |
|---|---|---|
| Who uses it | Individual and SBA-financed buyers of owner-run spas | PE-backed platforms, independent sponsors, strategic groups |
| Owner’s pay | Added back in full | Replaced with market pay for the injector and manager roles |
| Medical director fee | Kept as a cost | Kept at a market rate, even if the owner is the director |
| Rent on a building the owner holds | Adjusted to market | Adjusted to market |
| Typical published multiple | 2.92x median asking (Main Street Index, 2026) | 3x to 12x by size (AmSpa / Xite, 2026) |
Do not blend the two. A practice at the boundary should be modeled twice and negotiated on the stronger basis; a seller who quotes a 5x EBITDA multiple against an SDE figure overstates the price by the owner’s pay times the multiple, and a buyer’s quality of earnings review will find it. Our quality of earnings guide shows what that review tests.
How do you calculate med spa valuation? A worked example
Normalize earnings, pick the basis, apply the band, then bridge to cash. The example below uses Zenoti’s CY2025 median revenue per med spa location of $1.86M and AmSpa’s revenue bands. It is illustrative arithmetic, not an appraisal: a single site lands at $1.14M to $2.28M, and a three-site group at $6.14M to $9.82M.
- Normalize. Start from net income, add back owner pay, interest, depreciation and amortization, and one-time or personal costs. That gives SDE.
- Pick the basis. For a platform buyer, subtract market pay for the work the owner does (lead injector, manager). That gives adjusted EBITDA.
- Apply the band. Use the revenue band from AmSpa and Xite, then move up or down with the drivers in the next section.
- Bridge to proceeds. Enterprise value minus debt, plus or minus the working capital adjustment, then split into cash at close and rollover equity.
| Line (illustrative) | Single-site spa | Three-site group |
|---|---|---|
| Revenue | $1,860,000 (Zenoti CY2025 median) | $5,580,000 (three median sites) |
| Net income | $260,000 | n/a |
| Add back owner salary | $180,000 | n/a |
| Add back one-time and personal costs | $50,000 | n/a |
| Add back interest, depreciation, amortization | $60,000 | n/a |
| SDE | $550,000 | n/a |
| Less market pay for the owner’s roles | $170,000 | n/a |
| Adjusted EBITDA | $380,000 (20.4% margin) | $1,227,600 (22% margin) |
| AmSpa / Xite band | 3x to 6x (under $4M revenue) | 5x to 8x ($4M to $20M revenue) |
| Enterprise value range | $1,140,000 to $2,280,000 | $6,138,000 to $9,820,800 |
| Midpoint multiple and value | 4.5x = $1,710,000 | 6.5x = $7,979,400 |
| 60% cash at close | $1,026,000 | $4,787,640 |
| 40% rollover equity | $684,000 | $3,191,760 |
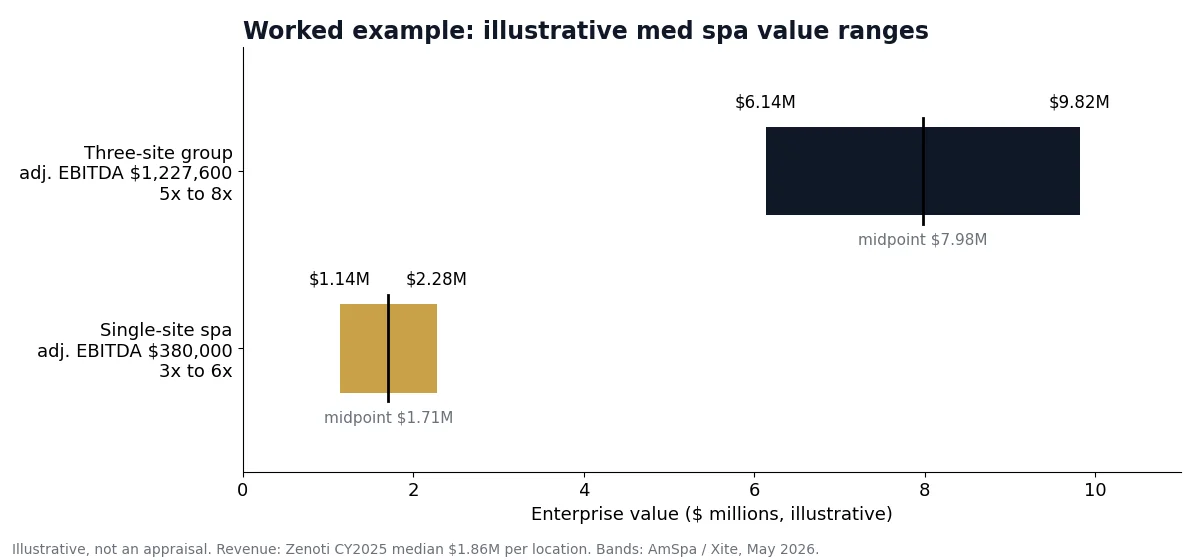
The single site clears Skytale’s 20% adjusted EBITDA margin line but sits far below its $1 million EBITDA mark for competitive valuations, which is why it lands in the 3x to 6x band. The three-site group crosses $1 million and enters the 5x to 8x band. Moving from the midpoint to the top of each band is worth $570,000 for the single site and $1,841,400 for the group, which is the money the drivers below decide.
What raises or lowers a med spa’s multiple?
Provider independence, recurring revenue, margin and clean compliance files move a med spa within its band. Skytale names clinician retention, membership penetration, geographic density and data quality as the drivers of its 30% to 100% premium, and it sets hard investor lines: EBITDA above $1 million, gross profit above 65% and adjusted EBITDA above 20%.
| Driver | Buyer threshold | Effect on value | Source |
|---|---|---|---|
| Scale | Annual EBITDA above $1 million | Below it, fewer competitive bids | Skytale / Qsight, Dec 2025 |
| Gross profit | Above 65%, excluding direct labor | Below it, buyer questions pricing and product cost | Skytale / Qsight |
| Adjusted EBITDA margin | Above 20%; 20% to 30% seen as resilient | Thin margins pull toward the low end of the band | Skytale / Qsight |
| Patient retention | 50% of new patients, up to 80% of returning patients | Higher retention supports recurring-revenue credit | Skytale / Qsight |
| Repeat-patient benchmark | 73% repeat patients is the industry average | Below average reads as a transactional spa | AmSpa 2024 report |
| Service mix | About 60% injectables, rest across devices, skincare, weight loss | A heavy medical weight loss mix “makes investors nervous” | Skytale / Qsight |
| Site count | 3 to 8 or more sites | Draws the most competitive interest | AmSpa / Xite, May 2026 |
| Compliance files | Medical director, injector supervision and MSO documents in order | Gaps cut price or stall diligence, mostly in California | AmSpa / Xite, May 2026 |
| Sale process | Several bidders, not one unsolicited offer | A 126% gap between lowest and highest bid in one Bundy Group dermatology sale | Practical Dermatology, Sept 2025 |
Owner dependence is the most common reason a small spa sits at 3x rather than 6x. AmSpa and Xite say owner dependence and operational concentration push smaller spas to the low end, and Skytale adds that patients should be loyal to the brand, not to one provider. Our note on how owner dependency affects valuation shows how buyers test it.
Which treatments are buyers paying for?
Neurotoxins are the growth line buyers pay for: US neurotoxin patient spend rose 8% to $6.4 billion in 2024 while the non-surgical market grew 5% to $20.5 billion, per Qsight. Body contouring fell 22% and laser hair removal 9%, so a device-heavy spa carries more demand risk than an injector-led one.
| Category | 2024 US patient spend | Change vs 2023 | Source |
|---|---|---|---|
| All non-surgical aesthetics | $20.5 billion | +5% | Skytale / Qsight, Dec 2025 |
| Neurotoxins | $6.4 billion | +8% | Skytale / Qsight |
| Dermal fillers | $3.8 billion | -3% | Skytale / Qsight |
| Hyaluronic acid fillers | $3.0 billion | -4% | Skytale / Qsight |
| Biostimulatory fillers | $787 million | +4% | Skytale / Qsight |
| Energy-based devices | $3.6 billion | -5% | Skytale / Qsight |
| Skin tightening | n/a | +6% | Skytale / Qsight |
| Laser hair removal | n/a | -9% | Skytale / Qsight |
| Body contouring | n/a | -22% | Skytale / Qsight |
| Medical weight loss (mostly compounded GLP-1) | 11% of spend | +55% (after +235% in 2023) | Skytale / Qsight |
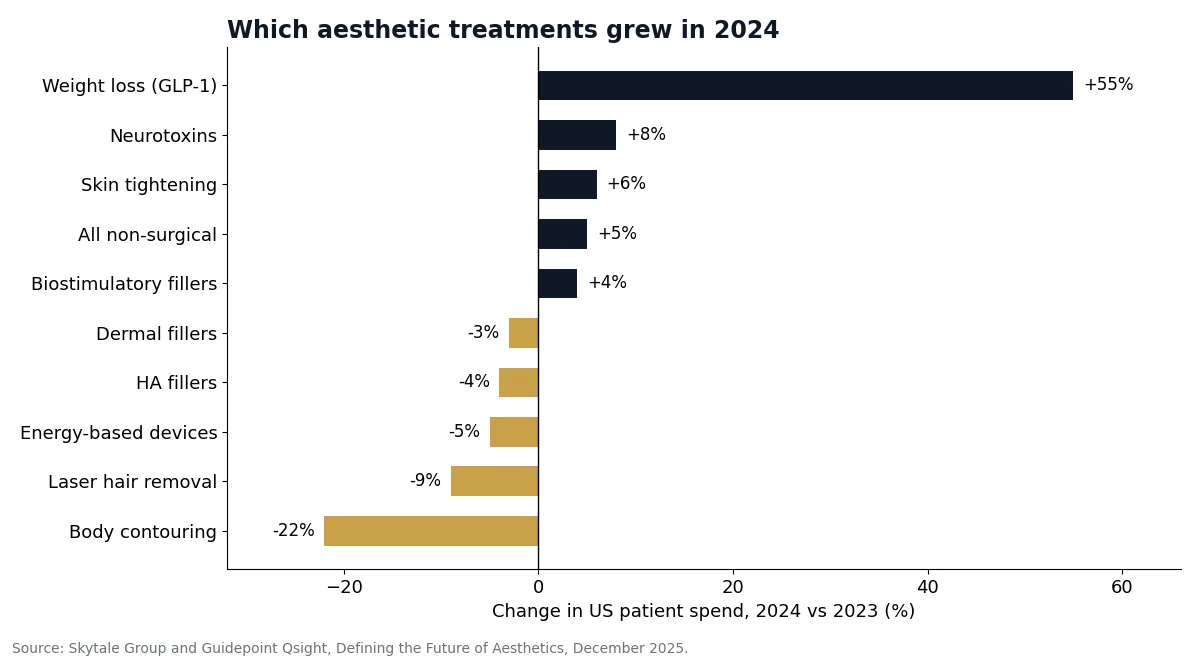
Supplier results through Q3 2026 point the same way. AbbVie reported US Botox Cosmetic net revenue of $388M, up 2.4%, and US Juvederm at $90M, down 6.3%, for Q3 2026, and Galderma reported neuromodulator sales up 16.9% at constant currency for the first nine months of 2026. A spa whose revenue leans on HA filler or one device is selling into the weakest lines.
Who is buying med spas in 2026, and who owns the big platforms?
Private equity platforms are the main buyers, but they own little of the market: AmSpa’s 2024 report puts PE ownership at 3% of med spas and single-location spas at 81%. The table lists each platform’s sponsor with the dated release behind it, so an owner can check who is behind an offer before taking a call.
| Platform | Sponsor | Dated event | Source |
|---|---|---|---|
| Ideal Image | L Catterton (majority); TPG Growth (minority) | L Catterton bought parent Steiner Leisure in 2015; TPG Growth invested May 11, 2021 | TPG release, Business Wire |
| Milan Laser Hair Removal | Leonard Green & Partners; Sixth Street and Wildcat Capital (growth) | LGP since 2019; Sixth Street and Wildcat invested February 22, 2023, LGP and co-founders keep majority | Leonard Green release |
| LaserAway | Ares Management; Seidler Equity Partners | Seidler since 2018; Ares invested October 21, 2021; sale explored June 2026, process ended per PitchBook October 14, 2026 | LaserAway release, Business Wire |
| SkinSpirit | KKR (minority, Health Care Strategic Growth Fund II); GreyLion (minority since 2018) | KKR investment announced October 20, 2022 | SkinSpirit release, Business Wire |
| VIO Med Spa (franchisor) | Freeman Spogli (majority) | Announced September 16, 2024 | VIO release, PR Newswire |
| Advanced MedAesthetic Partners (Avelure, Ever/Body) | Leon Capital Group | Acquired Ever/Body, December 2025 (PitchBook data) | Edgepoint flash report, March 2026 |
| Alpha Aesthetics Partners | Thurston Group | 37 locations; $93 million Manulife-led debt; sale under consideration, October 14, 2026 | PitchBook via Yahoo Finance |
| MD Esthetics | New Harbor Capital | Four add-ons took it from 12 to 35 locations, September 16, 2026 | PR Newswire |
| Aviva Aesthetics | DuneGlass Capital | Muse Med Spa, its 11th partnership of 2026, September 16, 2026 | Aviva newsroom |
| Olympus Cosmetic Group | VSS Capital Partners | Gallaher Plastic Surgery & Med Spa, September 9, 2026 | PR Newswire |
| Elase Medical Spas | Imperial Capital | Derma Health, Phoenix metro, July 2026 | AZ Big Media, July 31, 2026 |
| Cosmetic Physician Partners | None stated (practitioner-owned) | About $35 million distribution to practitioner-owners, July 22, 2026 | PR Newswire |
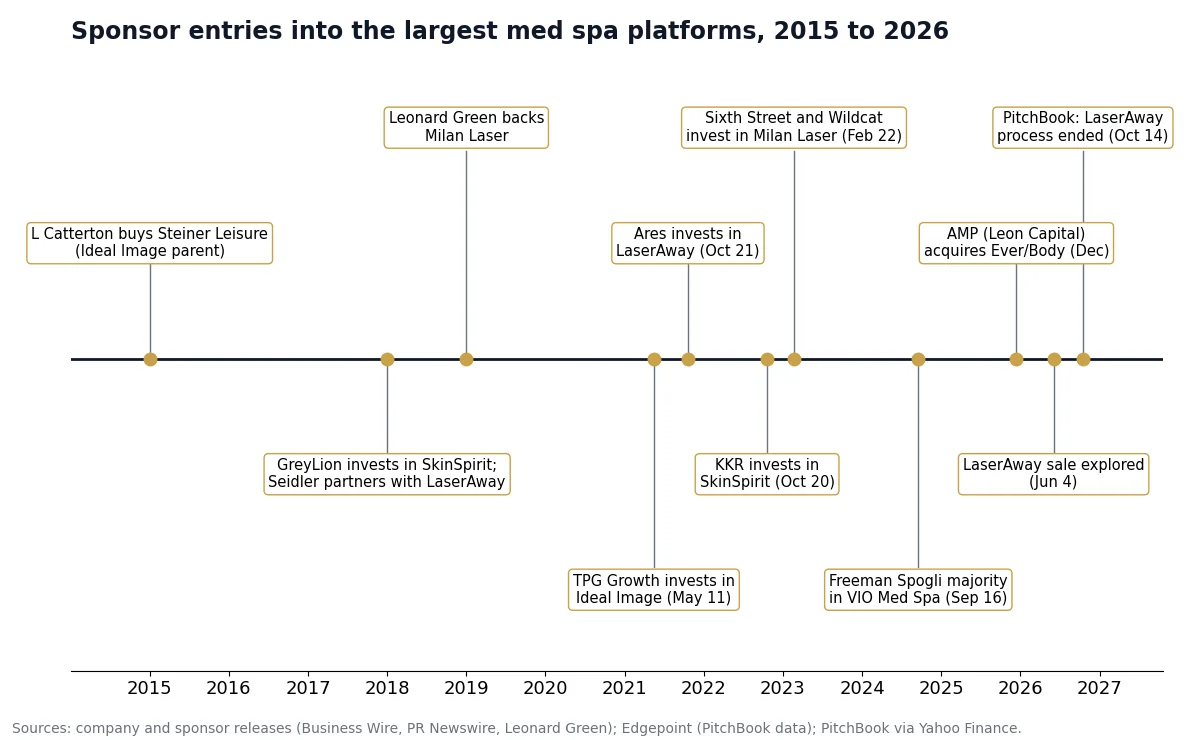
CT’s Q3 2026 deal file, compiled from press releases and company newsrooms for our Medspa Market Report, counted 16 announced entries covering 19 transactions between July 1 and September 30, 2026, and 0 disclosed a price or multiple. That is why every multiple on this page comes from an advisor benchmark rather than a deal comp. PitchBook expects as many as 25 med spa platforms to come to market in 2027 and 2028, which would add the first scaled comps.
What deal structure should a med spa owner expect?
Expect part of the price in cash and part in the buyer’s equity. AmSpa and Xite report about 60% cash at close and 40% rollover equity in most 2025 deals, rising to 80% cash and 20% rollover, with holdbacks and earnouts common where provider transition matters. Compare offers on cash at close, not headline value.
| Term | Typical range or example | Source |
|---|---|---|
| Cash at close | About 60%, up to 80% | AmSpa / Xite, May 15, 2026 |
| Rollover equity | About 40%, down to 20% | AmSpa / Xite, May 15, 2026 |
| Rollover example | Sell 70%, roll 30% into the platform | AmSpa / Xite, August 14, 2026 |
| Seller note example | 80% at close, 20% as a seller note | AmSpa / Xite, August 14, 2026 |
| Holdbacks and earnouts | Common where future performance or provider transition is key | AmSpa / Xite, May 15, 2026 |
Rollover equity pays only when the platform sells, so its value depends on the sponsor’s exit; our founder rollover equity benchmarks cover the terms to negotiate. Earnouts tied to EBITDA or patient retention shift risk back to the seller, and the earnout benchmarks by deal size show common lengths and triggers.
How do CPOM and state laws affect med spa valuation?
Corporate practice of medicine (CPOM) rules decide who may own the medical side of a med spa, so they decide which buyers can bid and how the deal is built. California SB 351 took effect January 1, 2026, Oregon SB 951 applies to new MSO deals from January 1, 2026, and a federal bill introduced September 16, 2026 would extend similar limits nationally.
| Rule | Key dates | What it does | Effect on a sale |
|---|---|---|---|
| California SB 351 | Signed October 6, 2025; effective January 1, 2026 | Bars PE and management firms from interfering with clinical judgment; voids certain MSO contract terms | California MSO and friendly-PC agreements get re-reviewed in diligence |
| California AB 1415 | Signed October 11, 2025 | PE groups, hedge funds and MSOs must give at least 90 days’ notice of covered deals to the Office of Health Care Affordability | Adds at least 90 days to the timeline for covered deals |
| Oregon SB 951 | Signed June 9, 2025; new and sold structures from January 1, 2026; older structures by January 1, 2029 | Bans MSO control of medical groups; limits noncompetes; private right of action | A sale after June 9, 2025 triggers the 2026 rules, not the 2029 grace period |
| Texas HB 3749 | Signed June 20, 2025; effective September 1, 2025 | Elective IV therapy needs a prior evaluation and an order from a physician or delegated PA or NP | IV revenue without those records is a diligence finding |
| FDA 503B bulks proposal | Federal Register, May 1, 2026 | Proposes removing semaglutide, tirzepatide and liraglutide from the 503B bulks list | Compounded GLP-1 revenue is treated as at-risk |
| Federal practice-ownership bill | Introduced September 16, 2026; in committee | Would require majority ownership by licensed professionals and limit MSO control | A watch item for MSO-based buyers if it moves |
The dermatology side of the market faces the same CPOM rules with insurance billing on top; the dermatology M&A multiples report compares the two, and the healthcare services multiples report places both in the wider sector.
Should you sell your med spa now or fix it first?
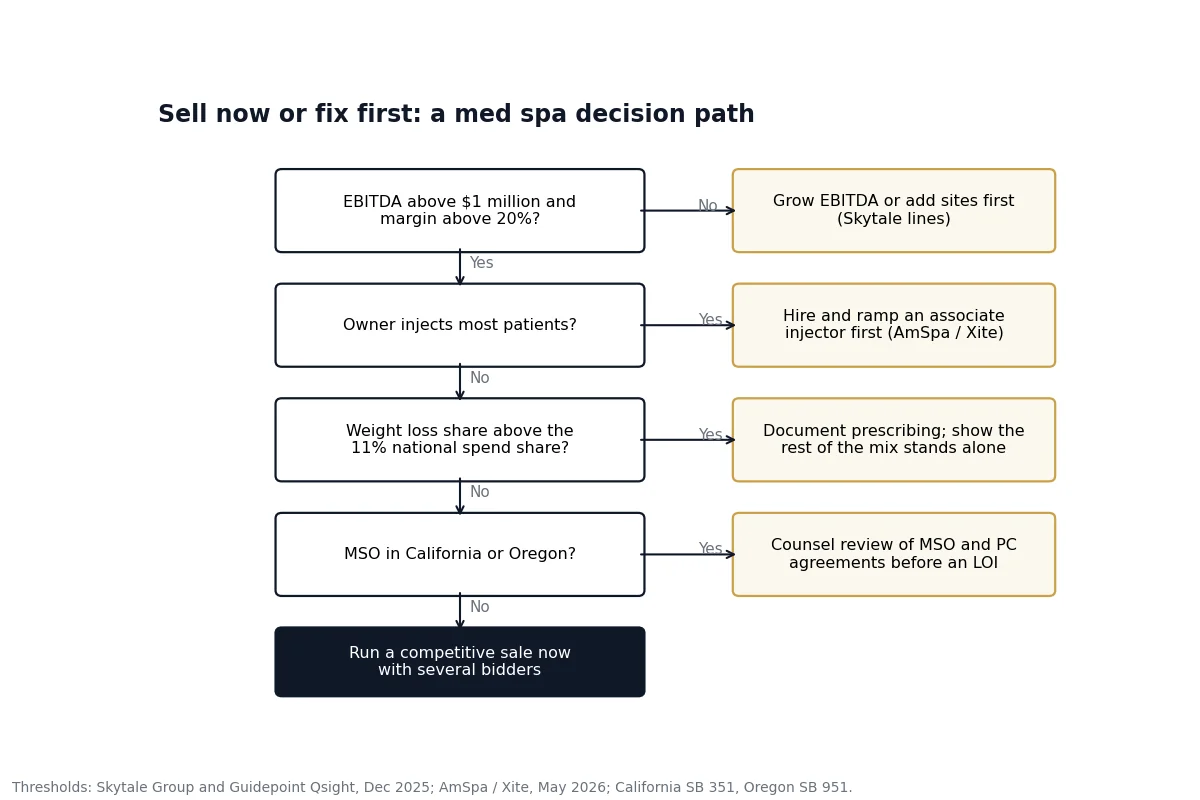
Sell now if the spa already meets the buyer thresholds; fix first if one gap would move it a full band. The decision table uses the Skytale and AmSpa lines above. If your situation matches a row, the right-hand column is the next step, and the time it takes is the cost of waiting.
| If your situation is | Then | Why (source) |
|---|---|---|
| If EBITDA is above $1 million, margin above 20% and no provider carries the book | Run a competitive sale now with several bidders | Meets Skytale’s investor lines; bids in one Bundy Group sale ranged 126% apart |
| If you run 3 to 8 sites in Florida, Texas or California | Approach platforms and new sponsors together | AmSpa / Xite name these as the most active states and site counts |
| If you inject most of the patients yourself | Hire and ramp an associate injector before going to market | Owner dependence pushes small spas to the low end of 3x to 6x (AmSpa / Xite) |
| If medical weight loss is a larger share of revenue than the 11% national spend share | Show the rest of the mix stands alone; document prescribing and sourcing | Skytale: a heavy weight loss mix makes investors nervous; FDA 503B proposal, May 2026 |
| If you operate in California or Oregon through an MSO | Have counsel review the MSO and PC agreements before an LOI | SB 351 (CA) and SB 951 (OR) apply to 2026 deals |
| If repeat patients are below the 73% average | Build memberships and treatment plans first | AmSpa 2024 benchmark; Skytale retention lines of 50% and 80% |
The step-by-step sale process (data room, confidential outreach, comparing letters of intent) is in our guide on how to sell a med spa, and the advisor side is on our M&A advisor for med spas page.
Thinking about selling your med spa? CT Acquisitions helps owners of founder-owned businesses make the most of their exit through a confidential sale, recapitalization or exit planning, with a 500+ buyer network. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells.
Book a confidential call to see where your EBITDA, provider mix and state rules place you against the bands above.
How we compiled this
We compiled this page in November 2026 from 30 dated documents: AmSpa industry reports and articles, the Skytale Group and Guidepoint Qsight report, Scope Research, Zenoti benchmark data, sponsor and company press releases, AbbVie and Galderma results, statute pages and law firm alerts. Multiples come only from named advisor or data sources, and the deal record comes from CT’s Q3 2026 Medspa Market Report file. We excluded forum posts and any multiple we could only see in a search snippet. Nothing here is an appraisal of any business.
Frequently asked questions
What is the EBITDA multiple for a med spa?
Med spas sold for about 3x to 6x EBITDA under $4M of revenue, 5x to 8x at $4M to $20M and 7x to 12x above $20M in 2025, per AmSpa and Xite (May 15, 2026). Scope Research reports the same bands and 10x to 20x for a handful of high-growth national platforms.
How much money does a med spa owner make?
The average US med spa brought in $1,398,833 of revenue in 2023, per AmSpa’s 2024 report, and Zenoti puts the CY2025 median at $1.86M per location. Skytale says well-run spas earn adjusted EBITDA margins of 20% to 30%, so owner earnings before their own pay often run several hundred thousand dollars.
Is private equity buying med spas?
Yes, but slowly. AmSpa’s 2024 report puts private equity ownership at 3% of med spas, and Skytale expects about 10% total consolidation over the next 4 to 5 years. Active 2026 buyers include MD Esthetics (New Harbor Capital), Aviva Aesthetics (DuneGlass Capital) and Olympus Cosmetic Group (VSS Capital Partners).
How profitable are medical spas?
Skytale and Guidepoint Qsight say consistent margins of 20% to 30% are possible, and private equity buyers look for gross profit above 65% and adjusted EBITDA above 20%. AmSpa’s 2024 report shows $527 average spend per visit and 73% repeat patients, the two numbers that drive that margin.
Who owns a med spa?
Most med spas are owner-run: AmSpa’s 2024 report counts 81% as single-location businesses and 3% as private equity owned. In states with corporate practice of medicine rules, such as California, the medical side must be owned by a licensed professional, and investors hold the business side through a management services organization.
Did LaserAway sell?
No sale had been announced as of November 2026. Reuters reported on June 4, 2026 that Ares-backed LaserAway was exploring a sale that could value it above $2 billion, and PitchBook reported on October 14, 2026 that the process is no longer active.
Sources
All sources accessed November 2026.
- AmSpa, Tommy Newton (Xite): Med Spa M&A and Private Sales, May 15, 2026
- AmSpa, Tommy Newton (Xite): Private Equity, Platforms, Roll-Ups, EBITDA, and Multiples, August 14, 2026
- AmSpa: 2024 Medical Spa State of the Industry Executive Report recap, November 6, 2024
- Skytale Group and Guidepoint Qsight: Defining the Future of Aesthetics, December 2025
- Scope Research: Med Spa and Aesthetics Valuation Multiples and M&A Trends, 2025
- Zenoti: 2026 Beauty and Wellness Benchmark Report, Medspa Edition, April 29, 2026
- Main Street Index: Buying a Med Spa, October 5, 2026
- Private Equity Wire (Reuters): LaserAway weighs sale, June 2026
- PitchBook via Yahoo Finance: Thurston Group explores sale of Alpha, October 14, 2026
- AbbVie: Third-Quarter 2026 Financial Results, October 30, 2026
- Galderma: Q3 2026 results, October 22, 2026
- Practical Dermatology: M&A in Derm and Aesthetics, September 2025
- Sponsor releases: TPG / Ideal Image (May 11, 2021), Milan Laser (February 22, 2023), LaserAway (October 21, 2021), SkinSpirit (October 20, 2022), VIO Med Spa (September 16, 2024)
- Statutes and rules: California SB 351, Oregon SB 951 (Davis Wright Tremaine), Federal Register, May 1, 2026
Observed ranges reported by third-party sources. Not an appraisal, not investment, legal, tax or financial advice.
Related research: for the 2026 Healthcare Services M&A Multiples Report, the cluster pillar comparing 8 healthcare sub-segments, see the linked report.
Related research: for the 2026 Dermatology M&A Multiples Report, adjacent sibling with distinct axis (derm insurance + medical + cosmetic mix; med spa 100% cash-pay), see the linked report.
Related research: for the 2026 Optometry Practice M&A Multiples Report, sibling healthcare specialty spoke, see the linked report.
Related research: for the 2026 Physical Therapy Practice M&A Multiples Report, sibling healthcare specialty spoke, see the linked report.
