
Veterinary Practice Valuation Multiples 2026: M&A Benchmarks by Size and Segment
Veterinary practice valuation multiples run about 5x to 8x EBITDA for sole-provider practices and 13x to 15x or more for top-tier groups, per CLA Meridian Capital’s Q2 2026 veterinary update.
Key takeaways
- The average veterinary EBITDA multiple was 12.3x in the first half of 2026, down from a 14.9x peak in the second half of 2021 (CLA Meridian Q2 2026, IDEXX data).
- Size sets the band: general practices traded at 5.3x EBITDA at $500K to $1M, 8.6x at $1M to $5M and 11.3x at $5M to $10M in Q1 2025 (First Page Sage).
- Mars paid $93.00 a share for VCA in 2017, about $9.1 billion with debt, which was above the value Barclays derived at 19.0x LTM adjusted EBITDA (VCA merger proxy).
- Supply has thinned: about 350 veterinary hospitals sold in 2024 and 357 in 2025, against 1,550 in 2021 (CLA Meridian Q2 2026).
- Consolidator offers are rarely all cash: one veterinary broker reports 60% to 80% cash at closing, 10% to 25% earnouts and 10% to 30% rollover equity (Transitions Elite).

What EBITDA multiples do veterinary practices sell for in 2026?
Most published 2025 to 2026 sources put veterinary practices between 3.5x and 15x EBITDA, and the spread is explained by size and doctor count. CLA Meridian Capital’s Q2 2026 update gives 5.0x to 8.0x for sub-scale or sole-provider practices and 13.0x to 15.0x or more for top-tier practices, with a 12.3x average in the first half of 2026.
The table lists every dated range we could trace to a named publisher, with the earnings basis and practice profile each one describes. Read each row only against a practice that matches its profile; a quote for a $1M EBITDA multi-doctor group does not apply to a single-doctor clinic.
| Source and date | Practice profile | Basis | Range |
|---|---|---|---|
| CLA Meridian Capital, Q2 2026 | Sub-scale or sole-provider practice | EBITDA | 5.0x to 8.0x |
| CLA Meridian Capital, Q2 2026 | Top-tier practices and platforms | EBITDA | 13.0x to 15.0x+ |
| DVM Elite, June 2026 | All practices, 2026 projection | EBITDA | 6x to 12x |
| Ad Astra Equity, June 2026 | Under $250K adjusted EBITDA, solo DVM | Adjusted EBITDA | 3.5x to 5.0x |
| Ad Astra Equity, June 2026 | $1M+ adjusted EBITDA, specialty or premium multi-doctor | Adjusted EBITDA | 12.0x to 15.0x |
| Ackerman Group, June 2025 | Sales to corporate buyers | EBITDA | 8x to 13x |
| Red Bike Advisors, undated | Independent companion animal practice | EBITDA | 6x to 10x |
| Red Bike Advisors, undated | Specialty or emergency practice sold to private equity | EBITDA | 12x to 15x |
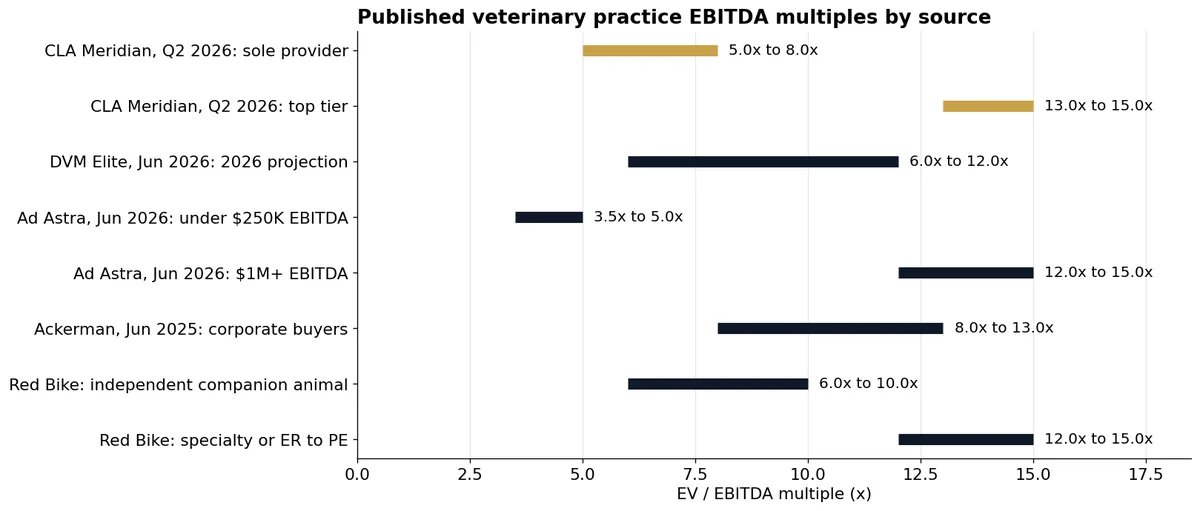
Our sell-process guide for practice owners uses an 8x to 15x EBITDA band for 2026 with 5x to 8x for one or two doctors, which sits inside these sources; the full timeline is in our guide on how to sell a veterinary practice.
Why do published veterinary multiples disagree?
Published veterinary multiples disagree because they measure different practices, earnings and years. A sole-provider clinic at $250K EBITDA and a $1M EBITDA group with specialty referral are both called “a vet practice”, yet Ad Astra Equity prices the first at 3.5x to 5.0x and the second at 12.0x to 15.0x. Before you compare a quote, check four things.
- Earnings basis. SDE adds back the full owner-veterinarian pay, so an SDE multiple is lower than an EBITDA multiple on the same clinic. Buyers in our sources price on adjusted EBITDA, after owner pay is reset to a market wage.
- Size and doctor count. First Page Sage puts a general practice at 5.3x EBITDA at $500K to $1M and 11.3x at $5M to $10M, more than double.
- Buyer type. DVM Elite reports independent veterinarians paying 3x to 5x and corporate buyers 6x to 8x; Ackerman Group reports 8x to 13x for corporate buyers.
- Year. Ackerman Group cites 12x to 18x in 2021 and 8x to 13x in 2023. CLA Meridian’s half-year average fell from 14.9x (second half of 2021) to 11.0x (second half of 2022).
Several popular guides also carry figures that do not match their own arithmetic or the primary record. The table sets each claim against what the source document says.
| Claim seen in published guides | What the primary source says |
|---|---|
| Mars bought VCA at about 14x to 16x LTM EBITDA (stated on this page before November 2026) | VCA’s merger proxy shows $93.00 per share was above the $57.75 to $92.25 per share range Barclays derived at 13.0x to 19.0x LTM adjusted EBITDA to September 30, 2016, so the price implied more than 19x (DEFM14A, Feb 2017) |
| A practice at 5x on $300,000 EBITDA “could sell for 15 million” (DVM Elite, June 2026) | 5 x $300,000 = $1.5M; the same article’s $750,000 example at 5x is $3.75M, not $37.5M |
| About 4.9M insured pets in the US at year-end 2024 (stated on this page before November 2026) | NAPHIA counts 7.03 million insured pets in North America at year-end 2024 and 7.6 million at year-end 2025 |
| Ethos Veterinary Health is held by BC Partners or Cerberus (stated on this page before November 2026) | The FTC reviewed JAB’s $1.65 billion purchase of Ethos’s parent in 2022 |
How do multiples change with practice size and specialty?
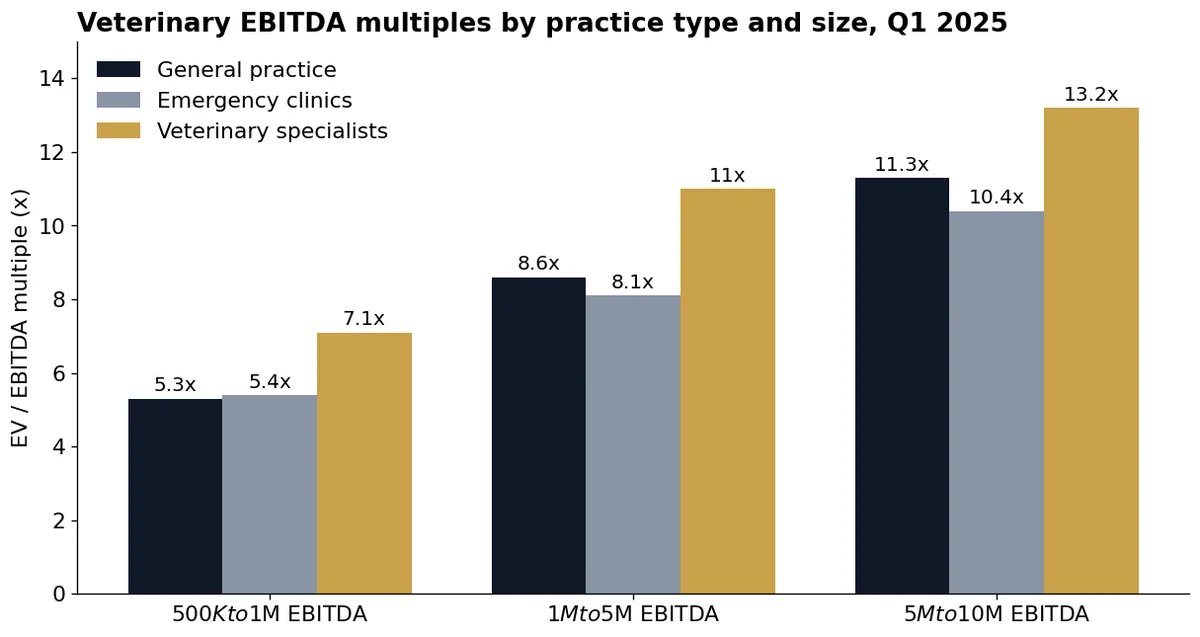
Veterinary multiples step up with EBITDA size in every practice type. In First Page Sage’s Q1 2025 study, a general practice moves from 5.3x at $500K to $1M EBITDA to 8.6x at $1M to $5M and 11.3x at $5M to $10M. Veterinary specialists carry the highest figures in each band: 7.1x, 11x and 13.2x.
| Practice type (Q1 2025) | $500K to $1M EBITDA | $1M to $5M EBITDA | $5M to $10M EBITDA |
|---|---|---|---|
| General practice | 5.3x | 8.6x | 11.3x |
| Emergency clinics | 5.4x | 8.1x | 10.4x |
| Veterinary specialists | 7.1x | 11x | 13.2x |
| Exotic animal clinics | 6.6x | 10x | 12.9x |
| Livestock, food and large animal | 6.2x | 10.4x | 12.8x |
Source: First Page Sage, published January 7, 2025, a meta-analysis drawing on private equity networks, proprietary databases and valuation interviews. The same study gives revenue multiples for general practice of 1.6x at $1M to $3M revenue, 2.2x at $3M to $10M and 2.9x at $10M to $50M.
Doctor count is the operational version of size. Ad Astra Equity ties its bands to it: 3.5x to 5.0x for a solo DVM under $250K adjusted EBITDA, 6.0x to 7.5x for two DVMs at $250K to $500K, and 8.0x to 12.0x for three or more DVMs at $500K to $1M. For specialty and emergency hospitals, our guide to selling a veterinary specialty hospital covers the referral-network buyers.
How have veterinary multiples moved since 2017?
The average veterinary EBITDA multiple rose from 7.5x in the first half of 2017 to a 14.9x peak in the second half of 2021, fell to 10.9x in the first half of 2023, and has held between 12.3x and 12.5x since the second half of 2024, per CLA Meridian Capital’s Q2 2026 chart built on IDEXX data.
| Half year | Average EV/EBITDA | Half year | Average EV/EBITDA |
|---|---|---|---|
| 1H17 | 7.5x | 2H21 | 14.9x |
| 2H17 | 10.4x | 1H22 | 13.9x |
| 1H18 | 11.0x | 2H22 | 11.0x |
| 2H18 | 10.0x | 1H23 | 10.9x |
| 1H19 | 10.6x | 2H23 | 11.4x |
| 2H19 | 10.5x | 1H24 | 11.8x |
| 1H20 | 9.9x | 2H24 | 12.3x |
| 2H20 | 10.9x | 1H25 | 12.5x |
| 1H21 | 12.5x | 2H25 | 12.4x |
| 1H26 | 12.3x |
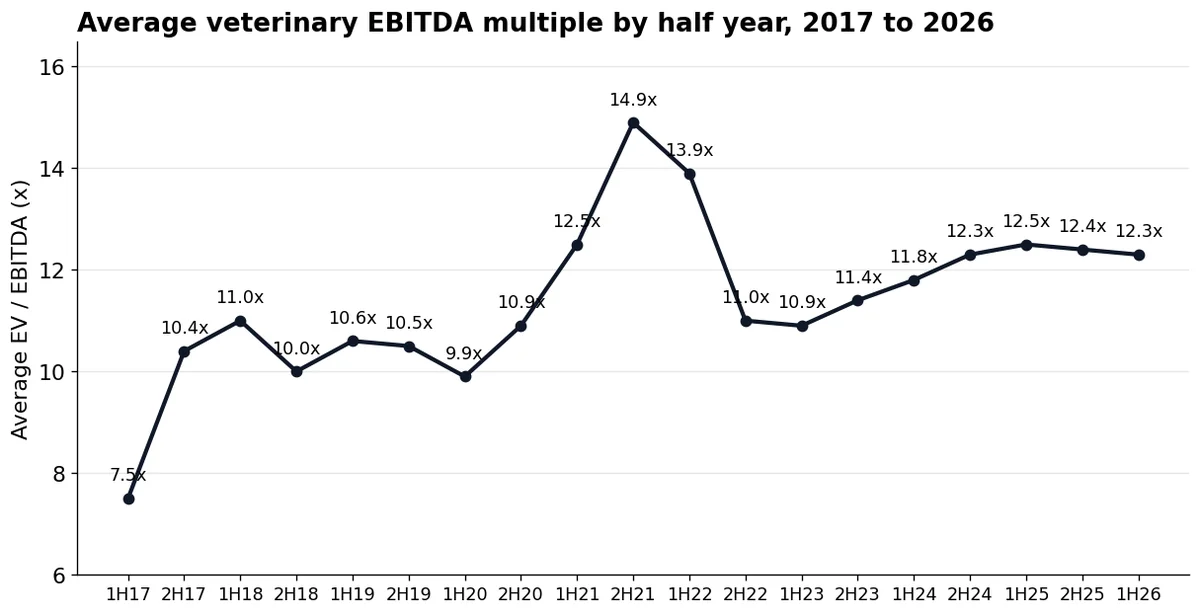
The 1H26 figure of 12.3x is 2.6 turns, or about 17%, below the 2H21 peak. These are averages of reported deals, which skew toward larger groups that disclose terms, so a sole-provider clinic should read the 5.0x to 8.0x band, not the average.
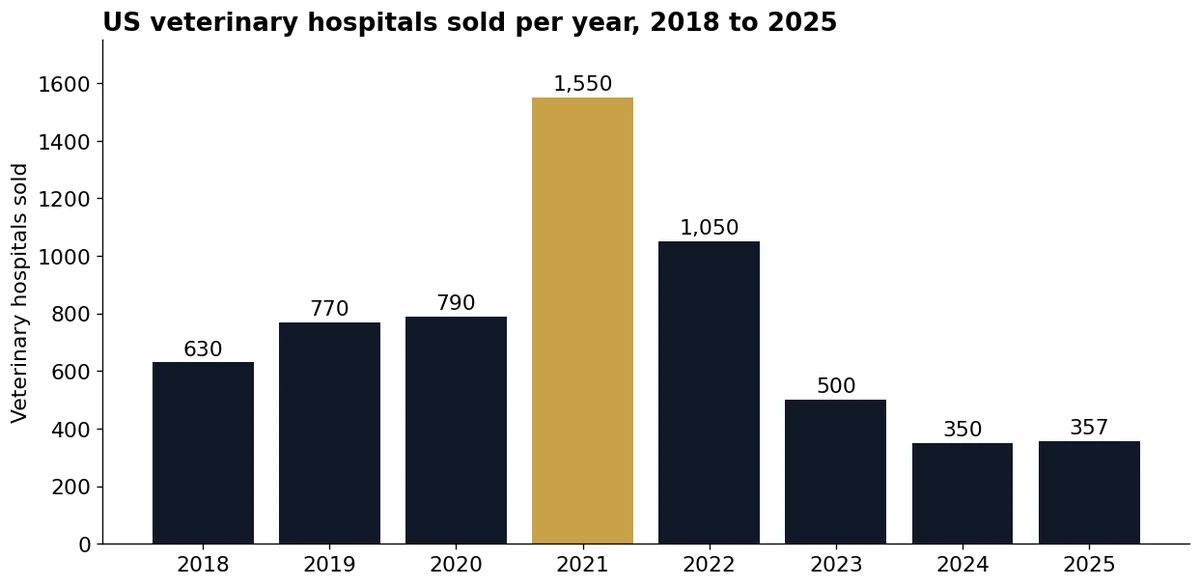
Deal counts fell faster than prices. CLA Meridian counts veterinary hospitals sold per year as follows, and notes that invoice volume has declined for four consecutive years by at least about 2% to 3% a year.
| Year | 2018 | 2019 | 2020 | 2021 | 2022 | 2023 | 2024 | 2025 |
|---|---|---|---|---|---|---|---|---|
| Hospitals sold | 630 | 770 | 790 | 1,550 | 1,050 | 500 | 350 | 357 |
What have consolidators paid in disclosed veterinary deals?
Few veterinary deals publish both a price and earnings, so the platform-level record is thin but checkable. Mars paid more than 19x LTM adjusted EBITDA for VCA in 2017, Partners Group paid a reported 15.0x for Blue River PetCare in 2024, and Chewy paid at most 3.2x run-rate revenue for Modern Animal in 2026.
| Date | Buyer (sponsor) | Target | Disclosed terms | Implied metric |
|---|---|---|---|---|
| Jan 2017 | Mars | VCA Inc. | $93.00 per share, about $9.1B incl. $1.4B debt (proxy); FTC required 12 clinic divestitures (FTC) | Above 19.0x LTM adjusted EBITDA |
| Dec 2017 (closed Jan 2018) | KKR | PetVet Care Centers, about 125 hospitals | Price not disclosed (OTPP) | Not disclosed |
| Jul 2018 | Oak Hill Capital (lead) | VetCor recap, 272 hospitals | Not disclosed (Harvest Partners) | Not disclosed |
| Jun 2019 | JAB | National Veterinary Associates, 670+ hospitals | Not disclosed (Ares) | Not disclosed |
| Apr 2020 | TSG Consumer Partners | Pathway Vet Alliance, now Thrive Pet Healthcare, 270+ hospitals | Majority stake (Ropes & Gray) | Not disclosed |
| Jun 2022 | JAB (NVA) | SAGE Veterinary Partners, 16 clinics | $1.1B (FTC) | About $68.75M per clinic |
| Jun 2022 | JAB (NVA) | Ethos Veterinary Health parent | $1.65B (FTC) | Not disclosed |
| Mar 2022 | AEA Investors | AmeriVet Veterinary Partners | EV $1,600M (CLA Meridian, PitchBook data) | 7.1x revenue |
| Jul 2024 | Partners Group | Blue River PetCare | EV $1,500M (CLA Meridian, PitchBook data) | 15.0x EBITDA |
| Dec 2024 | Shore Capital and Silver Lake | Southern Veterinary Partners and Mission Veterinary Partners, now Mission Pet Health, 730+ practices | $8.6bn reported (Private Equity Wire, Bloomberg) | About $11.8M per practice |
| May 2026 | Chewy | Modern Animal, 29 clinics, $125M+ run-rate revenue | $399.8M (Chewy 10-Q) | At most 3.2x revenue; $13.8M per clinic |
Two cautions apply to this ledger. Per-clinic prices for SAGE and Modern Animal reflect specialty hospitals and platforms, not a typical general practice. And the Barclays precedent set in the VCA proxy, which included PetVet (2015) and NVA (2014), ran from 9.9x to 19.3x LTM adjusted EBITDA with a 13.8x median, which shows how wide even platform prices were before the 2021 peak.
Which groups own the most US locations in 2026?
Mars, JAB and Shore Capital control the three largest location counts in the US. The Private Equity Vet database, updated October 24, 2026, lists Banfield (Mars) at 1,019 locations, NVA (JAB) at 1,017 and Mission Pet Health (Shore) at 984. By one estimate cited by the FTC chair in 2022, consolidators held close to 50% of companion animal practice revenue.
| Group | Owner or lead sponsor | Listed US locations (Oct 2026) |
|---|---|---|
| Banfield | Mars | 1,019 |
| National Veterinary Associates | JAB | 1,017 |
| Mission Pet Health | Shore Capital, Silver Lake | 984 |
| VetCor | Oak Hill Capital (2018 recap lead) | 886 |
| VCA | Mars | 859 |
| PetVet Care Centers | KKR | 439 |
| Thrive Pet Healthcare | TSG Consumer Partners | 362 |
Buyer health matters as much as size. Thrive reported $46 million of Q2 2026 adjusted EBITDA while its first-lien PIK loan priced at 80.17 and Moody’s rated it Caa3 (Octus, Sep 2026), so rollover equity in a stretched platform carries more risk than the headline multiple shows. Sponsor hold periods and each platform’s history are in our veterinary private equity report.
How do you calculate a veterinary practice valuation from a multiple?
Veterinary practice valuation is adjusted EBITDA times a market multiple. Reset the owner-veterinarian’s pay to a market wage, add back one-time and personal costs, charge market rent, then apply the multiple for your size and profile. The BLS median veterinarian wage was $130,100 in May 2025, a usable floor for the reset.
Illustrative worked example: a three-DVM general practice reports $1,050,000 of EBITDA and pays the owner-veterinarian $250,000. The numbers are hypothetical; the multiples come from the sources named in each row.
| Step | Input | Result |
|---|---|---|
| 1. Reported EBITDA | From the P&L | $1,050,000 |
| 2. Owner pay reset | $250,000 paid minus $130,100 market wage (BLS May 2025) | +$119,900 |
| 3. Adjusted EBITDA | $1,050,000 + $119,900 | $1,169,900 (about $1.17M) |
| 4a. Floor case | 5.0x, CLA Meridian sole-provider floor | $5.85M |
| 4b. Base case | 8.6x, First Page Sage general practice at $1M to $5M | $10.06M |
| 4c. Top-tier case | 13.0x, CLA Meridian top-tier floor | $15.21M |
| 5. Structure of base case | 70% cash, 20% rollover, 10% earnout (inside Transitions Elite ranges) | $7.04M cash, $2.01M rollover, $1.01M earnout |
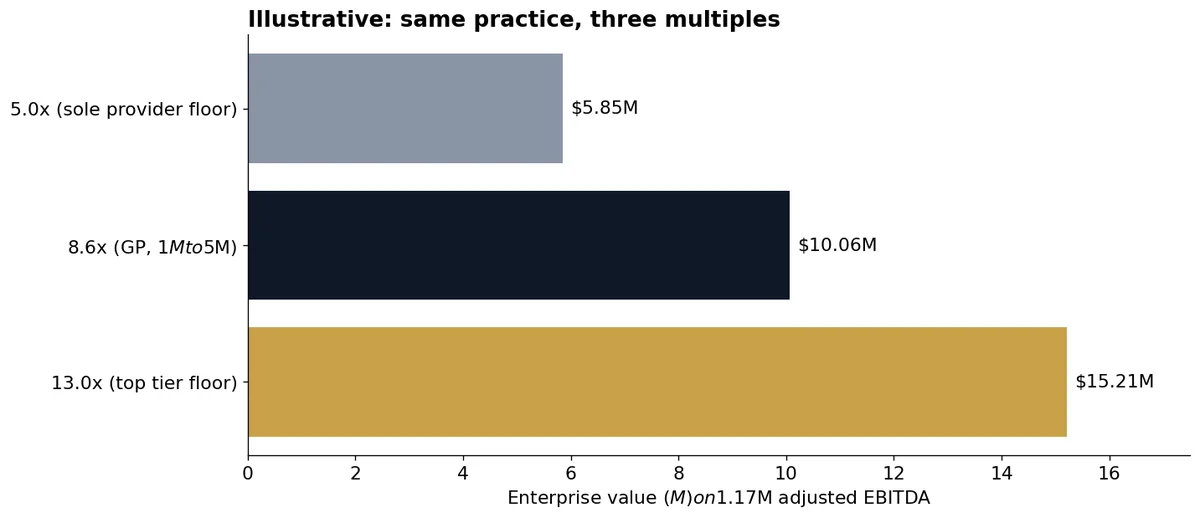
The $9.36M gap between the floor and top-tier cases is the reason to run more than one buyer. Our veterinary practice valuation calculator gives a first range in a few minutes; a quality of earnings review, covered on our QoE page, tests the add-backs before a buyer does.
Does owning the building change the multiple?
Owning the building lowers the practice-only number but can raise total proceeds. A buyer charges market rent against EBITDA, then values the property separately at a cap rate. In July 2026, FCPT bought 102 Mission Pet Health veterinary properties for $268.0 million on about $17.37 million of rent, an implied cap rate of about 6.5% (FCPT).
Illustrative: a $150,000 market rent lowers adjusted EBITDA by $150,000, which at 8.6x cuts practice value by $1.29M. The same rent capitalized at 6.5% supports a building value of about $2.31M, so keeping the property and signing a market lease, or selling it to a net-lease buyer, can leave the owner ahead.
What moves a veterinary practice up or down its band?
Doctor depth, margin and reliance on the owner move a practice within its band. CLA Meridian Capital scores practices from fully owner-dependent to associate-driven production, and from EBITDA margins under 10% to over 20%. A practice that sits at the favorable end of each driver is priced toward the 13.0x to 15.0x top-tier range.
| Driver | Lower in the band | Higher in the band | Source |
|---|---|---|---|
| Doctor depth | Solo DVM: 3.5x to 5.0x under $250K EBITDA | 3+ DVMs: 8.0x to 12.0x at $500K to $1M | Ad Astra Equity, June 2026 |
| Key-person risk | Fully owner-dependent | Associate-driven production | CLA Meridian Q2 2026 |
| EBITDA margin | Under 10% | Over 20% | CLA Meridian Q2 2026 |
| Specialty mix | General practice: 8.6x at $1M to $5M | Specialists: 11x at $1M to $5M | First Page Sage, Q1 2025 |
| Add-back quality | Aggressive or unsupported adjustments | Clean, documented adjustments | CLA Meridian Q2 2026 |
| Rollover flexibility | Cash-only demand | Open to rollover or partnership | CLA Meridian Q2 2026 |
Owner dependence is the driver most owners can change before a sale. Moving production to associates over 12 to 24 months before going to market is covered in our owner dependency explainer and our veterinary practice exit plan.
Which buyers and multiples fit your practice?
Match the buyer route to your EBITDA and doctor count first, then negotiate structure. The decision table uses the size bands from First Page Sage, Ad Astra Equity and CLA Meridian Capital. Where a row gives a range, expect the low end if the owner produces most of the revenue and the high end with an associate bench.
| If your practice is | Expected range (source) | Then do this |
|---|---|---|
| Solo DVM, under $250K adjusted EBITDA | 3.5x to 5.0x (Ad Astra) | Compare an individual DVM buyer with regional groups; ask whether the offer is on SDE or EBITDA |
| Sole provider, $250K to $1M EBITDA | 5.0x to 8.0x (CLA Meridian) | Add or retain an associate before marketing; document every add-back |
| General practice, $1M to $5M EBITDA, 3+ DVMs | 8.6x average (First Page Sage) | Run a process with several national and regional platforms; price rollover in each offer |
| Specialty or emergency, $1M+ EBITDA | 11x to 15x (First Page Sage, Red Bike) | Include specialty-focused groups; quantify referral revenue by source |
| You own the building | About 6.5% cap rate (FCPT, 2026) | Price the property separately from the practice; compare a market lease with a sale |
| Offer is mostly rollover in a stressed platform | Check the sponsor’s credit (e.g. Caa3 at Thrive) | Ask for more cash at close or a put right on the rolled equity |
CT Acquisitions helps owners of founder-owned practices run a confidential sale, recapitalization or exit plan with a network of 500+ buyers. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells. Book a confidential call to test your range.
How we compiled this
We compiled this page in November 2026 from 24 dated documents: the VCA merger proxy and a Chewy 10-Q on SEC EDGAR, four FTC documents, sponsor, lender and company releases (Ares, OTPP, Harvest Partners, Ropes & Gray, FCPT, Mission Pet Health), trade and database sources (Private Equity Wire, Octus, Private Equity Vet), CLA Meridian Capital’s Q2 2026 report, BLS and NAPHIA data, and six published multiple studies. Multiples are reported as each source states them; implied figures show their arithmetic. We excluded forum posts and any multiple without a named publisher.
Frequently asked questions
What multiples of EBITDA do vet practices sell for?
Vet practices sell for about 5.0x to 8.0x EBITDA when sub-scale or owner-dependent and 13.0x to 15.0x or more when top-tier, per CLA Meridian Capital’s Q2 2026 update. The average across reported deals was 12.3x in the first half of 2026. General practices at $1M to $5M EBITDA averaged 8.6x in First Page Sage’s Q1 2025 study.
How do you value a veterinary practice?
Value a veterinary practice by multiplying adjusted EBITDA by a market multiple. Reset the owner-veterinarian’s pay to a market wage (the BLS median was $130,100 in May 2025), remove one-time and personal costs, charge market rent, then apply the multiple for your size, doctor count and specialty mix. Price owned real estate separately.
How much are corporations paying for veterinary practices?
Corporate buyers paid 8x to 13x EBITDA in 2023 per Ackerman Group, and DVM Elite reports 6x to 8x for corporate buyers in 2026. Disclosed platform deals run higher: Mars paid more than 19x LTM adjusted EBITDA for VCA in 2017, and Partners Group paid a reported 15.0x for Blue River PetCare in 2024.
Are veterinary multiples lower than in 2021?
Yes. CLA Meridian’s average veterinary EBITDA multiple peaked at 14.9x in the second half of 2021 and stood at 12.3x in the first half of 2026, about 17% lower. Deal counts fell further, from 1,550 hospitals sold in 2021 to 357 in 2025, so fewer practices now compete for buyer attention.
Do specialty and emergency hospitals get higher multiples?
Specialists get the highest multiples in each size band in First Page Sage’s Q1 2025 data: 7.1x at $500K to $1M EBITDA, 11x at $1M to $5M and 13.2x at $5M to $10M. Emergency clinics tracked general practice closely, at 5.4x, 8.1x and 10.4x in the same bands.
How much of a consolidator offer is paid in cash at closing?
Transitions Elite, a veterinary practice broker, reports 60% to 80% of deal value paid in cash at closing, with earnouts of 10% to 25% and rollover equity of 10% to 30%. Compare offers on cash at close and on the credit of the platform issuing the rolled equity, not only on the headline multiple.
Sources
- CLA Meridian Capital, Veterinary Services Market Update Q2 2026, accessed Nov 2026.
- VCA Inc., definitive merger proxy DEFM14A (Feb 15, 2017), accessed Nov 2026.
- Chewy Form 10-Q, quarter ended Aug 2, 2026, accessed Nov 2026.
- FTC, Mars/VCA analysis (2017); FTC, JAB/SAGE (Jun 13, 2022); FTC, JAB/Ethos (Jun 29, 2022); Statement of Chair Khan (Jun 13, 2022), accessed Nov 2026.
- First Page Sage, Veterinary Practice EBITDA and Valuation Multiples (Jan 7, 2025), accessed Nov 2026.
- Ad Astra Equity (Jun 5, 2026); Ackerman Group (Jun 25, 2025); DVM Elite (Jun 17, 2026); Red Bike Advisors; Transitions Elite, accessed Nov 2026.
- OTPP, KKR to acquire PetVet (Dec 27, 2017); Harvest Partners, VetCor recap (Jul 2, 2018); Ares, NVA to JAB (Jun 17, 2019); Ropes & Gray, TSG/Pathway (Apr 3, 2020), accessed Nov 2026.
- Private Equity Wire, Shore and Silver Lake (Nov 2024); Mission Pet Health (Jul 21, 2025); FCPT (Jul 2026); Octus, Thrive (Sep 22, 2026); Private Equity Vet database (Oct 24, 2026), accessed Nov 2026.
- BLS Occupational Outlook Handbook, Veterinarians; NAPHIA industry data (2026 report), accessed Nov 2026.
Related research: sector-wide figures are in the Healthcare Services M&A Multiples Report 2026 and the sibling Dental and DSO M&A Multiples Report 2026.
