
F Reorganization Steps: The 7-Step Process to Convert and Sell an S-Corp Without Tax Drag
An F reorganization is a tax-free change in form of one corporation under IRC Section 368(a)(1)(F): owners form NewCo, swap their S-corp stock for NewCo stock, file Form 8869, convert the old company to an LLC, then sell it.
By Christoph Totter, Founder of CT Acquisitions · Last reviewed: October 2026
Key takeaways
- A valid F reorganization must meet all six requirements of Treas. Reg. 1.368-2(m)(1), which applies to transactions on or after September 21, 2015.
- NewCo files Form 8869 with line 14 checked “Yes”, and no Form 2553 is required from the parent.
- Under Rev. Rul. 2008-18, NewCo must obtain a new EIN and the old S corporation keeps its EIN.
- A missed Form 8869 can be cured within 3 years and 75 days of the intended effective date under Rev. Proc. 2013-30, with no IRS user fee.
- The buyer’s basis step-up covers only the purchased portion; rolled equity keeps the seller’s basis, per Mintz (October 2024) and IRC Section 723.
What is an F reorganization, and why do S-corp sellers use one?
An F reorganization lets an S corporation sale give the buyer asset-purchase tax treatment while the seller keeps a single legal transaction. The old company becomes a disregarded LLC under a new parent, so a sale of the LLC interests is taxed as an asset sale under IRC Section 1060 and Form 8594, and the buyer amortizes goodwill over 15 years under IRC Section 197.
Private equity buyers favor it for three reasons. The operating company keeps its EIN, contracts and permits; the seller can roll equity into the buyer’s partnership tax-deferred under IRC Section 721; and the step-up no longer hinges on a valid original S election, a risk Mintz flags for a Section 338(h)(10) election.
What are the F reorganization steps?
The F reorganization steps are: form NewCo with identical owners, contribute 100 percent of the S-corp stock to NewCo, file Form 8869, make any state parent-level elections, convert the old company to an LLC at least one day later, close the sale, then file post-closing forms.
- Form NewCo. Incorporate NewCo with the same owners as OldCo and get its EIN on Form SS-4. NewCo must hold no property or tax attributes beforehand, apart from de minimis assets (Treas. Reg. 1.368-2(m)(1)(iii)).
- Contribute the stock. Every shareholder transfers 100 percent of OldCo stock for NewCo stock in identical proportions (1.368-2(m)(1)(i) and (ii)). Freeze the cap table first.
- File Form 8869. NewCo elects to treat OldCo as a qualified subchapter S subsidiary (QSub) under IRC Section 1361(b)(3), effective on the contribution date, with line 14 checked “Yes” and OldCo’s existing EIN on line 8. The election triggers a deemed liquidation of OldCo into NewCo; do not file Form 966.
- Make state elections at NewCo. New York’s Form CT-6 instructions say only the parent can make the New York S election, and a QSub whose parent does not elect is taxed as a New York C corporation.
- Convert OldCo to an LLC. Use a state statutory conversion or a merger into a new LLC, at least one day after the QSub election’s filing and effective dates (Plante Moran, November 2025). The single-owner LLC is disregarded by default, so no Form 8832 is filed.
- Close the sale. NewCo sells the LLC interests under a membership interest purchase agreement and, if rolling equity, contributes the rollover slice to the buyer’s partnership. Buyer and NewCo each attach Form 8594 to the return for the year of sale.
- File post-closing forms. The LLC reports its new responsible party on Form 8822-B within 60 days. NewCo keeps its S status only while it has no more than 100 eligible shareholders and one class of stock (IRC Section 1361(b)(1)).
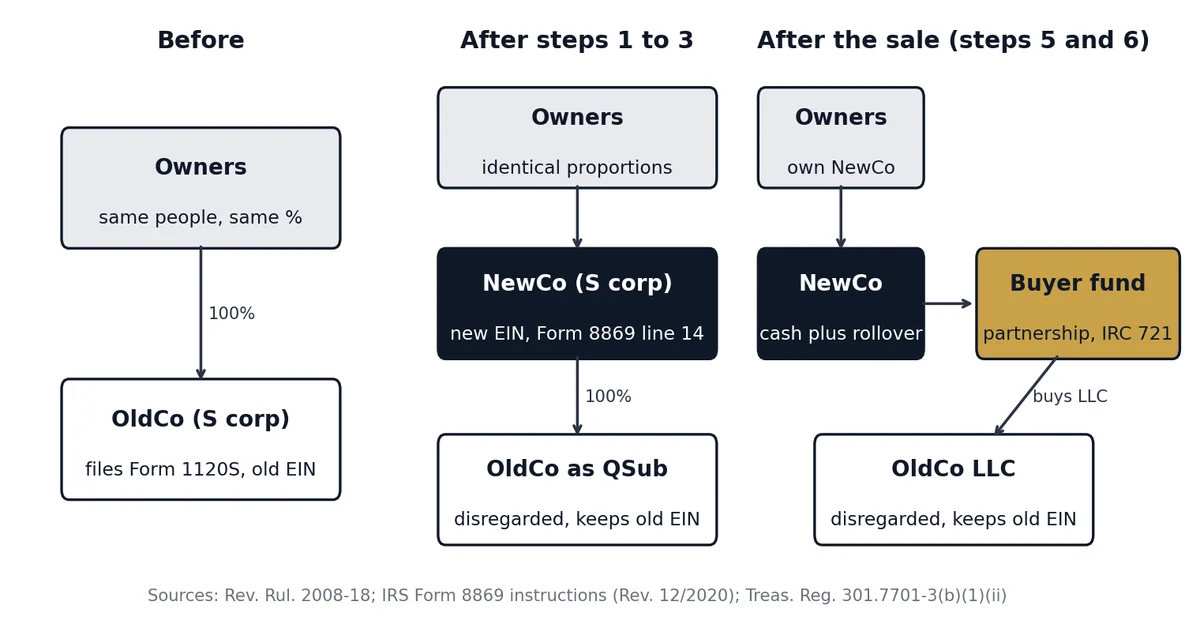
The F reorganization checklist below maps each step to its rule, filer, timing and EIN.
| Step | Governing rule | Form and filer | Timing | EIN |
|---|---|---|---|---|
| 1. Form NewCo | Treas. Reg. 1.368-2(m)(1)(iii) | State articles; Form SS-4 (NewCo) | Before the contribution | NewCo gets a new EIN |
| 2. Contribute stock | Treas. Reg. 1.368-2(m)(1)(i), (ii) | Contribution agreement (owners) | Same date as the Form 8869 effective date | OldCo keeps its EIN |
| 3. QSub election | IRC 1361(b)(3); Rev. Rul. 2008-18 | Form 8869, line 14 “Yes” (NewCo) | Effective no more than 2 months and 15 days before filing | OldCo EIN on line 8 |
| 4. State elections | State law (NY Tax Law section 660) | NY Form CT-6 (NewCo) | Preceding tax year or by the 15th day of the third month | NewCo EIN |
| 5. LLC conversion | Treas. Reg. 301.7701-3(b)(1)(ii) | State conversion or merger filing | At least one day after step 3 | LLC keeps OldCo EIN |
| 6. Sale | IRC 1060; IRC 721 for rollover | Form 8594 (buyer and NewCo) | With the return for the year of sale | LLC EIN moves with the business |
| 7. Post-closing | IRC 1361(b)(1) | Form 8822-B (LLC) | Within 60 days of the change | Unchanged |
The parent and subsidiary layout is explained further in our guide to a holding company structure.
Which six requirements make an F reorganization valid?
Treas. Reg. 1.368-2(m)(1) sets six tests, and failing any one removes F reorganization treatment. Continuity of interest and continuity of business enterprise are not required for an F reorganization under 1.368-2(m)(2), and related events before or after the reorganization, such as the sale, generally do not disqualify it under 1.368-2(m)(3).
| Requirement (1.368-2(m)(1)) | What it means in a sale | Where deals break it |
|---|---|---|
| (i) Stock for stock | All NewCo stock goes out in exchange for OldCo stock | NewCo issues shares to an investor or key employee during the steps |
| (ii) Identical owners | Same persons, same proportions before and after | A shareholder buyout or gift lands between steps 1 and 3 |
| (iii) Clean NewCo | No prior assets or tax attributes, beyond de minimis | NewCo is an existing company the owners already use |
| (iv) OldCo liquidates | For tax only; OldCo need not dissolve under state law | No QSub election, so no deemed liquidation occurs |
| (v) One acquirer | Only NewCo takes OldCo’s assets and tax attributes | Assets are split to a second entity in the same plan |
| (vi) One target | NewCo takes no property from any other corporation | A sister company is merged in during the steps |
How long does an F reorg take, and which deadlines apply?
No statute sets a minimum duration: steps 1 to 5 can be finished in days, because the LLC conversion only has to follow the QSub election by one day (Mintz; Plante Moran). The binding clocks are the Form 8869 effective-date window, the New York CT-6 deadline and the 60-day Form 8822-B rule. McDonald Hopkins (August 2026) notes that cleanup filings for a defective S election can extend the timeline.
| Clock | Rule | Source |
|---|---|---|
| Form 8869 effective date | No more than 2 months and 15 days before filing, and no more than 12 months after | Form 8869 instructions (Rev. 12/2020) |
| LLC conversion | At least one day after the QSub election is filed and effective | Plante Moran; Mintz |
| Late Form 8869 relief | Within 3 years and 75 days of the intended effective date, with reasonable cause | Rev. Proc. 2013-30, section 4.02 |
| NY S election | During the preceding tax year or by the 15th day of the third month | NY Form CT-6 instructions |
| Form 8822-B | Within 60 days of a responsible party change | IRS Form 8822-B |
| QSub re-election bar | No new election until the fifth taxable year after a termination | IRC 1361(b)(3)(D) |
| Built-in gains period | 5 years from the first S corporation year | IRC 1374(d)(7) |
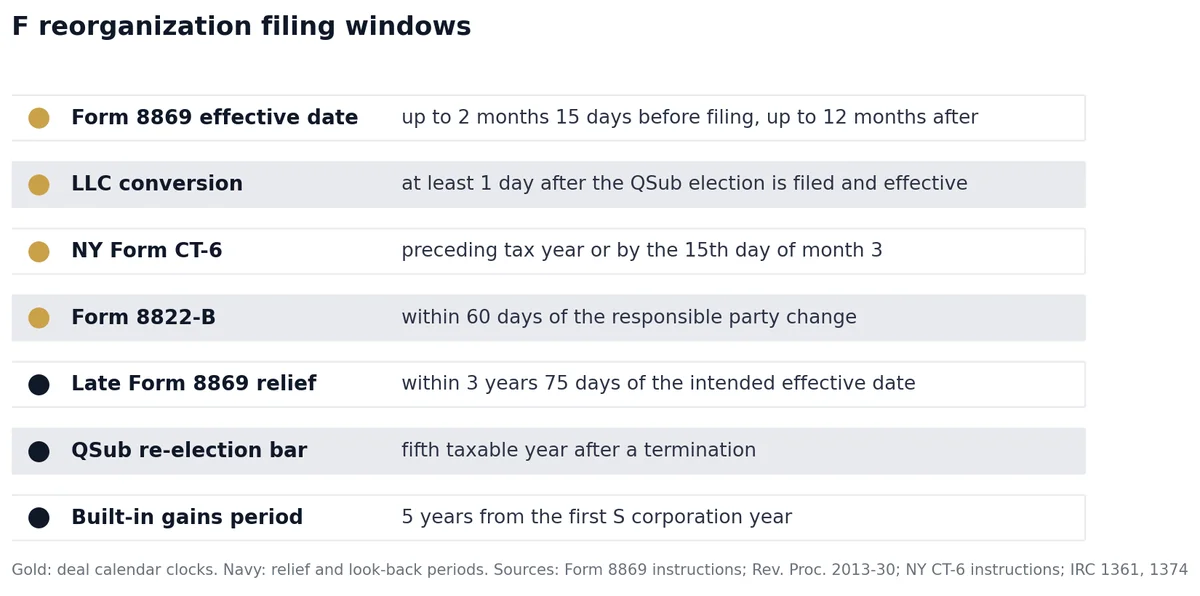
The Tax Adviser (February 2026) recommends sending Form 8869 by certified mail so the IRC Section 7502 timely-mailing rule applies, and filing it after the contribution but before the conversion takes effect.
What do other F reorganization guides get wrong?
Most errors in published F reorg guides involve Form 2553, the EIN and the LLC election. The table checks six common statements, two of them from earlier versions of this page, against the primary source so you can test your adviser’s checklist before filing.
| What some guides say | What the primary source says | Source |
|---|---|---|
| NewCo must file a new Form 2553 | No Form 2553 is required from the parent; the S election continues for NewCo. Plante Moran still recommends a protective election. | Form 8869 instructions, line 14; Rev. Rul. 2008-18 |
| No new EIN is needed | NewCo must obtain a new EIN; OldCo keeps its EIN | Rev. Rul. 2008-18 |
| File an election to make the LLC disregarded (Vela Wood, step 5) | A single-owner domestic LLC is disregarded by default | Treas. Reg. 301.7701-3(b)(1)(ii) |
| Continuity of business enterprise must be met | Not required for an F reorganization | Treas. Reg. 1.368-2(m)(2) |
| The buyer steps up the full price, rollover included | Step-up covers the purchased portion; contributed property keeps the contributor’s basis | Mintz; IRC 723 |
| Step order does not matter | The QSub election comes before the conversion; flipping them invalidated the election in PLR 201724013 | McDonald Hopkins |
F reorganization or another structure: which fits your deal?
Buyer type and rollover decide the structure. A Section 338(h)(10) election needs a corporate buyer acquiring at least 80 percent of the stock within 12 months; a Section 336(e) election allows non-corporate buyers; an F reorganization works with any buyer and supports a rollover. Our asset sale vs stock sale guide covers the wider trade-off.
| If your situation is | Then consider | Threshold or rule |
|---|---|---|
| PE fund or other partnership buyer, seller rolls equity | F reorganization | Rollover deferred under IRC 721 when the buyer vehicle is a partnership (Mintz) |
| Corporate buyer, 80 percent or more of stock, no rollover, clean S history | Section 338(h)(10) | IRC 338(d)(3) and 1504(a)(2) |
| Non-corporate buyer, 80 percent or more of stock, no rollover | Section 336(e) | Treas. Reg. 1.336-1(b)(6); no sale to a related person |
| Gaps in the S election history (missing consents, second class of stock) | F reorganization plus relief filings | Rev. Proc. 2013-30 or 2022-19 (McDonald Hopkins) |
| C corporation converted to S within the last 5 years | Any asset-treatment structure triggers built-in gains tax | 21 percent on recognized built-in gain, IRC 1374 |
| Business existed before August 10, 1993 and seller will own more than 20 percent of buyer | Test anti-churning before pricing the step-up | IRC 197(f)(9) (Plante Moran) |
| Target is an LLC that elected S status | Convert it to a corporation before step 1 | 60-month rule on Form 8832 (McDonald Hopkins) |
Worked example: how a rollover splits the step-up
This illustrative example uses round numbers, not a real deal. A buyer agrees to $20,000,000 for 100 percent of the LLC, and NewCo rolls 20 percent into the buyer’s partnership.
| Line | Amount | Rule |
|---|---|---|
| Headline value of the LLC | $20,000,000 | Illustrative |
| Rollover slice (20 percent) | $4,000,000 | IRC 721 deferral; IRC 723 carryover basis |
| Cash purchase (80 percent), stepped up | $16,000,000 | IRC 1060, Form 8594 |
| Goodwill share of the purchase (assumed 60 percent) | $9,600,000 | Class VII |
| Annual Section 197 amortization (divided by 15) | $640,000 | IRC 197 |
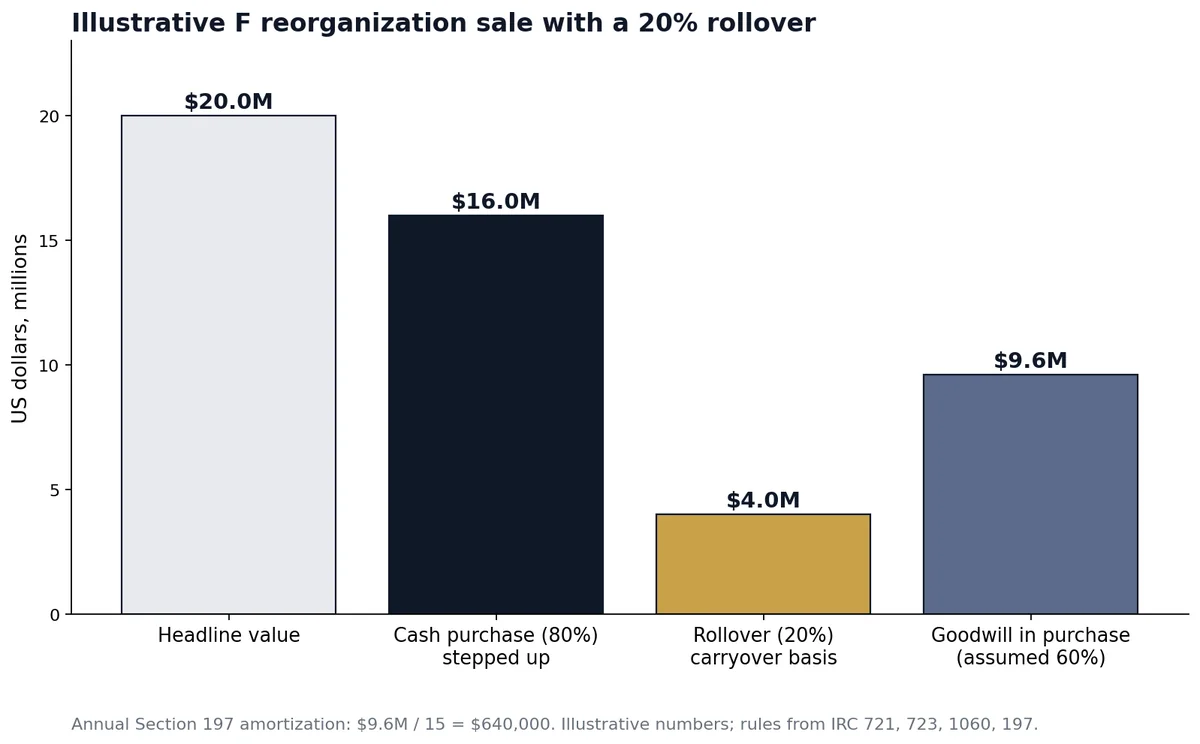
The seller is taxed now on the $16,000,000 slice and defers the $4,000,000 slice until the buyer’s exit. The split between ordinary recapture and capital gain follows the purchase price allocation; rollover mechanics are in our rollover equity tax guide.
What should you ask your CPA or tax attorney before step 1?
This page summarizes published IRS, Treasury and law-firm guidance; it is not tax advice. A tax attorney drafts the plan, contribution and conversion documents, and a CPA files Forms 8869 and 8594. Ask them:
- Has every Form 2553 consent and the S election history been verified, and do we need Rev. Proc. 2013-30 relief first?
- Will Form 8869 be effective on the contribution date, sent by certified mail, with line 14 checked?
- Which states need a parent-level S election, and what is each deadline?
- Does IRC 1374 or IRC 197(f)(9) reduce the value of the step-up in our deal?
For what the seller owes after closing, read our companion guide on F reorganization sale tax outcomes. CT Acquisitions is an M&A advisory firm for founder-owned businesses on the sell side, buy side and exit planning, with a network of 500+ buyers and capital partners. No fee to you on buy-side introductions; sell-side mandates are paid on success at closing.
How we compiled this
We compiled this from 20 primary and practitioner documents read in October 2026: Code and Treasury Regulation text on Cornell LII, Rev. Rul. 2008-18, Rev. Proc. 2013-30, the Form 8869 instructions, New York’s CT-6 instructions and five law-firm or journal articles. We excluded forum posts and unsourced deal-frequency statistics.
Frequently asked questions
What is the purpose of an F reorganization?
The purpose of an F reorganization in a sale is to give the buyer an asset-level basis step-up under IRC Section 1060 while the seller signs one equity purchase agreement. The old S corporation becomes a disregarded LLC under NewCo, keeps its EIN under Rev. Rul. 2008-18, and the seller can roll equity into a buyer partnership tax-deferred under IRC Section 721.
How long does it take to do an F-reorg?
The legal steps can be completed in days. The LLC conversion only needs to follow the Form 8869 QSub election by one day, according to Mintz and Plante Moran. Most of the calendar goes to verifying the S election history, state parent-level elections such as New York Form CT-6, and drafting documents, so start right after the letter of intent.
Does an F-reorg require a new EIN?
Yes for NewCo, no for the operating company. Rev. Rul. 2008-18 states that NewCo must obtain a new EIN, while the old S corporation, now a QSub and later an LLC, retains its EIN. NewCo applies on Form SS-4, and the old EIN goes on line 8 of Form 8869, so payroll accounts, contracts and permits stay unchanged.
Can you do an F-reorg with an LLC?
Yes, if the LLC is taxed as an S corporation, but the order changes. McDonald Hopkins notes that an LLC that filed Form 2553 generally cannot file Form 8832 to become disregarded within the 60-month window, so the LLC is usually converted to a state-law corporation before step 1. NewCo itself can be a corporation or an LLC taxed as an S corporation.
How much does an F-reorg cost?
The IRS charges no filing fee for Form 8869, Form SS-4 or Form 8594, and Rev. Proc. 2013-30 says user fees do not apply to its late-election relief. The cost is professional time plus state conversion fees. Ask your tax attorney and CPA for a fixed quote that names each step, each state filing and any relief filing.
Can you do an F reorg during the built-in gains period?
Yes. The reorganization itself is tax-free, but the asset-treatment sale that follows can trigger built-in gains tax if the company converted from a C corporation within the 5-year recognition period of IRC Section 1374(d)(7). The tax applies at the 21 percent corporate rate to recognized built-in gain, so model it before agreeing on price.
Sources
- 26 U.S.C. 368, 1361, 1374, 338, 197, 723 (Cornell LII)
- 26 CFR 1.368-2(m), 301.7701-3, 1.336-1 (Cornell LII)
- IRS, Rev. Rul. 2008-18, IRB 2008-13
- IRS, Rev. Proc. 2013-30
- IRS, Instructions for Form 8869 (Rev. December 2020)
- IRS, About Form 8594, Form 8822-B and Form SS-4
- New York State Department of Taxation and Finance, Form CT-6 instructions (12/20)
- Mintz, October 10, 2024; Plante Moran, November 2025; McDonald Hopkins, August 6, 2026; Vela Wood; The Tax Adviser, February 2026
- All sources accessed October 2026.
2 Responses