
What Is a Management Incentive Plan (MIP) in Private Equity? How MIPs Vest, Convert, and Pay Out
A management incentive plan (MIP) is a pool of equity, a median 10% of shares in WTW’s 2023 survey, that a private equity owner sets aside for managers: it pays only if the company sells above the value at grant.
By Christoph Totter, Founder of CT Acquisitions · Last reviewed: October 2026
Key takeaways
- MIP stands for management incentive plan. In WTW’s survey of 18 private equity investments, the median pool was 10% of undiluted shares outstanding, and 63% of it was granted at or near the deal (WTW via WorldatWork, August 2023).
- Law firm surveys put the average pool at 13% of fully diluted equity (Paul Hastings, 2013) and 9.51% (Goodwin, 2018), so check the denominator before you compare offers.
- Under IRS Rev. Proc. 93-27 and Rev. Proc. 2001-43, profits interests that meet the conditions are not taxed at grant or at vesting, and holders need not file a Section 83(b) election.
- Restricted stock is taxed at vesting unless you file a Section 83(b) election no later than 30 days after the transfer (26 U.S.C. 83(b)(2)); the IRS standard form is Form 15620 (Rev. 4-2025).
- A hurdle moves the check more than the percentage: in the illustrative payout walk below, a 2.0x return hurdle cuts a $720,000 payout to $240,000 at the same sale price.
What does MIP mean in business and private equity?
MIP means management incentive plan in business and private equity: equity or equity-like units that an owner reserves for the managers who run a portfolio company, on top of salary and bonus. The units pay out when the company is sold, and only on value created after the grant date. At some public companies the same name labels an annual cash bonus plan instead.
Deal documents may call the units incentive units, profits interests, management shares or, in UK deals, sweet equity. Section 2.02 of IRS Rev. Proc. 93-27 defines a profits interest as any partnership interest other than a capital interest, so the units have value only above the grant value.
| Where you saw “MIP” | What it stands for | What it is | Source |
|---|---|---|---|
| Private equity deal documents | Management incentive plan | Equity pool for managers, paid at the sponsor’s exit | WTW, 2023 |
| Corporate pay letters (“MIP bonus”) | Management incentive plan or program | Annual bonus tied to company targets, sometimes partly in stock units | INC Research MIP, SEC Exhibit 10.8 |
| FHA home loans | Mortgage insurance premium | Premium that protects lenders against loss on foreclosure | HUD Handbook 4155.2, ch. 7 |
| Medical imaging | Maximum intensity projection | 3D technique that condenses many images into one view | Stanford 3DQ Lab |
What is a MIP bonus at a corporate employer?
A MIP bonus at a corporate employer is an annual incentive payment, not private equity equity. The INC Research MIP filed with the SEC paid senior managers one lump sum per one-year performance period, sized as a target percentage of base earnings at 100% of an EBITDA target, and paid no later than April 15 after the plan year.
Some corporate plans mix cash and stock: the UPS Management Incentive Program, effective January 1, 2011, paid an electable portion in cash or shares by March 15 and the rest as Restricted Performance Units that vest 20% per year over 5 years. If your MIP pays every year, the exit sections below do not apply.
How is a management incentive plan structured?
A management incentive plan has four dials: pool size, upfront allocation, vesting conditions and the form of the units. WTW’s 2023 survey found a median pool of 10% of undiluted shares, 63% of it granted at or near the deal, performance conditions on some or all awards at 78% of sponsors, and stock options (61%) used more often than profits interest units (44%).
| MIP term | Published figure | Source and date |
|---|---|---|
| Pool size, median | 10% of undiluted shares outstanding (10.9% in the 2022 analysis) | WTW, 18 PE investments, Aug 2023 |
| Pool size, average | 9.51% (2018), 11.3% (2015), 12.6% (2013) | Goodwin Rollover and Incentive Equity Survey, May 2018 |
| Pool size, average | 13% of fully diluted equity | Paul Hastings study, Apr 2013 |
| Share of pool granted up front | 63% (6.3% of shares); historically 70% to 80% | WTW, Aug 2023 |
| Performance conditions on some or all awards | 78% of respondents | WTW, Aug 2023 |
| Most common performance goal | MOIC or money-on-money, 57% | WTW, Aug 2023 |
| Unit form used | Options 61%, profits interest units 44%, full-value awards 11% | WTW, Aug 2023 |
| CEO rollover alongside the MIP | 25% of sale proceeds on average; direct reports 10% to 15% | WTW, Aug 2023 |
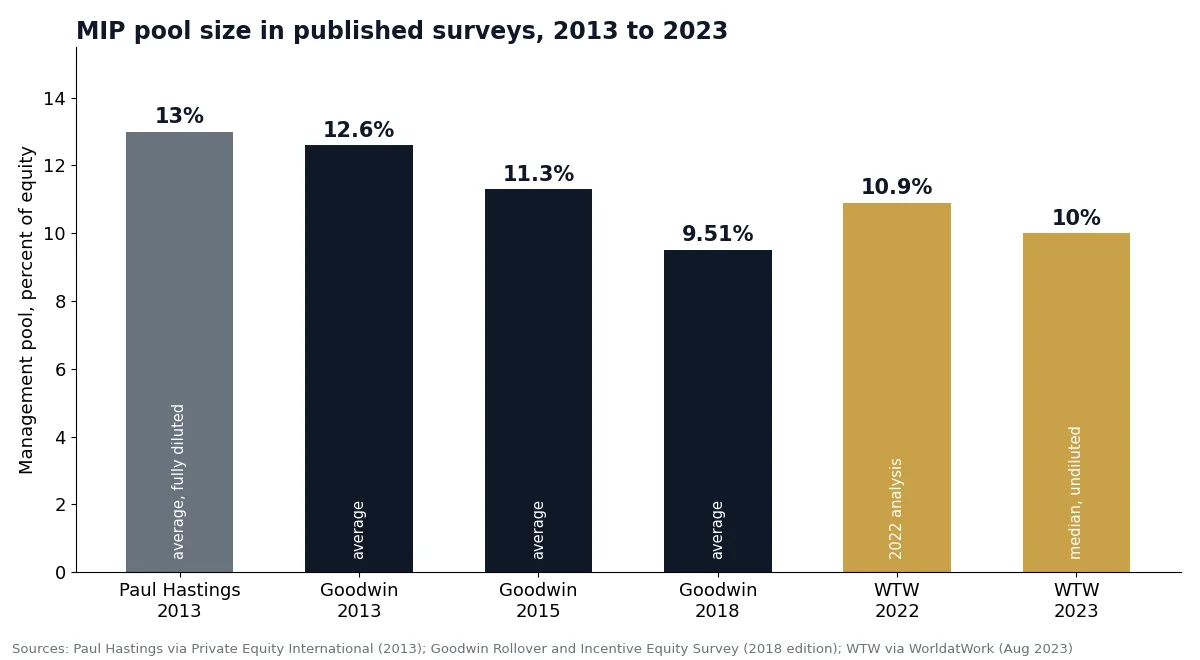
WTW measures against undiluted shares and Paul Hastings against fully diluted equity, so the same grant reads lower on the second basis. Ask for your grant as a percentage of both the pool and fully diluted equity: a 15% slice of a 10% pool is 1.5% of the company, tied to the sponsor’s private equity value creation plan.
Want a specific read of your business?
CT Acquisitions is an M&A advisory firm working both sides of the table, with 500+ active lower-middle-market buyer relationships. We help founders understand and negotiate the full deal, including the management incentive plan that shapes their future upside. Book a confidential call.
Book a 30-Min CallHow does MIP equity vest?
MIP equity vests in two ways: by time, while you stay employed, and by performance, usually when the sponsor’s multiple on invested capital (MOIC) clears a target at exit. WTW found that 78% of sponsors attach performance conditions to some or all awards, and 57% use MOIC or money-on-money as the goal. Unvested units are usually forfeited when a manager leaves.
- Time vesting. Units vest in steps over a stated number of years. Check what happens to the unvested part if the sale comes before the schedule ends.
- Performance vesting. Units vest only if the sponsor’s return reaches a multiple, for example 2.0x MOIC. Ask how the multiple is measured.
- Single trigger. Unvested units vest on the change of control alone.
- Double trigger. Units vest only on a change of control plus termination; read the definitions of termination without cause and good reason.
- Good leaver and bad leaver. These clauses set the buyback price for vested units when you leave: fair value, or a lower figure such as what you paid.
Which form will your MIP take, and how is each form taxed?
The tax result of a management incentive plan depends on the form of the units, not on the plan’s name. Profits interests in an LLC taxed as a partnership can be tax-free at grant under IRS Rev. Proc. 93-27; nonqualified options are taxed when exercised; restricted stock is taxed at vesting unless you file a Section 83(b) election within 30 days. Each row cites the rule.
| Unit form | At grant and vesting | At exercise or exit | Rule |
|---|---|---|---|
| Profits interest (LLC incentive units) | Not a taxable event if the safe harbor is met; no 83(b) needed if the company treats you as a partner from grant and nobody deducts the units’ value | Gain on sale; long-term capital gain if held more than 1 year | Rev. Proc. 2001-43, Rev. Proc. 93-27, 26 U.S.C. 1222(3) |
| Nonqualified stock option | No tax if the strike is at least fair market value at grant; a strike below it can make the option deferred compensation | Fair market value at exercise less the price paid is income; a 409A failure adds 20% tax plus interest | IRS Topic 427, 26 U.S.C. 409A |
| Incentive stock option (corporations only) | No regular tax; strike must be at least fair market value; over $100,000 first exercisable in a year becomes nonqualified | No regular tax at exercise (AMT may apply); capital gain if shares are held 2 years from grant and 1 year from exercise | 26 U.S.C. 422, IRS Topic 427 |
| Restricted stock | Value less price paid is income at vesting, or at grant if you file an 83(b) election within 30 days | Gain above the amount already taxed; long-term if held more than 1 year | 26 U.S.C. 83, Form 15620 |
| Phantom equity or cash MIP | No tax until paid | Paid as compensation: “the payment of a bonus is treated as employment income and taxed accordingly” | Latham & Watkins, Feb 2024, 26 U.S.C. 409A |
The profits interest safe harbor has three exceptions, summarized by Proskauer Rose (May 2023): the interest must not relate to a substantially certain and predictable stream of income, must be held at least two years before disposition, and must not come from a publicly traded partnership. In ES NPA Holding, LLC v. Commissioner (T.C. Memo 2023-55), the Tax Court read the safe harbor broadly.
One correction to common guides: Incentiv’s MIP guide says plans “structured adeptly” typically allow capital gains treatment, with no conditions given. The IRS sources above attach a condition to every capital gain route: the 93-27 two-year hold, the Section 422 holding periods, or a timely 83(b) election. This page summarizes public IRS rules and is not tax advice.
Which MIP tax deadlines run from the grant date?
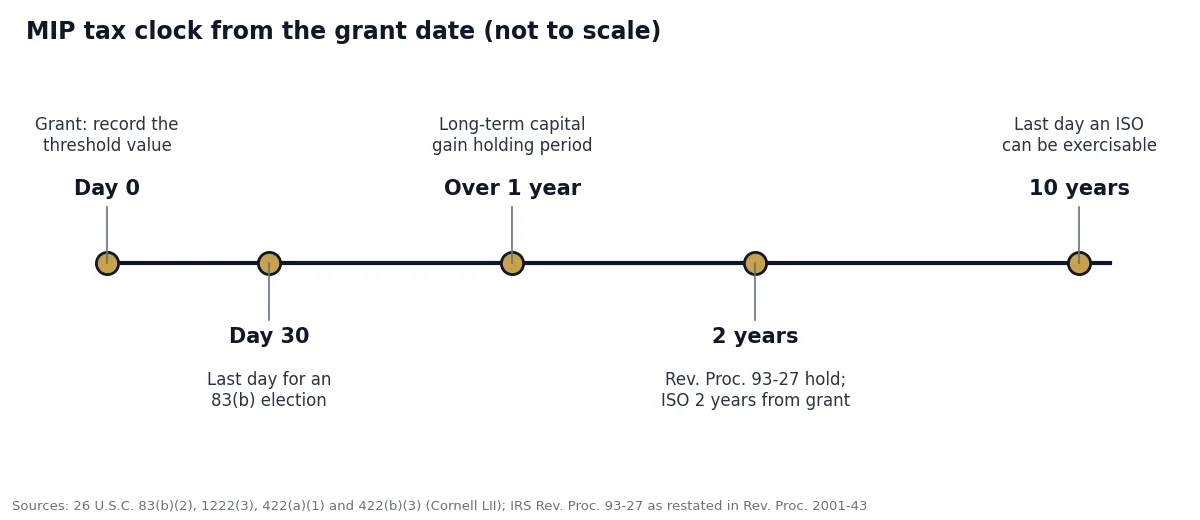
Five dates run from the day MIP units are granted or transferred. The shortest is 30 days, the last day to file a Section 83(b) election, and 26 U.S.C. 83(b)(2) allows no late filing. Capital gain needs a holding period of more than 1 year, incentive stock options need 2 years from grant, and an ISO cannot be exercisable after 10 years.
| Date from grant | What happens | Applies to | Rule |
|---|---|---|---|
| Day 0 | Grant or transfer; get the threshold value in writing | All unit forms | Plan document |
| Day 30 | Last day to file an 83(b) election | Restricted stock and other unvested property | 26 U.S.C. 83(b)(2), Form 15620 |
| More than 1 year | Gain can be long-term capital gain | Profits interests, stock | 26 U.S.C. 1222(3) |
| 2 years | Earliest sale that keeps the Rev. Proc. 93-27 safe harbor; ISO 2-year holding period (plus 1 year from exercise) | Profits interests, ISOs | Rev. Proc. 93-27, 26 U.S.C. 422(a)(1) |
| 10 years | Last day an ISO can be exercisable | ISOs | 26 U.S.C. 422(b)(3) |
How much is a management incentive plan worth at exit?
A management incentive plan is worth your share of the equity growth above the grant threshold, not a share of the sale price. Multiply that growth by the pool, your allocation and your vested fraction, then subtract escrow and rollover. In the illustrative case below, the same 15% slice of a 10% pool pays $720,000 without a hurdle and $240,000 with a 2.0x hurdle.
- Sale price (enterprise value). The headline number. Your MIP is never a share of this.
- Less debt and deal costs, giving equity value. Lenders and advisers are paid first; the order is set by the private equity capital stack.
- Less the threshold. Profits interests share only in value above the level set at grant. A sponsor return hurdle sits here too.
- Times the pool size. The share of that growth set aside for management.
- Times your allocation and your vested fraction. Cut to what has vested by the sale date unless the plan accelerates.
- Less what is not paid at closing. Escrows, holdbacks, earnouts, required rollover and tax.
The figures below are illustrative, not drawn from a real deal. A sponsor buys a company at an equity value of $40M and grants a 10% MIP pool with the threshold set at that $40M. Five years later the company sells for $150M. Debt and costs take $50M, leaving $100M of equity value.
| Line | No hurdle | Hurdle at 2.0x the sponsor’s money |
|---|---|---|
| Value the MIP shares in | $100M less $40M = $60M | $100M less $80M = $20M |
| 10% pool | $6M | $2M |
| Your 15% of the pool, 80% vested | $720,000 | $240,000 |
| After a 10% escrow holdback | $648,000 at closing | $216,000 at closing |
The same grant pays 1.2% of equity value above the line (15% of 10% of 80%). This simplified model ignores catch-up tranches.
| Equity value at exit | Your payout, no hurdle ($40M threshold) | Your payout, 2.0x hurdle ($80M) |
|---|---|---|
| $40M | Nothing | Nothing |
| $60M | $240,000 | Nothing |
| $80M | $480,000 | Nothing |
| $100M | $720,000 | $240,000 |
| $120M | $960,000 | $480,000 |
| $150M | $1,320,000 | $840,000 |
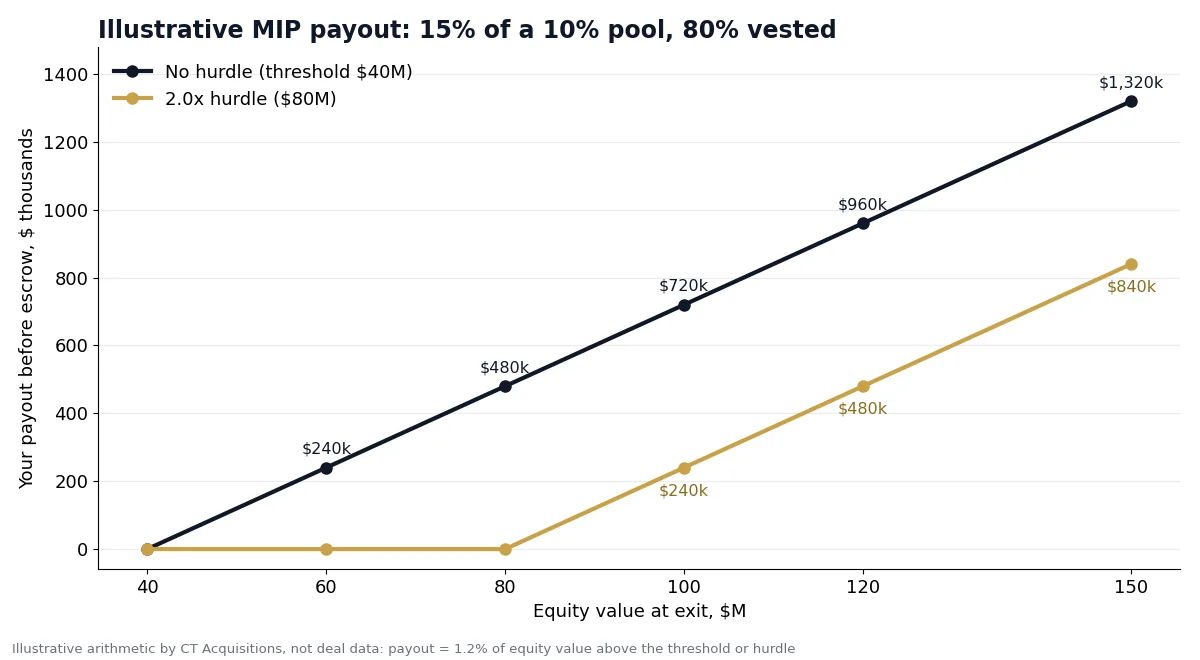
Below $80M of equity value the hurdle version pays nothing, and each $20M above the line adds $240,000 in both versions. Ask for three numbers in writing: the threshold value on your grant, the exact return target, and the sponsor’s base case for debt at exit.
What happens to a management incentive plan when the company is sold?
When a private equity owner sells, the management incentive plan pays out, rolls over, or both. Vested units share in proceeds above the grant threshold, unvested units accelerate only under single or double trigger terms, and the buyer often asks managers to reinvest part of the payout before granting a new MIP. In WTW’s 2023 survey, CEOs rolled 25% of sale proceeds on average.
| Issue | Common approaches | What to check |
|---|---|---|
| Vesting on a sale | Single trigger or double trigger; performance units often vest only if the sponsor hits a return target | Which trigger applies and how the return target is measured |
| Payout waterfall | Profits interests share only in value above the grant threshold, after debt and the sponsor’s preferred return | At what sale price the MIP starts to pay |
| Rollover | The buyer asks management to reinvest part of its proceeds | How much must roll, at what valuation and on what terms |
| New MIP | A new sponsor sets up a new pool for the next hold period | Pool size, your allocation and when vesting restarts |
| Escrow and earnouts | MIP holders usually bear their share of escrows, holdbacks and earnouts | When deferred amounts are paid and what can reduce them |
| Leavers | Good leaver and bad leaver terms price units of managers who left before the sale | Whether a past departure affects your payout |
In a corporation, change of control payments that equal or exceed 3 times an executive’s base amount are parachute payments under 26 U.S.C. 280G: the company loses the deduction on the excess and the executive owes a 20% excise tax under 26 U.S.C. 4999. A company with no readily tradeable stock can exempt them with approval by more than 75% of shareholder voting power after full disclosure (Section 280G(b)(5)(B)).
Reinvestment terms are covered in our guide to management rollover and whether to do one, and escrow protections in how to negotiate an earnout in a business sale.
How is a MIP different from equity rollover or a bonus?
A MIP is new equity the sponsor grants for future growth; equity rollover is sale proceeds the seller reinvests; an annual bonus pays cash from yearly results. Only the MIP and rollover ride on one exit price, and only rollover puts the seller’s own money at risk. WTW found that one third of sponsors required rollover and 39% offered a voluntary one.
| Instrument | What it is | Paid when | Usual tax character | Source |
|---|---|---|---|---|
| Management incentive plan (private equity) | New units granted to managers after the deal | At the exit | Depends on form; capital gain possible for profits interests, ISOs and stock with an 83(b) | Rev. Proc. 93-27; 26 U.S.C. 422 and 83 |
| Equity rollover | Seller reinvests part of the sale proceeds in the buyer’s company | At the next exit | Gain can be deferred in a contribution under IRC Section 351 or Section 721 | 26 U.S.C. 351(a), 721(a) |
| Corporate MIP or annual bonus | Cash, sometimes partly stock units, tied to yearly targets | Each year | Compensation income | INC Research and UPS plan filings; Latham & Watkins |
| Cash MIP or phantom equity | Bonus pool funded from exit proceeds | At the exit | Compensation income | Latham & Watkins, Feb 2024 |
For founders the two equity routes stack; see equity rollover for founders and rollover equity tax treatment under Section 351.
Should you sign the management incentive plan as offered?
Sign a management incentive plan only after you can run its payout yourself. That takes three numbers in writing (the grant threshold, the return hurdle and the sponsor’s base case exit debt) plus the form of the units, because the form decides whether a 30-day 83(b) deadline or a Section 409A problem applies. Match your situation to a row below.
| If your situation is | Do this | Rule behind it |
|---|---|---|
| Your grant is restricted stock you buy or receive unvested | Ask your tax adviser before day 30 whether to file an 83(b) election on Form 15620 | 26 U.S.C. 83(b)(2); no late elections |
| Your grant is profits interests in an LLC | Confirm in writing that the company treats you as a partner from grant and takes no deduction for the units’ value | Rev. Proc. 2001-43, sections 4.01 and 4.02 |
| Your grant is options with a strike below fair market value at grant | Ask how the plan complies with Section 409A before you sign | 26 U.S.C. 409A: income inclusion plus 20% additional tax |
| Your ISOs first exercisable in one year exceed $100,000 at grant value | Expect the excess to be taxed as nonqualified options | 26 U.S.C. 422(d) |
| Performance vesting needs 2.0x MOIC or more | Model the payout at the sponsor’s base case exit, not the best case | Illustrative walk above: the 2.0x hurdle cut the payout by two thirds |
| The company is a corporation and your change of control payments reach 3 times your base amount | Ask whether the sponsor will hold a 280G shareholder vote | 26 U.S.C. 280G(b)(5)(B): more than 75% approval; 20% excise tax under 4999 |
| You are the founder rolling equity and taking a MIP grant | Compare the required rollover with WTW’s 25% CEO average and ask whether rolled equity ranks ahead of MIP units | WTW, Aug 2023 |
| Acceleration is double trigger only | Read what counts as termination, including a pay cut or relocation | Plan document definitions |
For a founder, the MIP is one line in the wider deal covered in what happens when you sell your business to private equity. CT Acquisitions is an M&A advisory firm for founder-owned businesses (sell side, buy side and exit planning, 500+ buyer network); it reviews MIP terms in a sale process and does not give tax advice. No fee to you on buy-side introductions; sell-side mandates are paid on success at closing.
How we compiled this
We compiled this page in October 2026 from 21 documents: IRS Rev. Proc. 2001-43 (which restates Rev. Proc. 93-27), IRS Tax Topic 427, IRS Form 15620, eight Internal Revenue Code sections on Cornell LII (83, 409A, 422, 280G, 4999, 1222, 351, 721), WTW’s 2023 survey, coverage of the Goodwin 2018 and Paul Hastings 2013 surveys, two plan documents filed with the SEC (INC Research, UPS), notes from Proskauer Rose and Latham & Watkins, HUD Handbook 4155.2 and a Stanford lab page for the other meanings of MIP, and Incentiv’s guide, checked against the IRS sources. The payout figures are illustrative arithmetic, not client data. We excluded forum threads and software vendor pages as fact sources.
Frequently asked questions
What does MIP stand for in business?
MIP stands for management incentive plan. In private equity it is a pool of equity, a median 10% of undiluted shares in WTW’s 2023 survey, that the owner reserves for the managers who run the company. It pays out when the business is sold, and only on value created after the grant date.
What is a MIP payout?
A MIP payout is the cash a manager receives at the sale: the equity value above the grant threshold, times the pool, times the manager’s allocation and vested fraction, less escrow and any required rollover. In this page’s illustrative case, a 15% slice of a 10% pool, 80% vested, pays $648,000 at closing with no hurdle.
What are MIP shares?
MIP shares are the units issued to managers under a management incentive plan. They may be called incentive units, profits interests, management shares or, in UK deals, sweet equity. Under IRS Rev. Proc. 93-27 a profits interest is any partnership interest other than a capital interest, so it is worth something only if the company sells above the value set at grant.
Is a MIP the same as a bonus?
Not in private equity. An annual bonus is cash paid from yearly results, while a private equity MIP gives managers equity that pays mainly at the sale. Some sponsors run a cash MIP, a bonus pool funded from exit proceeds, and Latham and Watkins notes that such a payment is treated as employment income. At some public companies, such as UPS, MIP is the name of the annual bonus plan.
What happens to my MIP equity if I leave the company?
Unvested MIP units are usually forfeited when you leave. For vested units, the good leaver and bad leaver clauses set the buyback price, either fair value or a lower figure such as your cost. If you filed a Section 83(b) election on restricted stock that you later forfeit, 26 U.S.C. 83(b)(1) allows no deduction for the forfeiture.
How big is a typical MIP pool?
Published surveys put it near 10%. WTW’s 2023 survey found a median of 10% of undiluted shares outstanding, Goodwin’s 2018 survey an average of 9.51%, and a 2013 Paul Hastings study an average of 13% of fully diluted equity. Compare offers on the same denominator, because the same grant reads lower as a share of fully diluted equity.
Sources
- IRS, Rev. Proc. 2001-43, Internal Revenue Bulletin 2001-34 (restating Rev. Proc. 93-27), accessed October 26, 2026
- IRS, Topic no. 427, Stock options, accessed October 26, 2026
- IRS, Form 15620, Section 83(b) Election (Rev. 4-2025), accessed October 26, 2026
- Cornell LII, 26 U.S.C. 83, 409A, 422, 280G, 4999, 1222, 351, 721, accessed October 26, 2026
- WTW via WorldatWork, Examining plans for private equity portfolio companies (August 9, 2023), accessed October 26, 2026
- Private Equity Wire, Goodwin 2018 Rollover and Incentive Equity Survey (May 17, 2018), accessed October 26, 2026
- Private Equity International, Paul Hastings incentive equity study (April 23, 2013), accessed October 26, 2026
- Proskauer Rose, Tax Court decision interprets profits interest safe harbor (May 23, 2023), accessed October 26, 2026
- Latham & Watkins, Management Incentive Plan Resets: 4 Solutions for Sponsors (February 27, 2024), accessed October 26, 2026
- SEC EDGAR, INC Research Management Incentive Plan, Exhibit 10.8 and UPS Management Incentive Program, Exhibit 10.1.3, accessed October 26, 2026
- HUD Handbook 4155.2, chapter 7 and Stanford 3DQ Lab, What is a MIP?, accessed October 26, 2026
Related Guide: What Is Equity Rollover?
Related Guide: What Is a Management Rollover?
Related Guide: What Happens When You Sell to Private Equity
Related Guide: Selling a Manufacturing Company to Private Equity
Want a Specific Read of Your Business?
30 minutes, confidential, no contract, no cost. You leave with a read of your local buyer market and a likely valuation range.
For owners moving from concept to action, our sell-side prep sequence covers the practical prep work.
Buy-side readers can register through the proprietary buy-side network for direct-to-owner opportunities.
30 N Gould St, Ste N, Sheridan, WY 82801, USA · (307) 522-0262 · Contact