
Quality of Earnings Providers in 2026: 18 QoE Firms Compared by Type, Published Price and SBA Fit
Quality of earnings providers fall into four types: Big Four, national CPA firms, regional CPA firms and QoE boutiques. Only 3 of the 18 below publish prices, from $6,490 to $40,000, and SBA lenders cannot use a seller’s QoE.
Key takeaways
- For SBA loan numbers issued on or after October 1, 2026, the lender must obtain a QoE on Initial Acquisition and Business Expansion loans with a Business Purchase Price of $3 million or more, and the report “must not be prepared by or for the seller” (SBA SOP 50 10 8.1, Appendix 15, Para. C.1).
- Only 3 of the 18 quality of earnings providers below publish prices as of November 2026: WebAcquisition from $6,490, Guardian Due Diligence at $20K to $40K, and Midwest CPA, whose sell-side QoE starts at $25,000.
- The Big Four, RSM US, BDO USA, Baker Tilly and the other national firms quote QoE fees engagement by engagement; none of their QoE pages we read shows a price.
- The provider map moved in 2026: Grant Thornton agreed on July 29, 2026 to buy CBIZ for about $5 billion (INSIDE Public Accounting), and CBIZ already owned Marcum’s non-attest business.
- 52% of 185 U.S. respondents to Grant Thornton’s Q1 2026 International Business Report named the quality or completeness of target financials as a barrier to completing deals (Grant Thornton, May 2026).
Preparing to sell your business?
CT Acquisitions helps owners of founder-owned businesses run a confidential sale, recapitalization or exit plan, with a 500+ buyer network. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells.
Who are the main quality of earnings providers?
The main quality of earnings providers for a U.S. business sale are the Big Four (Deloitte, PwC, EY, KPMG), national CPA firms such as RSM US, Grant Thornton and BDO USA, regional CPA firms such as Weaver, BPM and Kreischer Miller, and QoE boutiques such as Midwest CPA. The table lists 18, each tied to the firm’s own service page, read in November 2026.
| Provider | Type (CT grouping) | What its own QoE page lists | Published price | Source |
|---|---|---|---|---|
| Deloitte | Big Four | Acquisition and vendor (sell-side) due diligence | None found | Deloitte |
| PwC | Big Four | Financial due diligence within PwC Deals | None found | PwC |
| EY (EY-Parthenon) | Big Four | Sell-side: a “credible and defensible financial narrative”; normalized earnings, working capital, debt-like items | None found | EY |
| KPMG | Big Four | Divestiture and sell-side diligence, including working capital and net debt | None found | KPMG |
| RSM US | National CPA firm | Quality of earnings analysis under financial due diligence; deal work on more than 1,100 transactions a year | None found | RSM US |
| Grant Thornton (now with CBIZ and Marcum) | National CPA firm | Buy-side and sell-side financial diligence; agreed on July 29, 2026 to buy CBIZ, which bought Marcum’s non-attest business on November 1, 2024 | None found | IPA, CBIZ 8-K |
| BDO USA | National CPA firm | Due diligence “beyond the scope of a traditional Quality of Earnings analysis”; sell-side financial due diligence | None found | BDO |
| Baker Tilly (with Moss Adams) | National CPA firm | Quality of earnings plus vendor due diligence; Moss Adams merged in effective June 3, 2025 | None found | Baker Tilly, SEC 8-K |
| Forvis Mazars | National CPA firm | Earnings and cash flow quality, net working capital; formed June 1, 2024 from FORVIS and Mazars USA | None found | Forvis Mazars |
| Plante Moran | National CPA firm | Sell-side due diligence that “includes a quality of earnings analysis, working capital assessment” | None found | Plante Moran |
| Eide Bailly | National CPA firm | Buy-side due diligence and sell-side quality of earnings; 50+ offices | None found | Eide Bailly |
| Withum | National CPA firm | Sell-side quality of earnings report for “a smooth and speedy sale process” | None found | Withum |
| Weaver | Regional CPA firm | Sell-side QofE to find what the buy-side QofE team may uncover | None found | Weaver |
| BPM | Regional CPA firm (No. 32, IPA 2026) | Preliminary QoE analysis for sell-side preparation; working capital analysis | None found | BPM |
| Kreischer Miller | Regional CPA firm (Horsham, PA) | Publishes Full Scope QoE vs QoE Lite scope side by side | Scope only, no price | Kreischer Miller |
| Midwest CPA | QoE boutique | Proof of cash and working capital peg in every QoE; 350+ QoE reviews completed | Yes: sell-side from $25,000 | Midwest CPA |
| Guardian Due Diligence | QoE boutique (buyer focus) | Adjusted EBITDA and SDE, working capital peg, 65-item red flag checklist | Yes: $20K, $25K, $40K | Guardian |
| WebAcquisition | QoE boutique (buyer focus) | Full QoE and QoE Lite for acquisitions up to $5 million | Yes: from $6,490 | WebAcquisition |
Cherry Bekaert, EisnerAmper and Frazier & Deeter also list QoE work. If a proposal arrives on CBIZ or Marcum letterhead, note that CPA Practice Advisor reported on November 2, 2026 that the Grant Thornton and CBIZ deal had closed, with the firm going to market as Grant Thornton (CPA Practice Advisor). For what a QoE tests, see our quality of earnings guide.
Which quality of earnings providers publish their prices?
Three of the 18 providers publish QoE prices as of November 2026. WebAcquisition lists a QoE Lite from $6,490 and a full QoE from $8,900; Guardian Due Diligence lists $20K, $25K and $40K tiers for purchase prices under $2M; Midwest CPA lists about $15,000 under a $5MM price and a sell-side QoE from $25,000, with fixed fees quoted in writing.
| Provider | Product | Published price | Scope or condition | Published turnaround |
|---|---|---|---|---|
| WebAcquisition | QoE Lite | From $6,490 | Acquisitions up to $5 million | Not stated |
| WebAcquisition | Full QoE | From $8,900 | Acquisitions up to $5 million | 2 to 3 weeks |
| Midwest CPA | Buy-side QoE | About $15,000 | Purchase price under $5MM | 2 to 4 weeks |
| Midwest CPA | Buy-side or SBA Lender-Ready QoE | $18,000 to $25,000 | $5MM to $15MM, or any SBA Lender-Ready QoE | 2 to 4 weeks |
| Midwest CPA | QoE over $15MM | From $25,000 | Purchase price over $15MM | 2 to 4 weeks |
| Midwest CPA | Sell-side QoE | From $25,000 | Proof of cash and working capital included | 2 to 4 weeks |
| Guardian Due Diligence | Excel-only QoE | $20,000 | 2025 and 2026 TTM; price under $2M | Not stated |
| Guardian Due Diligence | QoE | $25,000 | 2024, 2025 and 2026 TTM; price under $2M | Not stated |
| Guardian Due Diligence | Advised QoE | $40,000 | Full QoE plus 10 advisory hours | Not stated |
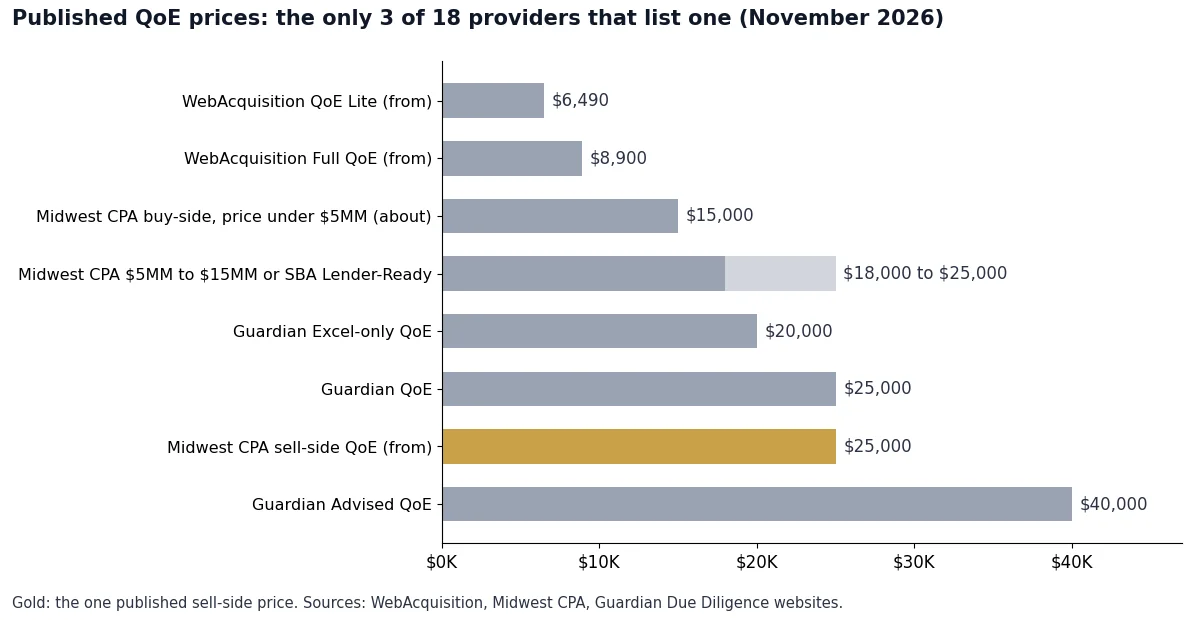
Two of the three publishers sell mainly to buyers: Guardian’s tiers are built for $1M to $10M purchase prices, and WebAcquisition targets acquisitions up to $5 million. For an owner preparing to sell, the one published sell-side price in this set is the Midwest CPA starting fee of $25,000. Kreischer Miller publishes scope instead of price: its QoE Lite may drop customer and supplier analysis and typically excludes debt-like items, which a buyer’s team will test anyway. Our seller guide to QoE report cost covers what drives a quote.
How do Big Four, national, regional and boutique QoE providers differ?
The four provider types differ first on price disclosure and then on who they are built for. None of the 15 Big Four, national or regional firms shows a QoE fee; all 3 boutiques do. National firms cite scale, such as more than 1,100 transactions a year at RSM US, while boutiques publish 2 to 4 week turnarounds and proof of cash in every report.
| Type | Firms in this table | Price disclosure | What their pages emphasize | Where sellers tend to use them (CT Acquisitions judgment) |
|---|---|---|---|---|
| Big Four | Deloitte, PwC, EY, KPMG | None found | Vendor due diligence, debt-like items, divestitures | Large sponsor auctions, public or cross-border buyers |
| National CPA firm | RSM US, Grant Thornton, BDO USA, Baker Tilly, Forvis Mazars, Plante Moran, Eide Bailly, Withum | None found | RSM US cites more than 1,100 transactions a year; Eide Bailly 50+ offices | Sales to PE platforms and strategic acquirers in a run process |
| Regional CPA firm | Weaver, BPM, Kreischer Miller | Kreischer Miller publishes scope tiers, no price | Sell-side preparation, working capital, QoE Lite option | Owner-run companies selling to regional or PE buyers |
| QoE boutique | Midwest CPA, Guardian Due Diligence, WebAcquisition | Published, $6,490 to $40K | Proof of cash, working capital peg, 2 to 4 week turnaround | SBA-financed and smaller deals; buyer-side QoE Lite |
Can an SBA lender use your sell-side quality of earnings?
No, not as the required report. Under SBA SOP 50 10 8.1, Appendix 15, Para. C.1, in force for SBA loan numbers issued on or after October 1, 2026 (SBA Information Notice 5000-880695), the lender must obtain its own QoE when the Business Purchase Price is $3 million or more, and that report “must not be prepared by or for the seller.”
| Rule | What SOP 50 10 8.1 says | What it means for the seller |
|---|---|---|
| Trigger | Initial Acquisition or Business Expansion, Business Purchase Price of $3 million or more, set before buyer equity or seller debt | A seller note does not get you under it. |
| Exemptions | Owner Buyout, ESOP & Cooperative, owner-occupied Special Purpose Property | Partner buyouts and ESOP sales skip it. |
| Who orders it | An independent professional, for the benefit of the Lender; “must not be prepared by or for the seller” | Your sell-side QoE cannot stand in for it. |
| Buyer’s own QoE | Usable after review by a Lender-approved vendor | A buyer report can be reused; yours cannot. |
| Cash Proof | Bank data reconciled to income statement and tax return, trailing 12 months and last two fiscal years | Have three periods of bank statements ready. |
| Reconciliation | Financial statements, tax returns and IRS transcript data tied to normalized earnings | Books that miss the returns become the finding. |
| Add-backs | Non-recurring items, owner pay, related-party deals, deferred maintenance, cash vs accrual | Test the same list first. |
| Debt service | DSC sized on QoE earnings; short coverage shrinks the loan, equity fills the gap | A rejected add-back cuts the buyer’s loan. |
| Timing | Under PLP, engaged when the SBA Loan Number is issued | The lender’s firm arrives right after LOI. |
| Cost | May be passed to the borrower; counts toward equity injection | The borrower carries it, not you. |
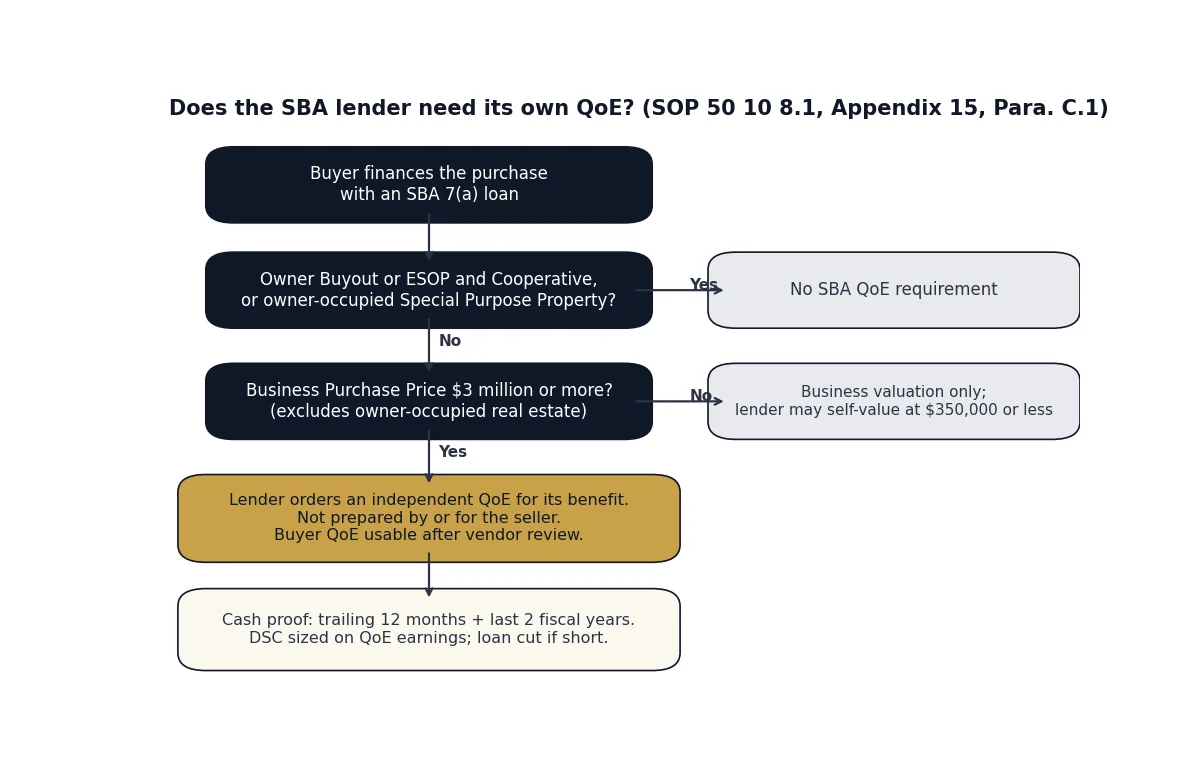
If your likely buyers use SBA financing above $3 million, build the sell-side QoE to the lender’s scope: a cash proof for the trailing 12 months and two fiscal years, tied to filed returns. The lender’s firm then retests work that already reconciles. The rest of the buyer’s loan rules are in our SBA 7(a) acquisition loan guide.
When should a seller order a quality of earnings?
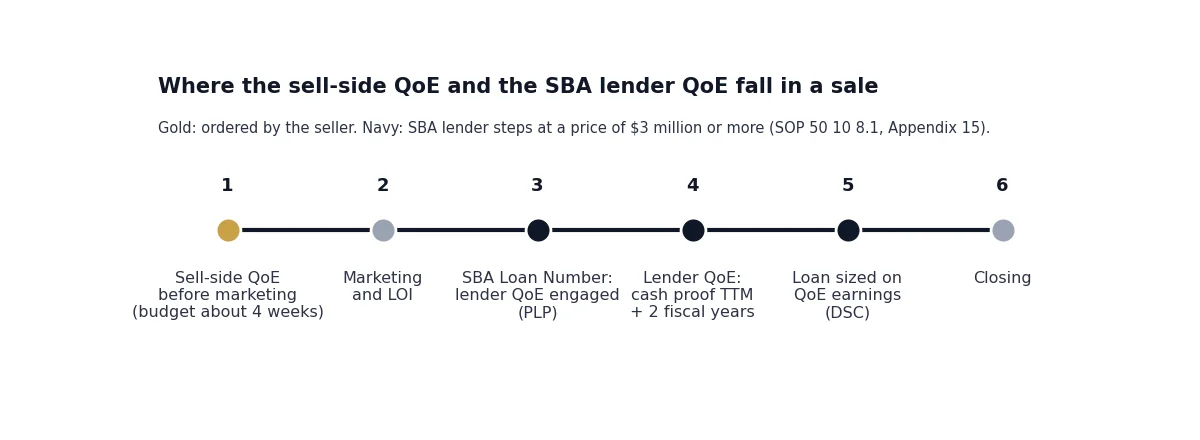
Order a sell-side quality of earnings before the business goes to market, so findings are fixed before any LOI. Boutiques publish 2 to 4 weeks of work once data arrives (Midwest CPA). With an SBA buyer at $3 million or more, a second, lender-ordered QoE follows the LOI and must be engaged by the time the SBA Loan Number is issued under PLP processing.
- Before marketing: commission the sell-side QoE; budget about 4 weeks, per Midwest CPA.
- Marketing and LOI: share the report with buyers; note which buyers plan SBA 7(a) financing.
- SBA Loan Number issued: under PLP, the lender’s QoE vendor is retained with an engagement letter in place.
- Lender QoE fieldwork: cash proof for the trailing 12 months and two fiscal years; tie-out to tax returns and IRS transcripts.
- Loan sizing: the lender sets Debt Service Coverage on QoE earnings and cuts the loan if coverage falls short.
- Closing: any gap between price and supported value is filled by buyer equity or a renegotiated price.
Is a sell-side quality of earnings worth the fee?
A sell-side quality of earnings pays when the EBITDA it protects, times the buyer’s multiple, exceeds the fee. Divide the quoted fee by the multiple to get break-even EBITDA, then compare it with add-backs that lack a paper trail. At the Midwest CPA starting price of $25,000 and an illustrative 5x multiple, break-even is $5,000 of EBITDA.
- Take the quoted fee (F), including any change-order allowance.
- Take the buyer’s multiple (M).
- Divide F by M to get break-even EBITDA.
- Total your exposed add-backs, those backed by a story rather than payroll records, leases or invoices; see which add-backs buyers accept.
| Line | Example A (illustrative) | Example B (illustrative) |
|---|---|---|
| Quoted fee (F) | $25,000 (Midwest CPA sell-side starting price) | $60,000 (regional firm quote) |
| Buyer multiple (M) | 5x | 6x |
| Break-even EBITDA (F divided by M) | $5,000 | $10,000 |
| Exposed add-backs | $40,000 owner perks with partial receipts | $125,000: $70,000 spouse salary with no written role plus a $55,000 settlement |
| Price at risk (exposed times M) | $200,000 | $750,000 |
| Exposed add-backs as a multiple of break-even | 8 times | 12.5 times |
Both illustrative examples clear break-even many times over; an owner with audited statements and one supported salary add-back usually does not. Test working capital separately: a disputed peg moves price dollar for dollar with no multiple (see our working capital peg guide) and often sets up a retrade.
Which QoE provider type fits your sale?
Choose the provider type from your buyer’s financing and your deal size. The SBA rule sets the one hard threshold: $3 million of Business Purchase Price for Initial Acquisition and Business Expansion loans. Above it, an SBA buyer brings a lender QoE regardless of yours; below it, a full sell-side QoE is optional and a clean tie-out to returns often does the job.
| If your situation is | Do this | Basis |
|---|---|---|
| If your buyer uses SBA 7(a) and the Business Purchase Price is under $3 million | Skip a full sell-side QoE; tie monthly books to filed returns | No SBA QoE trigger; at $350,000 or less the lender may value the business itself |
| If your SBA buyer’s price is $3 million or more | Expect a lender QoE; order sell-side work with a cash proof and tax return tie-out | SOP 50 10 8.1, Appendix 15, Para. C.1 |
| If the sale is an owner buyout or an ESOP | QoE Lite or none, unless the lender asks | Both are exempt from the SBA QoE rule |
| If you are selling to PE platforms in a run process | Three written quotes from national or regional CPA firms, full monthly working capital in scope | CT Acquisitions judgment |
| If large sponsors, public or cross-border acquirers are likely bidders | Ask a Big Four or national firm to quote vendor due diligence | CT Acquisitions judgment |
| If your books are cash basis with many owner add-backs | Commission the sell-side QoE before marketing | SOP 50 10 8.1 tests cash vs accrual and owner pay |
Not sure which QoE scope your buyers will expect?
Book a 15-minute call and we will map your likely buyer pool, its financing and the diligence it will run. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells.
What should you ask before hiring a quality of earnings provider?
Ask six questions before you sign and get the answers into the engagement letter: scope periods, fee structure, staffing, turnaround, reliance and lender acceptance. Each maps to a published term, such as the SBA cash proof periods in SOP 50 10 8.1 or the Midwest CPA fixed-fee and reliance-letter terms.
- Which periods and tests are in scope? Ask for the trailing 12 months plus two fiscal years with a cash proof (the SBA periods), monthly working capital and debt-like items.
- Is the fee fixed? Midwest CPA quotes fixed fees in writing; ask any firm for its hourly rate on scope changes.
- Who does the work? Get the named partner and manager and their QoE count in your industry.
- What is the turnaround? Published boutique figures are 2 to 3 weeks (WebAcquisition) and 2 to 4 weeks (Midwest CPA) from full data delivery.
- Can a buyer or lender rely on the report? Midwest CPA prices reliance letters as an add-on.
- Will a lender accept it? On SBA deals of $3 million or more, no: the lender orders its own independent QoE.
Once the report is in hand, our guide on how to read a quality of earnings report as a seller shows where buyers look first.
How we compiled this
In November 2026 we read the QoE or financial due diligence page of each of the 18 providers, SBA SOP 50 10 8.1 with SBA Information Notice 5000-880695, two SEC filings and three trade reports on firm combinations. Prices appear only where the provider publishes them on its own site. We left out aggregator lists, forum posts and fee ranges with no named source, including the per-firm price ranges in the earlier version of this page. This page carries no paid placements.
Frequently asked questions
Who performs quality of earnings?
Quality of earnings work is performed by CPA firms and financial due diligence specialists: the Big Four, national firms such as RSM US, Grant Thornton and BDO USA, regional firms such as Weaver and Kreischer Miller, and QoE boutiques such as Midwest CPA. For SBA 7(a) acquisitions of $3 million or more, the lender’s QoE must come from an independent, experienced financial professional under SOP 50 10 8.1.
Who are the big 4 in transaction services?
The Big Four in transaction services are Deloitte, PwC, EY (through EY-Parthenon) and KPMG. Each runs a financial due diligence practice that covers earnings quality, working capital and debt-like items, and each offers sell-side or vendor due diligence. None of the four shows a QoE fee on the service pages we checked in November 2026.
How much does a quality of earnings cost?
Published prices run from $6,490 for the WebAcquisition QoE Lite to $40,000 for the Guardian Due Diligence advised tier, and the Midwest CPA sell-side QoE starts at $25,000 (firm websites, November 2026). National and Big Four firms quote per engagement and publish no price. Scope moves the fee most: periods covered, cash proof, working capital work and the number of entities.
What is a sell-side quality of earnings?
A sell-side quality of earnings is a QoE the owner commissions before marketing the business, so add-backs, working capital and revenue quality are tested before the buyer’s team tests them. Weaver notes that a buyer typically will not share adjustments that favor the seller. It does not replace the lender’s QoE on an SBA 7(a) acquisition of $3 million or more.
Can an SBA lender use the seller’s quality of earnings report?
Not as the required report. SBA SOP 50 10 8.1, Appendix 15, Para. C.1 says the QoE for an Initial Acquisition or Business Expansion of $3 million or more must be conducted for the benefit of the lender and must not be prepared by or for the seller. A buyer’s own QoE counts only after the lender’s approved vendor reviews it.
How long does a quality of earnings take?
Midwest CPA says most of its QoEs take 2 to 4 weeks and advises budgeting about 4 weeks; WebAcquisition quotes 2 to 3 weeks for a full QoE. The clock runs on how fast the seller delivers bank statements, tax returns and monthly closes. Under SBA PLP processing, the lender’s QoE must be engaged by the time the SBA Loan Number is issued.
Sources
All sources accessed November 7, 2026 unless a publication date is shown.
- SBA SOP 50 10 8.1, Lender and Development Company Loan Programs, Appendix 15 (effective October 1, 2026)
- SBA Information Notice 5000-880695, Issuance of SOP 50 10 8.1 (August 14, 2026)
- Midwest CPA, Quality of Earnings Analysis (pricing and scope)
- Guardian Due Diligence, Services (pricing tiers)
- WebAcquisition, How Much Does a QoE Report Cost? (Mushfiq Sarker)
- Kreischer Miller, Quality of Earnings Advisory Services (Full Scope vs QoE Lite)
- RSM US, Financial due diligence
- BDO USA, Due Diligence Advisory Services
- Plante Moran, Sell-Side Due Diligence
- Withum, Sell-Side Due Diligence
- Baker Tilly, Due Diligence
- Paysign, Inc. Form 8-K: Moss Adams merged with Baker Tilly US (June 3, 2025)
- Weaver, Quality of Earnings Report
- BPM, Quality of Earnings
- BPM, IPA 2026 Top 500 ranking release
- Eide Bailly, Quality of Earnings
- Forvis Mazars, Transaction Advisory
- Forvis Mazars, FORVIS and Mazars combination release (effective June 1, 2024)
- CBIZ, Completes Acquisition of Marcum, SEC Form 8-K Ex. 99.1 (November 1, 2024)
- INSIDE Public Accounting, Grant Thornton to Acquire CBIZ in $5 Billion Deal (July 29, 2026)
- CPA Practice Advisor, Grant Thornton Acquisition of CBIZ (November 2, 2026)
- Grant Thornton, Why seller readiness could shape the next M&A wave (May 18, 2026)
- EY, M&A due diligence
- PwC, Financial due diligence
- KPMG, Divestitures
- Deloitte, Acquisition and Vendor Due Diligence
About the Author
Christoph Totter is the founder of CT Acquisitions, an M&A advisory firm headquartered in Sheridan, Wyoming, that helps owners of founder-owned businesses make the most of their exit through a confidential sale, recapitalization or exit planning, with a 500+ buyer network. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells. Connect on LinkedIn · Book a call
Want a Specific Read on Your Business?
15 minutes, confidential, no contract. You leave with a read on your likely buyer pool and a likely valuation range. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells.
