
Dental DSO M&A and PE Roll-Up Tracker (2026): Active Platforms & Acquisitions
DSO M&A in 2026 is led by private-equity-backed groups: KKR controls Heartland Dental and Warburg Pincus backs MB2, but Mortenson Dental Partners is dentist and employee owned, and 17% of U.S. dentists were DSO-affiliated in 2025.
Key takeaways
- 17.0% of U.S. dentists were affiliated with a dental support organization (DSO) in 2025, up from 7.2% in 2015, and 31.4% of dentists less than five years out of dental school were (ADA Health Policy Institute, The U.S. Dentist Workforce, 2026 update).
- Heartland Dental, majority owned by KKR, supported 3,100 doctors in more than 1,880 locations across 39 states and DC after closing the 60-practice Smile Design Dentistry deal on September 8, 2025 (Heartland Dental).
- MB2 Dental took $525 million from Warburg Pincus on November 12, 2024 at an enterprise value above $3.5 billion, its third recapitalization in seven years (Charlesbank).
- Mortenson Dental Partners has no private equity investor: it reports 100% dentist and employee ownership through an ESOP, 156 practices and 10 states (Mortenson Dental Partners, accessed November 2026).
- Brian Colao of the law firm Dykema put smaller practices at about 5x to 6x EBITDA in 2026, down from about 7x at the 2019 to 2021 peak (Group Dentistry Now, June 2, 2026).
Weighing a DSO offer for your practice?
We run a confidential sale or recapitalization process for practice owners, with a 500+ buyer network. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells.
Which DSOs are buying dental practices in 2026, and who owns them?
Eleven DSOs with a dated public record lead DSO M&A for dentist sellers in 2026. Eight are backed by private equity sponsors such as KKR, Warburg Pincus, New Mountain Capital and Gryphon Investors; Allied OMS took its first minority investment in June 2025; PDS Health is led by its founder; and Mortenson Dental Partners is owned by its dentists and employees. Each row below links the release or report behind it.
| DSO | Owner or sponsor (since) | Latest dated event | Reported scale | Source |
|---|---|---|---|---|
| Heartland Dental | KKR majority (2018, from Ontario Teachers’, which kept a stake) | Closed Smile Design Dentistry, 60 practices in Central Florida and Tampa Bay, Sep 8, 2025 | 3,100 doctors, 1,880+ locations, 39 states and DC | Heartland, Sep 2025; Ontario Teachers’, 2018 |
| The Aspen Group (Aspen Dental) | Leonard Green, Ares Management, American Securities (American Securities-led recapitalization, 2015) | Exploring outside investors to handle about $3 billion of loans due the next year; nearing a sale of WellNow urgent care, May 19, 2026 | Not stated in the report | Bloomberg, May 2026 |
| MB2 Dental | Charlesbank (majority, 2021); Warburg Pincus ($525 million, 2024); KKR stays an investor | Recapitalization at an enterprise value above $3.5 billion, Nov 12, 2024 | 700+ doctor partners; 450+ partnerships added since 2021 | Charlesbank, Nov 2024 |
| PDS Health (Pacific Dental Services) | Founder and CEO Stephen Thorne IV; no sponsor named in the coverage | Headquarters moved to Henderson, Nevada; 36,000 sq ft building opened Apr 22, 2024 | 1,000+ supported practices, 24 states | OCBJ, Aug 5, 2024 |
| Sonrava Health (formerly Western Dental) | New Mountain Capital (November 2012) | Listed as a current New Mountain holding, November 2026 | 580+ offices, 20 states, 1,400+ doctors | New Mountain Capital |
| Smile Brands | Gryphon Investors (Aug 18, 2016) | Gryphon acquisition; terms not disclosed | Nearly 350 offices in 17 states at the 2016 deal | Gryphon Investors, 2016 |
| Mortenson Dental Partners | Dentists (about two-thirds) and an ESOP (about one-third); no private equity | Ownership model profiled, Mar 11, 2026 | 156 practices, 10 states | Mortenson; Group Dentistry Now, Mar 2026 |
| Dental365 | The Jordan Company via Resolute Fund V (2021); Regal Healthcare Capital Partners and founders kept minority stakes | Acquisition announced July 2021, closing August 2021; terms not disclosed | Nearly 70 locations and 165+ dentists in the New York area, Connecticut and New Jersey at the deal | Dentaltown, Aug 5, 2021 |
| Smile Doctors (orthodontics) | Linden Capital Partners and Thomas H. Lee Partners | Bought myOrthos, adding four states, 2025 | National orthodontic network | Lincoln International, 2025 |
| Specialized Dental Partners (specialty) | Quad-C Management | Southern Minnesota Periodontics & Dental Implants, Mankato, Sep 4, 2025, after 2025 add-ons in 8 other states | Periodontic, endodontic and specialty practices | Levin Associates, Sep 2025 |
| Allied OMS (oral surgery) | 65 Equity Partners, significant minority, with Everberg Capital (Jun 16, 2025); first institutional capital | Growth investment announced Jun 16, 2025; terms not disclosed | Surgeons in 50+ locations | 65 Equity Partners, Jun 2025 |
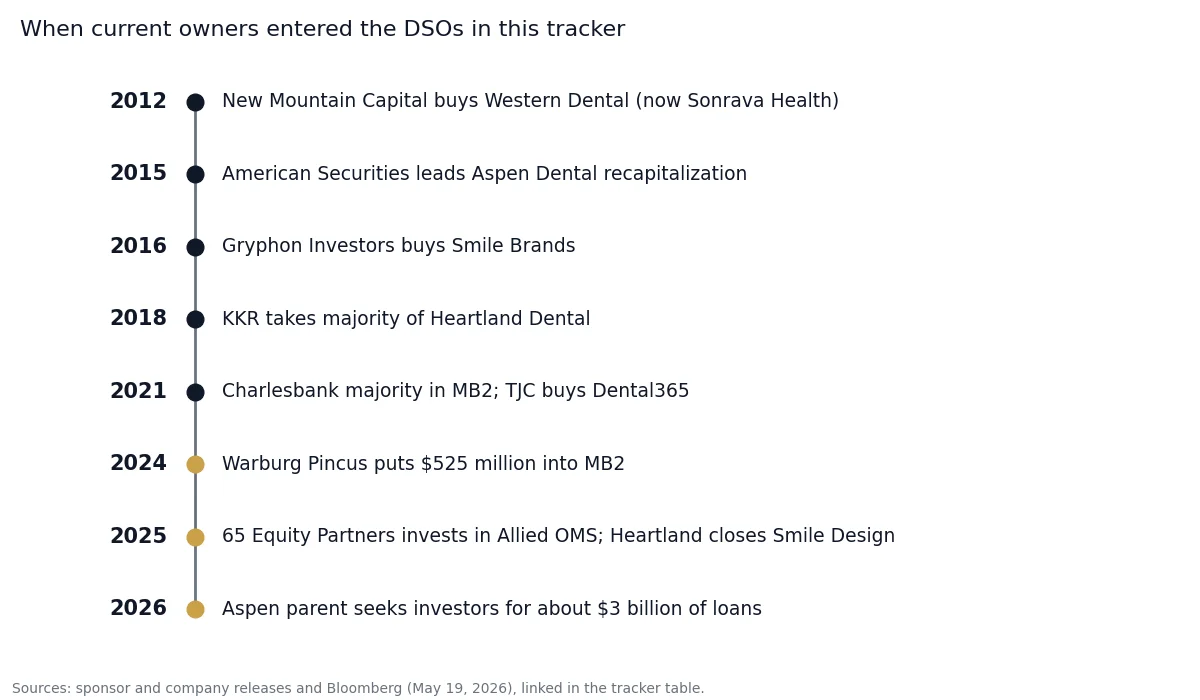
Hold periods vary widely. New Mountain Capital has owned Western Dental, now Sonrava Health, since November 2012, and Gryphon Investors has owned Smile Brands since August 2016. A rollover stake pays out only when the sponsor recapitalizes or sells, so ask each buyer when that event is planned. Aspen Dental’s parent is a separate case: Bloomberg reported in May 2026 that it was seeking outside investors for about $3 billion of loans. For the step-by-step sale process, see our guide to selling a dental practice to a DSO.
Who owns Mortenson Dental Partners?
Mortenson Dental Partners has no private equity owner. As of November 2026, its website states that the DSO is owned entirely by the dentists it supports and by team members through an employee stock ownership plan (ESOP), with 156 practices in 10 states. Group Dentistry Now reported on March 11, 2026 that doctors own about two-thirds and the ESOP trust about one-third.
Mortenson began as a single location in 1979 and runs its support center in Louisville, Kentucky. Earlier versions of this tracker, and some trade lists, attributed Mortenson to private equity sponsors; we found no release from Mortenson or any sponsor that supports that, and the company’s own page says otherwise. For a dentist seller, the difference shows up in the equity: Mortenson equity is held by dentists and staff, not a fund with a sale date.
How many dentists are affiliated with a DSO?
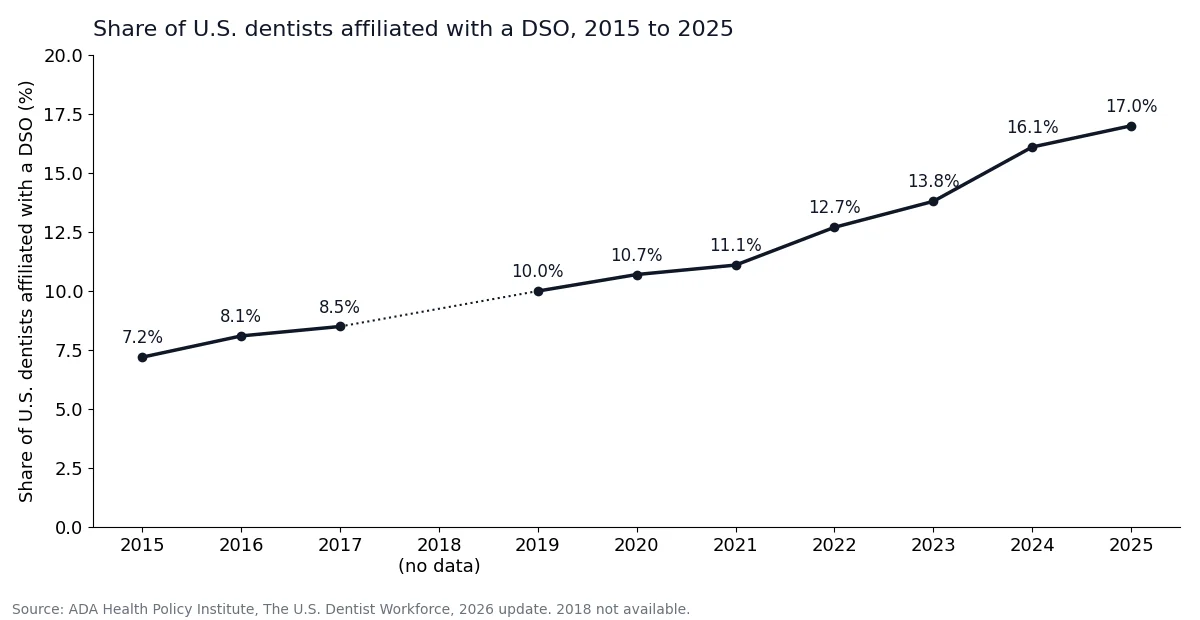
About one in six: 17.0% of U.S. dentists were affiliated with a DSO in 2025, according to the ADA Health Policy Institute’s U.S. Dentist Workforce report, 2026 update. The share has risen about one percentage point a year from 7.2% in 2015. HPI notes that data for 2018 is not available, so the series skips that year.
| Year | Share of U.S. dentists affiliated with a DSO | Source |
|---|---|---|
| 2015 | 7.2% | ADA HPI, U.S. Dentist Workforce, 2026 update (2018 not available) |
| 2016 | 8.1% | |
| 2017 | 8.5% | |
| 2019 | 10.0% | |
| 2020 | 10.7% | |
| 2021 | 11.1% | |
| 2022 | 12.7% | |
| 2023 | 13.8% | |
| 2024 | 16.1% | |
| 2025 | 17.0% |
Which dentists join DSOs?
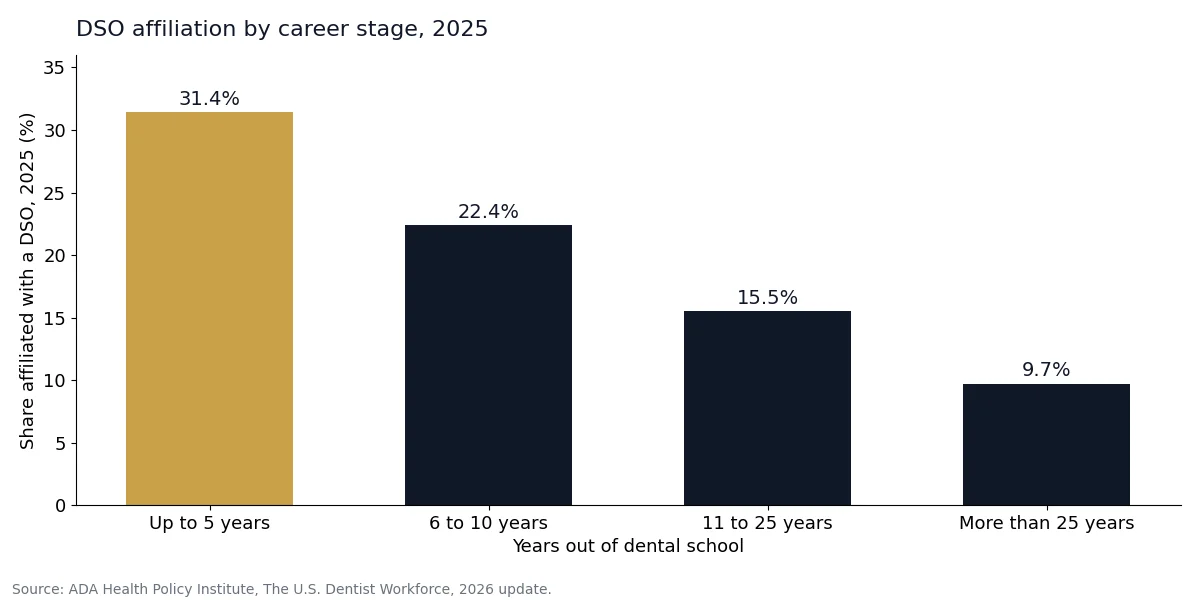
Younger dentists join DSOs most. In 2025, 31.4% of dentists less than five years out of dental school were DSO-affiliated, against 9.7% of those more than 25 years out, per the same ADA HPI report. That gap is why DSOs can staff an acquired practice with associates after the selling owner steps back.
| Years out of dental school | DSO-affiliated, 2019 | DSO-affiliated, 2025 |
|---|---|---|
| Up to 5 | 20.8% | 31.4% |
| 6 to 10 | Not broken out here | 22.4% |
| 11 to 25 | Not broken out here | 15.5% |
| More than 25 | 4.2% | 9.7% |
Geography matters as much as age. About one-quarter of dentists in Nevada, Arizona, Colorado, Oklahoma, Georgia and Florida were DSO-affiliated in 2025, and Colorado gained the most from 2015 to 2025, up 18.5 percentage points (ADA HPI). In Nevada, more than half of dentists less than five years out of school work in DSOs.
Private equity is a subset of that picture: an ADA HPI paper in Health Affairs found dentists affiliated with private equity rose from 6.6% in 2015 to 12.8% in 2021, with 96 private equity dental transactions in 2021 (ADA News, Aug 6, 2024).
What does a DSO deal pay a dentist seller?
A DSO offer pays a dentist in four parts: cash at closing, rollover equity in the DSO, an employment agreement to keep treating patients, and a lower personal income afterward because the practice profit now goes to the buyer. The headline multiple sets the price of that profit; the other three parts decide what you take home. Read each against the letter of intent.
| Deal part | What it means for the dentist | What to ask before signing | Source |
|---|---|---|---|
| Cash at close | The part of the price paid at closing, after practice debt, escrow and holdbacks | The cash figure after every deduction, not the enterprise value | Your letter of intent |
| Rollover equity in the DSO | Part of the price reinvested in the DSO or its holding company; paid out at a later recapitalization or sale | Which entity issues the units, what ranks ahead of them, and what happens to them if you leave early | MB2 offered doctor partners liquidity in its third recap in seven years (Charlesbank, 2024); Colao says sellers expected a second payout within 3 to 5 years and some are still waiting |
| Associate employment | You keep treating patients for a set term as an employee or contractor of the affiliated practice | Term in years, days per week, and whether pay is a percentage of your own collections | Employee dentists worked 2.5 fewer hours a week than owners in 2025 (ADA HPI) |
| Compensation reset | Your income falls from owner profit plus wage to clinical pay only | Your take-home before and after closing, modeled line by line | Average general dentist net income was $215,320 in 2025 (ADA HPI) |
| Clinical control and covenants | Non-compete radius and term; who sets clinical policy | In California, whether the management agreement fits SB 351 | SB 351, in force Jan 1, 2026, bars PE groups and hedge funds from interfering with dental clinical judgment (CDA, Oct 8, 2025) |
What multiples are DSOs paying in 2026?
Multiples have come down from the peak. Brian Colao, who leads the DSO industry group at Dykema, told Group Dentistry Now in June 2026 that large DSO deals now trade at about 9x to 10x EBITDA, against 13x to 16x in 2019 to 2021, and smaller practices at about 5x to 6x, against about 7x. Those are one practitioner’s ranges, not a dataset, so test your own number with our dental practice valuation calculator.
How does rollover equity get paid out?
Rollover equity pays only when the DSO’s owner recapitalizes or sells. MB2 Dental did that three times in seven years, most recently with Warburg Pincus in November 2024 at an enterprise value above $3.5 billion. Colao describes the opposite case: dentists who rolled equity expecting a second transaction within three to five years and are still waiting. Our equity rollover guide covers how the units work, and the recapitalization guide covers the payout event.
Worked example: what a 6x DSO offer means for your income
The price a DSO pays buys the practice profit, so the owner’s income resets to clinical pay after closing. The example below is illustrative: the inputs are round numbers we chose, and only the 5x to 6x range comes from a source (Colao, Group Dentistry Now, June 2026). Swap in your own collections, production and pay terms.
| Line (illustrative) | Amount | How it is calculated |
|---|---|---|
| Annual practice collections | $1,600,000 | Illustrative input |
| Selling dentist’s own production | $900,000 | Illustrative input |
| Clinical pay after the sale | $270,000 | 30% of $900,000 own production (illustrative rate) |
| Adjusted EBITDA the DSO buys | $320,000 | Profit after paying the dentist $270,000 (illustrative) |
| Enterprise value at 6x | $1,920,000 | 6 × $320,000; top of Colao’s 5x to 6x for smaller practices |
| Rollover equity at 20% | $384,000 | 20% × $1,920,000 (illustrative share) |
| Cash at close, before debt, fees and tax | $1,536,000 | $1,920,000 minus $384,000 |
| Owner take-home per year before the sale | $590,000 | $270,000 pay plus $320,000 profit |
| Take-home per year after the sale | $270,000 | Clinical pay only |
| Rollover value at the next recap, if equity is worth 0.5x, 1.0x or 2.0x what you rolled | $192,000 / $384,000 / $768,000 | $384,000 × 0.5, 1.0 or 2.0 |
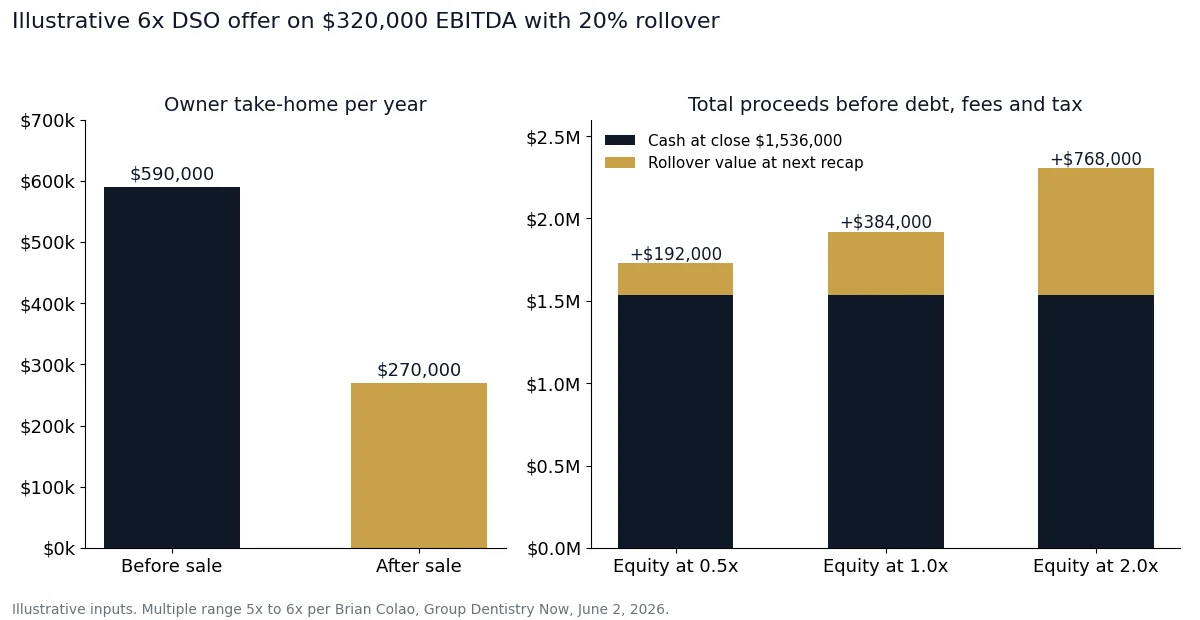
Read the result this way: the $320,000 a year you give up is the EBITDA you sold, and 6x pays you six years of it, before tax, partly in cash and partly in equity you cannot sell yourself. If you would keep practicing anyway, compare the $1,536,000 at closing with what $320,000 a year would earn you over the same six years as the owner. Our guide to how to sell a dental practice covers the tax side, and the dental practice sale agreement guide covers the contract terms.
Should you sell your practice to a DSO?
Sell to a DSO when the cash at close and the employment terms work on their own, and treat rollover as a bonus with a date you have asked about. The table turns the tracker and the ADA HPI data into rules for common seller situations in 2026.
| If your situation is | Then | Why |
|---|---|---|
| You want to stop clinical work within 2 years | Push for more cash at close and less rollover | Rollover often pays only at a recap 3 to 5 years out (Colao), and leaving early can affect the units |
| You plan to practice 5 or more years after closing | Consider a larger rollover, but only with a buyer whose sponsor has a stated exit plan | MB2 paid doctor partners at three recaps in seven years; other sponsors have held since 2012 or 2016 |
| The DSO’s parent has large debt maturing | Ask how your equity ranks behind the loans before you sign | The Aspen Group was handling about $3 billion of loans due the next year (Bloomberg, May 2026) |
| You practice in California | Have counsel check the management agreement against SB 351 | The law, in force since Jan 1, 2026, limits PE control of clinical decisions and some contract clauses |
| You want equity held by dentists, not a fund | Include a dentist-owned group such as Mortenson in your outreach | Mortenson reports 100% dentist and employee ownership, 156 practices in 10 states |
| Your practice is in Nevada, Arizona, Colorado, Oklahoma, Georgia or Florida | Ask several DSOs for offers before accepting the first | About one-quarter of dentists there were DSO-affiliated in 2025 (ADA HPI) |
| You run an orthodontic, oral surgery or periodontic practice | Add specialty platforms such as Smile Doctors, Allied OMS and Specialized Dental Partners | Each bought or raised capital for specialty practices in 2025 |
If you want a second opinion on an offer you already hold, our dental practice M&A advisor page explains how a sell-side process works for a practice owner.
How we compiled this
We compiled this page in November 2026 from 19 primary and trade sources, all linked below: the ADA Health Policy Institute’s 2026 workforce report, ADA News, sponsor and company releases and pages (Heartland, Ontario Teachers’, Charlesbank, Gryphon, New Mountain, 65 Equity Partners, Mortenson) and named trade or law-firm reports. Every DSO row needed a dated public record; we dropped 10 platforms from the earlier version of this tracker that we could not tie to one, and excluded forum posts and unattributed multiples.
Frequently asked questions
What is DSO M&A?
DSO M&A is the buying and selling of dental practices and dental support organizations, usually by private-equity-backed groups. A DSO buys or affiliates with a practice and runs its business side. In 2025, 17.0% of U.S. dentists were DSO-affiliated, per the ADA Health Policy Institute, up from 7.2% in 2015.
Is every DSO owned by private equity?
No. Most large DSOs have a private equity sponsor, such as KKR at Heartland Dental or New Mountain Capital at Sonrava Health, but Mortenson Dental Partners reports 100% dentist and employee ownership, and PDS Health is led by founder Stephen Thorne IV. An ADA HPI study found 12.8% of dentists were affiliated with private equity in 2021.
Who owns Mortenson Dental Partners?
Mortenson Dental Partners is owned by its dentists and employees, not private equity. As of November 2026, its website reports 100% dentist and employee ownership through an ESOP, with 156 practices in 10 states. Group Dentistry Now reported in March 2026 that doctors hold about two-thirds and the ESOP trust about one-third.
Is Aspen Dental struggling financially?
Bloomberg reported on May 19, 2026 that The Aspen Group, Aspen Dental’s parent, was exploring outside investors to handle roughly $3 billion of loans due the next year as earnings weakened, and was nearing a sale of WellNow urgent care. Its owners are Leonard Green, Ares Management and American Securities.
What happens to a dentist’s pay after selling to a DSO?
Pay usually drops to clinical compensation, because the practice profit now belongs to the DSO. In our illustrative example, take-home falls from $590,000 to $270,000 a year, and the $320,000 difference is the EBITDA the DSO bought at 6x. For scale, the ADA HPI put average general dentist net income at $215,320 in 2025.
What multiple do DSOs pay for a dental practice in 2026?
Brian Colao of Dykema told Group Dentistry Now in June 2026 that smaller practices trade at about 5x to 6x EBITDA, down from about 7x at the 2019 to 2021 peak, and large DSO deals at about 9x to 10x, down from 13x to 16x. Your number depends on EBITDA after a market clinical wage.
Sources
All sources accessed November 2026.
- ADA Health Policy Institute, The U.S. Dentist Workforce, 2026 update (data as of November 2026)
- ADA News, HPI: More new dentists affiliated with DSOs (Nov 17, 2025)
- ADA News, Private equity affiliation among dentists increases (Aug 6, 2024)
- Heartland Dental, Heartland Dental closes key transaction with Smile Design Dentistry (Sep 8, 2025)
- Ontario Teachers’ Pension Plan, KKR to acquire majority interest in Heartland Dental (2018)
- Bloomberg, Aspen Group eyes new investors to address debt as earnings slump (May 19, 2026)
- Charlesbank, MB2 Dental announces recapitalization event with new investor Warburg Pincus (Nov 12, 2024)
- Orange County Business Journal, PDS Health (Aug 5, 2024)
- New Mountain Capital, portfolio page: Sonrava Health (accessed November 2026)
- Gryphon Investors, Gryphon Investors acquires Smile Brands (Aug 18, 2016)
- Mortenson Dental Partners, company website (accessed November 2026)
- Group Dentistry Now, 3 DSO models, 1 mission: ownership, capital and the future of group dentistry (Mar 11, 2026)
- Group Dentistry Now, Cautious optimism: the DSO M&A market in 2026 (Brian Colao, Dykema) (Jun 2, 2026)
- Dentaltown, Dental365 to be acquired by The Jordan Company (Aug 5, 2021)
- Lincoln International, myOrthos has been sold to Smile Doctors (2025)
- Levin Associates, PE-backed Specialized Dental Partners expands presence in Minnesota (Sep 4, 2025)
- 65 Equity Partners, Allied OMS announces strategic growth investment (Jun 16, 2025)
- California Dental Association, New CDA-sponsored law protects against private equity interference (SB 351) (Oct 8, 2025)
- Kirkland & Ellis, Kirkland represents TJC on Dental365 (July 2021)
About the Author
Christoph Totter is the founder of CT Acquisitions, an M&A advisory firm that helps owners make the most of their exit, headquartered in Sheridan, Wyoming. We work directly with 500+ buyers, search funders, family offices, lower middle-market PE, and strategic consolidators, including direct mandates with the largest consolidators that other intermediaries cannot access. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells. Connect on LinkedIn · Get in touch
Next steps: If you’re selling your dental practice to a DSO, we run a confidential sell-side process, paid on success at closing. No public listing; introductions go only to matched buyers in our 500+ active capital partner network.
Read next: the 2026 LMM Buyer Mandate Report, a 4,500-word proprietary research piece on the 500+ active U.S. lower-middle-market buyers, mapped by EBITDA band, sector, and deal structure.
Want a Specific Read on Your Business?
15 minutes, confidential, no contract, no cost. You leave with a read on your local buyer market and a likely valuation range.
