
Construction Business Valuation Multiples in 2026: General Contractors, Specialty Trades and Heavy Civil
Quick Answer
Construction business valuation in 2026: small contractors sell for about 2.54x seller’s discretionary earnings (BizBuySell), PE-backed specialty trades for 5.7x to 8.2x EBITDA (GF Data), and disclosed heavy civil deals for 5.45x to 9.2x EBITDA.
By Christoph Totter, Founder of CT Acquisitions · Last reviewed: November 2026
Thinking about selling your construction business?
Skip the formulas. A 15-minute confidential call gives you a real valuation range and tells you which buyers would compete for your business. No cost, no obligation.
Key takeaways
- Construction and building businesses sold through BizBuySell from 2017 to 2025 averaged 2.54x seller’s discretionary earnings (SDE) and 0.56x revenue.
- PE-backed specialty trade contractors (NAICS 238) averaged 6.3x EBITDA in GF Data’s April 2025 report, from 5.7x at $10M to $25M of enterprise value up to 8.2x at $100M to $500M.
- Disclosed heavy civil deals ran from 5.45x run-rate EBITDA (Construction Partners’ cash for Lone Star Paving, 2024) to a blended 9.2x (Granite’s Warren Paving and Papich, 2025).
- Bonds do not travel with the business: the surety re-underwrites the buyer, and the Miller Act, 40 U.S.C. 3131, requires performance and payment bonds on federal construction contracts above $100,000.
- Net overbillings on the WIP schedule are cash the buyer expects to stay in the company at closing; in the worked example below, $1,300,000 of swept overbillings cuts the seller’s proceeds by the same amount.
What is a construction business worth in 2026?
A construction business is worth a multiple of its normalized earnings, checked against its equipment and backlog. Owner-run contractors under about $1M of earnings sell on SDE at roughly 2.5x to 2.7x on BizBuySell data. Contractors large enough for private equity sell on EBITDA at 5.7x and up. The segment (general contractor, specialty trade or heavy civil), the WIP schedule and the bonding line decide where in the range a company lands.
| Key number | Figure | Source |
|---|---|---|
| Construction and building, sold 2017 to 2025 | 2.54x SDE, 0.56x revenue (averages) | BizBuySell benchmarks |
| Heavy construction, sold businesses | 2.71x SDE, 0.58x revenue (averages) | BizBuySell heavy construction |
| Specialty trades NAICS 238, PE deals | 5.7x to 8.2x EBITDA by size, 6.3x average | GF Data, April 2025 |
| All industries, PE deals, 2024 | 7.2x EBITDA (379 deals) | GF Data, April 2025 |
| Public engineering and construction companies | 17.18x EV/EBITDA (48 firms) | Damodaran, NYU Stern, January 2026 |
| SBA surety bond guarantee ceiling | $9 million per contract, $14 million federal | Federal Register, Feb 15, 2024 |
The public-company figure is a ceiling, not a target. Damodaran’s 48 listed engineering and construction firms trade at 17.18x EBITDA because they are liquid, diversified and large; a private contractor with one estimator and one surety line prices closer to the BizBuySell and GF Data rows. Read the difference between SDE and EBITDA before comparing any two of these numbers.
What multiples do general contractors, specialty trades and heavy civil firms sell for?
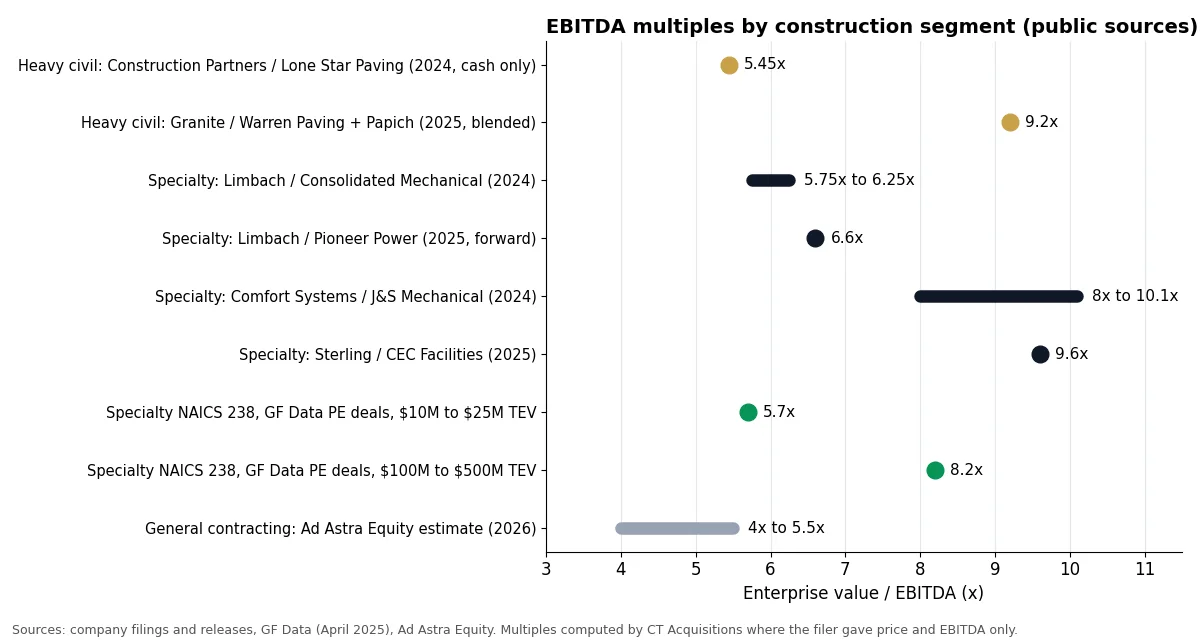
Specialty trade contractors carry the best public data and the highest private multiples: GF Data shows 5.7x to 8.2x EBITDA for PE deals, and four disclosed 2024 to 2025 public-buyer deals priced at 5.75x to 10.1x. Heavy civil deals with asphalt plants and aggregates priced at 5.45x to 9.2x. General contractors have no public deal data at scale; Ad Astra Equity estimates 4.0x to 5.5x.
The North American Industry Classification System (NAICS) splits construction, sector 23, into three subsectors, and buyers price them differently. NAICS 236 (construction of buildings) holds general contractors, who subcontract much of the work and earn thin fees on large revenue. NAICS 237 (heavy and civil engineering) holds road, utility and site contractors with large equipment fleets and public-agency customers. NAICS 238 (specialty trade contractors) holds electrical, mechanical, plumbing and roofing firms, where repeat service work lifts margins; GF Data’s NAICS 238 sample shows an 18.5% average EBITDA margin.
| Segment | Deal or dataset | Price and earnings | EBITDA multiple | Source |
|---|---|---|---|---|
| Specialty (238) | Limbach / Consolidated Mechanical, Dec 2024 | $23M plus up to $2M earn-out on $4M EBITDA | 5.75x to 6.25x | Limbach release |
| Specialty (238) | Limbach / Pioneer Power, Jul 2025 | $66.1M on $10M forward EBITDA | 6.6x | Limbach 8-K |
| Specialty (238) | Comfort Systems USA / J&S Mechanical, Feb 2024 | $120.6M on $12M to $15M EBITDA | 8.0x to 10.1x | Comfort Systems 10-Q |
| Specialty (238) | Sterling Infrastructure / CEC Facilities Group, 2025 | $505M upfront on $51M to $54M 2025 EBITDA | 9.6x at midpoint | Sterling 8-K |
| Heavy civil (237) | Construction Partners / Lone Star Paving, Oct 2024 | $654M cash plus 3 million shares on $120M run-rate EBITDA | 5.45x on cash alone | Construction Partners 8-K |
| Heavy civil (237) | Granite / Warren Paving and Papich, Aug 2025 | $710M combined | 9.2x blended (Granite) | Granite release |
| General contracting (236) | Advisor estimate | No deal-level data | 4.0x to 5.5x | Ad Astra Equity, 2026 |
| All construction | Advisor estimate | No deal-level data | 2.0x to 5.0x | Sofer Advisors |
Every public deal above involved a target earning $4M or more of EBITDA and a listed buyer with a stated growth plan. Below that size the GF Data floor of 5.7x applies only to companies large enough for PE, and owner-run contractors fall back to the SDE multiples in the BizBuySell rows. Segment-specific detail sits in our electrical contractor valuation guide, the mechanical contractor M&A multiples tracker and the excavation business valuation guide.
How do you value a construction company step by step?
Value a construction company in seven steps: normalize earnings, rebuild the WIP schedule, qualify the backlog, test the bonding line, restate equipment to fair market value, price the customer and safety risks, then apply a segment multiple and compare the result with the asset floor. Buyers’ quality of earnings (QoE) teams run the same sequence, so a seller who runs it first sees the price before the letter of intent does.
- Normalize earnings. Start from three years of CPA-reviewed statements. Add back owner pay above a market general manager salary and documented one-time costs; buyers reject undocumented add-backs, as our adjusted EBITDA add-backs guide shows line by line.
- Rebuild the WIP schedule. For every open job list contract value, estimated cost, cost to date, percent complete, earned revenue and billings. Recheck estimated cost on the five largest jobs; a raised cost estimate cuts profit in the period it is booked.
- Qualify the backlog. Count only signed, funded contracts with a notice to proceed. Divide qualified backlog by trailing revenue to get months of coverage.
- Test the bonding line. Write down the single-job and aggregate bonding limits and ask the surety, in writing, what it needs from a new owner.
- Restate equipment. Get a current appraisal and compare fair market value with net book value; the gap moves the asset floor and the tax allocation on IRS Form 8594.
- Price the risks. Measure the top customer’s share of revenue, the experience modification rate (EMR) and any prevailing wage exposure.
- Apply and reconcile. Multiply normalized earnings by the segment multiple, deduct risk discounts and any working capital shortfall, and compare the result with the adjusted net asset value.
How do over and under billings change the price?
Overbillings are cash collected ahead of the work, so a buyer treats them as an obligation to finish jobs it will not be paid for again. Under ASC 606 they sit as contract liabilities and underbillings as contract assets, netted per contract. A seller who sweeps net overbillings out as cash before closing loses that amount through the working capital adjustment.
The illustrative schedule below shows four open jobs for a $22,000,000 revenue specialty contractor. Percent complete is cost to date divided by estimated cost; earned revenue is percent complete times contract value; the over or under billing is billings minus earned revenue.
| Job (illustrative) | Contract | Est. cost | Cost to date | % complete | Earned revenue | Billed | Over (under) billed |
|---|---|---|---|---|---|---|---|
| Job A | $6,000,000 | $5,100,000 | $3,060,000 | 60% | $3,600,000 | $4,200,000 | $600,000 |
| Job B | $4,500,000 | $3,780,000 | $2,835,000 | 75% | $3,375,000 | $2,800,000 | ($575,000) |
| Job C | $8,000,000 | $6,960,000 | $2,088,000 | 30% | $2,400,000 | $3,700,000 | $1,300,000 |
| Job D | $3,200,000 | $2,720,000 | $2,448,000 | 90% | $2,880,000 | $2,855,000 | ($25,000) |
| Total | $21,700,000 | $18,560,000 | $10,431,000 | $12,255,000 | $13,555,000 | $1,300,000 net overbilled |
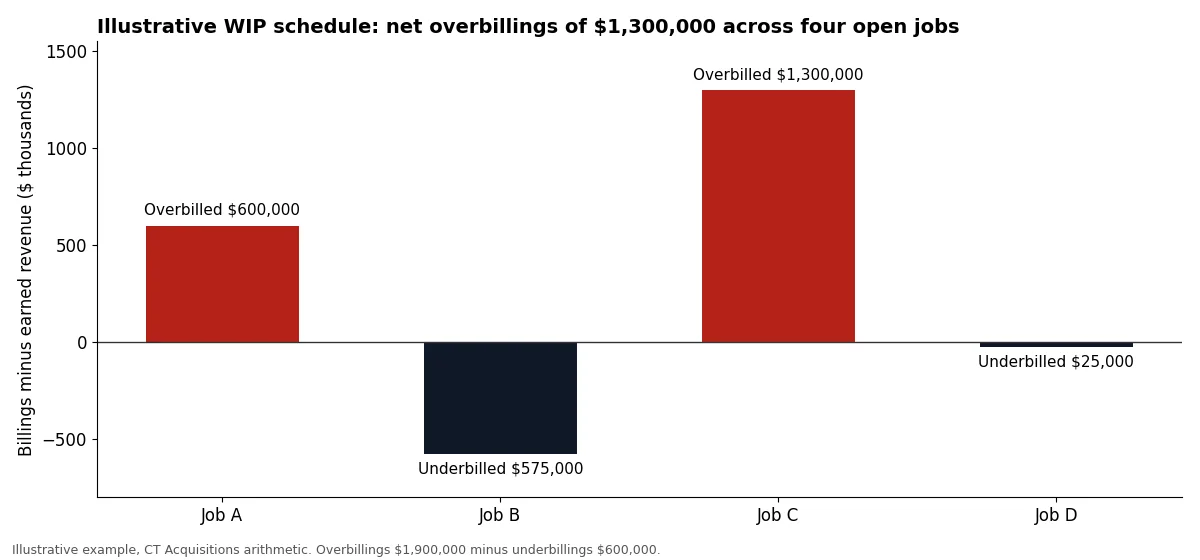
Job C is where a QoE team spends its time: it is 30% complete, $1,300,000 overbilled, and its profit rests on a cost estimate of $6,960,000. If the reviewer raises that estimate by $380,000, the lost profit comes straight out of normalized EBITDA. Retainage adds a second timing gap; on federal work FAR 32.103 limits it to 10 percent of approved progress estimates. Set the working capital target in the letter of intent, as our working capital adjustment guide explains.
How much is backlog worth to a buyer?
Backlog is worth what it proves about next year’s EBITDA, not its face value. Buyers count signed, funded contracts with a notice to proceed and ignore verbal awards and expected renewals. In the worked example, $15,400,000 of qualified backlog against $22,000,000 of trailing revenue covers 0.7 years, or 8.4 months, which supports the trailing earnings rather than adding a premium.
Backlog also carries margin risk. A fixed-price job signed before an input cost increase can turn a profitable backlog into a loss, so buyers ask for the estimated gross margin on each backlog line and compare it with the margin the same estimator earned on closed jobs. A backlog schedule that ties line by line to the WIP schedule and the signed contracts belongs in the data room checklist before the first buyer call.
Does bonding capacity transfer when you sell a construction company?
No: bonding capacity belongs to the surety relationship, not the company, and the surety re-underwrites the new owner’s balance sheet, indemnity and track record at a change of control. For contractors on public work this decides whether the backlog can be replaced, because the Miller Act requires a performance bond and a payment bond equal to the contract amount on federal jobs above $100,000.
Small contractors can lean on the SBA Surety Bond Guarantee program, which since March 18, 2024 covers contracts up to $9 million, or $14 million on federal work with a contracting officer’s certification. Ask the surety three questions before marketing the company: what working capital and net worth it requires from a buyer, whether it will issue a comfort letter at the letter of intent stage, and whether it needs your personal indemnity to continue for a transition period.
How does equipment change a construction company valuation?
Equipment sets the floor under the earnings value. Buyers restate the fleet from net book value to appraised fair market value and calculate an adjusted net asset value; when earnings are weak, that number governs. Heavy civil firms feel this most: Ad Astra Equity describes an asset floor built on orderly liquidation value at 60% to 75% of book for equipment-heavy contractors.
Book value understates most fleets. IRS Publication 946 places construction assets (asset class 15.0) on a 5-year recovery period, and the One Big Beautiful Bill Act (P.L. 119-21) restored 100% bonus depreciation under IRC 168(k) for property acquired after January 19, 2025. A two-year-old excavator can carry zero book value while it still resells at a market price. In an asset sale the gain over tax basis is depreciation recapture taxed as ordinary income, so the equipment line on Form 8594 matters to the seller; our tax guide for selling a business runs those numbers.
Which risks cut the multiple: concentration, EMR and prevailing wage?
Three risks cut construction multiples most often: one customer above 25% of revenue, an experience modification rate above 1.00, and unpaid prevailing wages on public jobs. Each is checkable in diligence, each transfers to the buyer in some form, and each is cheaper to fix 12 to 24 months before a sale than to discount at the letter of intent.
Customer concentration: CT Acquisitions treats a single customer above 25% of trailing revenue as a yellow flag and above 40% as a pricing issue, because that customer’s next award decides next year’s EBITDA; see how customer concentration cuts business value. Safety: under NCCI experience rating a 1.00 mod is the class average, built from three completed policy years, so a debit mod takes years to work off. Wages: the Davis-Bacon Act covers federally funded construction contracts above $2,000, and a buyer’s counsel will test certified payrolls against the wage determinations.
Worked example: valuing a $22 million specialty contractor
This illustrative example values a fictional commercial mechanical contractor with $22,000,000 of revenue, the WIP schedule above, and one customer at 38% of revenue. Every input is shown, the multiple is the GF Data NAICS 238 average for $10M to $25M of enterprise value, and the concentration discount is a CT Acquisitions assumption, not a published rate.
| Step (illustrative) | Input | Result |
|---|---|---|
| Reported EBITDA | From reviewed statements | $2,600,000 |
| Owner pay add-back | $420,000 paid vs $200,000 general manager | +$220,000 |
| WIP fade on Job C | Estimated cost raised by $380,000 | minus $380,000 |
| Normalized EBITDA | 2,600,000 + 220,000 minus 380,000 | $2,440,000 (11.1% margin) |
| Earnings value | $2,440,000 x 5.7 (GF Data, NAICS 238, $10M to $25M TEV) | $13,908,000 |
| Customer concentration | 0.5 turn x $2,440,000 (top customer 38%) | minus $1,220,000 |
| Enterprise value after risk | 13,908,000 minus 1,220,000 | $12,688,000 |
| Working capital shortfall | Net overbillings swept out as cash | minus $1,300,000 |
| Proceeds before debt and taxes | 12,688,000 minus 1,300,000 | $11,388,000 |
| Asset floor check | Book equity $4,800,000 + equipment uplift $2,250,000 ($3,400,000 appraised vs $1,150,000 book) | $7,050,000, below earnings value |
| Backlog check | $15,400,000 qualified / $22,000,000 revenue | 0.7 years (8.4 months) |
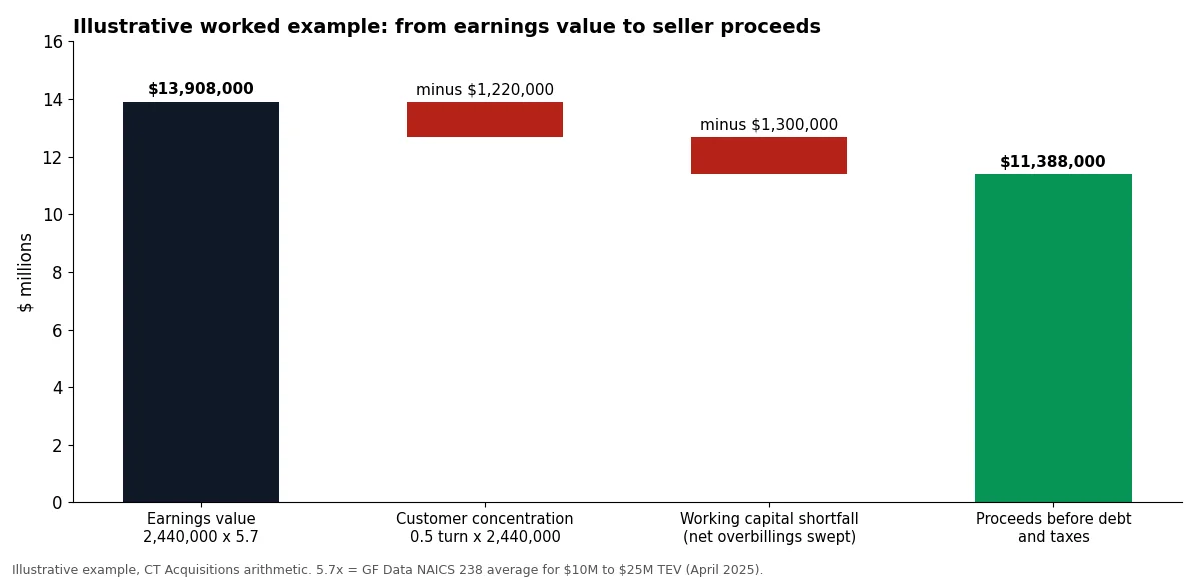
The earnings value of $13,908,000 equals 0.63x revenue, close to the 0.56x BizBuySell revenue average, which is a useful sanity check. The two deductions total $2,520,000, and both are in the seller’s control: leaving the net overbillings in the company avoids the $1,300,000 shortfall, and new work that brings the top customer below 25% of revenue would remove most of the concentration discount. Because the asset floor of $7,050,000 sits far below the earnings value, the equipment appraisal here mainly shapes the tax allocation rather than the price.
Selling a construction company? Talk to an advisor who knows the buyers.
We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells. A 15-minute call gets you three things: a realistic range for what your construction company is worth in today’s market, a sense of which buyer types fit your trade and scale, and the option to meet one of them. If none of it is useful, you’ve lost 15 minutes.
Which valuation path fits your construction company?
The right method follows from size, segment and asset intensity. Use this decision table to pick the earnings measure, the benchmark and the first fix; the thresholds come from the sources above and from CT Acquisitions working rules where marked. A company that fits two rows should be valued both ways, and the higher defensible number becomes the asking range.
| If your situation is | Value it on | Benchmark to use | Do this first |
|---|---|---|---|
| If the owner runs estimating and jobs, earnings under about $1M | SDE | 2.54x average (BizBuySell construction), 2.71x heavy construction | Document add-backs and name a second estimator |
| If you are a specialty trade with $1M+ EBITDA and service work | Adjusted EBITDA | 5.7x to 8.2x by size (GF Data NAICS 238) | Separate service and project margins in the financials |
| If you are a heavy civil or paving firm with a large fleet | Adjusted EBITDA and adjusted net asset value | 5.45x to 9.2x public deals; asset floor at appraised value | Order an equipment appraisal |
| If you are a general contractor on public work | Adjusted EBITDA | 4.0x to 5.5x (Ad Astra Equity estimate) | Ask the surety what a buyer needs to keep the line |
| If net overbillings exceed 5% of revenue (CT working rule) | Any method, then a working capital peg | Trailing 12-month average working capital | Leave overbilling cash in the company or price it in |
| If one customer is above 25% of revenue (CT working rule) | Any method, then a concentration discount | 0.5 turn in the illustrative example | Diversify for 12 to 24 months before marketing |
What do other guides get wrong about construction multiples?
Several ranking guides quote multiples two to four times higher than closed small-contractor deals because they mix public companies, PE platforms and revenue multiples without saying so. The primary data separates cleanly: SDE multiples near 2.5x for owner-run firms, EBITDA multiples of 5.7x to 8.2x for PE-sized specialty trades, and revenue multiples well under 1.0x.
| What a guide says | What the primary data shows | Source of the correction |
|---|---|---|
| First Page Sage: electrical contractors at 6.1x EBITDA below $1M of EBITDA | Owner-run construction firms averaged 2.54x SDE; PE deals start at 5.7x only above $10M of enterprise value | BizBuySell; GF Data |
| First Page Sage: electrical, plumbing and roofing at 3.8x to 4.2x revenue ($1M to $5M revenue) | Construction businesses averaged 0.56x revenue; Limbach paid 0.55x revenue for Pioneer Power | BizBuySell; Limbach 8-K |
| Viking Mergers: building construction at 9x to 11x EBITDA | 9x to 10x appears only in public-buyer deals for targets with $12M or more of EBITDA | Comfort Systems 10-Q; Sterling and Granite releases |
| Public construction stocks show what the sector is worth | Listed engineering and construction firms trade at 17.18x, about 2.4 times the 7.2x PE average for private deals | Damodaran; GF Data |
How we compiled this
We compiled this page from 19 primary or first-party documents accessed in November 2026: six company filings and releases (Limbach, Comfort Systems USA, Sterling Infrastructure, Construction Partners, Granite Construction), GF Data’s April 2025 report, BizBuySell benchmarks, Damodaran’s January 2026 dataset, and federal sources (40 U.S.C. 3131, FAR 32.103, the Federal Register, IRS Publication 946, Congress.gov, IRS Form 8594, NAICS, NCCI and the Department of Labor). Advisor estimates are labeled as estimates. Multiples marked as CT arithmetic divide a disclosed price by disclosed EBITDA. The worked example is illustrative, not a client. Forum posts were excluded.
Want to know what your construction business is worth?
Benchmarks give you a range. A 15-minute confidential call gives you a real number, based on what active buyers are paying right now and which ones would compete for your business. No cost, no obligation.
Frequently asked questions
How do I value my construction business?
Value a construction business by normalizing earnings (SDE below about $1M, adjusted EBITDA above), rebuilding the WIP schedule, and multiplying by a segment benchmark: 2.54x SDE for small firms on BizBuySell data, or 5.7x to 8.2x EBITDA for PE-sized specialty trades on GF Data. Then check the result against equipment at appraised fair market value.
What is a good EBITDA multiple for a construction company?
For a specialty trade contractor large enough for private equity, GF Data’s April 2025 report shows 5.7x EBITDA at $10M to $25M of enterprise value, rising to 8.2x at $100M to $500M. Public buyers paid 5.75x to 10.1x in four 2024 to 2025 specialty deals. General contractors price lower; Ad Astra Equity estimates 4.0x to 5.5x.
How much is a construction business worth with $1,000,000 in sales?
At the BizBuySell construction average of 0.56x revenue, $1,000,000 of sales points to about $560,000. A better method uses earnings: a contractor with $300,000 of seller’s discretionary earnings at the 2.54x average points to about $762,000. Margin moves the answer more than revenue, so two $1,000,000 contractors can be worth very different amounts.
Is a construction business worth 3 times profit?
For owner-run contractors, 3 times profit is slightly above the averages: BizBuySell reports 2.54x seller’s discretionary earnings for construction and 2.71x for heavy construction. Contractors with $1M or more of EBITDA, a management team and a bonding line move to EBITDA pricing, where PE-backed specialty trades averaged 6.3x in GF Data’s NAICS 238 sample.
How are heavy construction businesses valued?
Heavy civil and site contractors are valued on adjusted EBITDA and checked against adjusted net asset value, because their fleets are large. Disclosed deals ran from 5.45x run-rate EBITDA (Construction Partners’ cash for Lone Star Paving, 2024) to a blended 9.2x (Granite’s Warren Paving and Papich, 2025). Smaller heavy construction firms averaged 2.71x SDE on BizBuySell.
Does bonding capacity transfer when a construction company is sold?
No. The surety re-underwrites the buyer’s balance sheet, indemnity and experience at a change of control, so the seller’s line is not an asset the buyer receives. Federal jobs above $100,000 need performance and payment bonds under the Miller Act, 40 U.S.C. 3131, so ask the surety what a buyer must show before you sign a letter of intent.
Sources
- GF Data, Highlights and Products, Fourth Quarter 2024 (April 2025), NAICS 238 chart, accessed November 2026.
- BizBuySell, Building and Construction Valuation Benchmarks, accessed November 2026.
- BizBuySell, Heavy Construction Valuation Benchmarks, accessed November 2026.
- Aswath Damodaran, NYU Stern, Enterprise Value Multiples by Sector (US), January 2026, accessed November 2026.
- Limbach Holdings, Consolidated Mechanical acquisition release, December 2, 2024, accessed October 2026.
- Limbach Holdings, Form 8-K Exhibit 99.1, August 7, 2025, accessed October 2026.
- Comfort Systems USA, Form 10-Q, Q3 2024, accessed October 2026.
- Sterling Infrastructure, Form 8-K Exhibit 99.1, September 2, 2025, and June 17, 2025 announcement, accessed November 2026.
- Construction Partners, Form 8-K Exhibit 99.2, October 21, 2024, accessed November 2026.
- Granite Construction, Warren Paving and Papich Construction release, August 6, 2025, accessed November 2026.
- 40 U.S.C. 3131, Miller Act bonds, accessed November 2026.
- FAR 32.103, Progress payments under construction contracts, accessed November 2026.
- Federal Register, SBA Surety Bond Guarantee program limits, February 15, 2024, accessed November 2026.
- U.S. Department of Labor, Davis-Bacon and Related Acts, accessed November 2026.
- IRS Publication 946 (2025), How To Depreciate Property, accessed November 2026.
- Congress.gov, H.R. 1 (P.L. 119-21), One Big Beautiful Bill Act, accessed November 2026.
- IRS, About Form 8594, Asset Acquisition Statement, accessed November 2026.
- U.S. Census Bureau, NAICS 2022, sector 23 Construction, accessed November 2026.
- NCCI, experience rating, accessed November 2026.
- EisnerAmper, ASC Topic 606: Contract Assets and Liabilities for the Construction Industry, accessed November 2026.
- Ad Astra Equity, Construction Company Valuation and EBITDA Multiples (2026), advisor estimates, accessed November 2026.
- Sofer Advisors, How to Value a Construction Company, advisor estimate, accessed November 2026.
About the Author
Christoph Totter is the founder of CT Acquisitions, an M&A advisory firm that helps owners of founder-owned businesses make the most of their exit through confidential sales, recapitalizations and exit planning, headquartered in Sheridan, Wyoming, with a network of 500+ buyers. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells. Connect on LinkedIn · Get in touch
Related Guide: Restaurant Business Valuation: How to Estimate What Your Restaurant Is Really Worth, How tier-specific multiples drive restaurant exit outcomes.
Related Guide: SDE vs EBITDA: Which Metric Matters for Your Business, How to choose the right earnings metric, and why it changes valuation.
Related Guide: Buyer Archetypes: PE, Strategic, Search Fund, Family Office, How each buyer underwrites differently and what they pay for.
Related Guide: 2026 LMM Buyer Demand Report, Aggregated buy-box data from 76 active U.S. lower middle market buyers.
Related Guide: Business Valuation Calculator (2026), Quick starting-point valuation range based on SDE/EBITDA and industry.
Want a Specific Read on Your Business?
15 minutes, confidential, no contract, no cost. You leave with a view of your local buyer market and a likely valuation range.
Owners planning a 12- to 24-month runway can start with the seller prep hub for the pre-sale work that moves multiples.
