
Trucking Company Business Valuation in 2026: What Is My Transportation Business Worth?
Trucking company valuation in 2026: most small carriers sell for 2.35x to 3.75x seller’s discretionary earnings, the middle half of BizBuySell sales, with the fleet’s orderly liquidation value as the floor and equipment debt paid from the price.
Thinking about selling your trucking business?
Skip the formulas. A 15-minute confidential call gives you a real valuation range and tells you which buyers would compete for your business. No cost, no obligation.
Key takeaways
- Sold trucking companies priced at 2.35x to 3.75x SDE for the middle half, with a 3.00x average and a 0.65x revenue multiple, per BizBuySell.
- Truckload carriers ran operating margins below 1.0% in 2025 while costs hit a record $2.336 per mile, per ATRI’s July 15, 2026 release.
- Fleet debt comes out of the price: of the roughly $808 million enterprise value Knight-Swift paid for U.S. Xpress in July 2023, $484 million was assumed debt and finance leases, per FreightWaves.
- Asset-light brokerage earns a higher multiple: RXO paid $1.025 billion for Coyote Logistics in September 2024, about 11.9x 2023 pre-synergy adjusted EBITDA, per RXO.
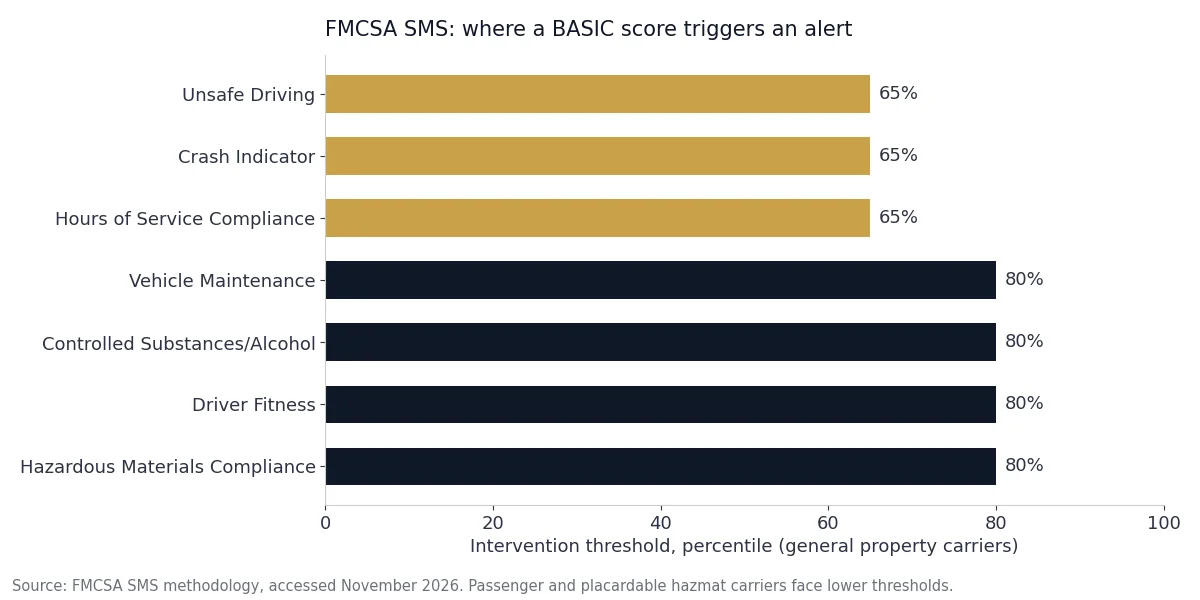
- FMCSA flags general carriers at the 65th percentile in Unsafe Driving, Crash Indicator and HOS Compliance and the 80th in Vehicle Maintenance, per the SMS methodology. A final unsatisfactory rating stops a general freight carrier on the 61st day under 49 CFR 385.13.
How much is a trucking company worth in 2026?
A trucking company is worth the higher of two numbers: its earnings times a market multiple, or what its tractors and trailers would bring in an orderly sale. For owner-run carriers, BizBuySell’s sold listings put the middle half at 2.35x to 3.75x SDE, with a 3.00x average. Equipment loans and leases are then paid from that price, so the owner’s check is smaller than the headline.
| Figure | Value | What it measures | Source |
|---|---|---|---|
| SDE multiple, middle half | 2.35x to 3.75x | Sold trucking companies | BizBuySell |
| Average SDE / revenue multiple | 3.00x / 0.65x | Sold trucking companies | BizBuySell |
| Median revenue / median owner earnings | $1,954,881 / $400,000 | Ratio of medians: 20.5% | BizBuySell; CT arithmetic |
| Truckload operating margin, 2025 | Below 1.0% | Fleet-reported costs vs revenue | ATRI, July 2026 |
| Average cost per mile, 2025 | $2.336 (2024: $2.260) | All-in operating cost | ATRI, July 2026 |
| Freight brokerage deal multiple | About 11.9x | Coyote Logistics, 2023 pre-synergy adjusted EBITDA | RXO, Sept 2024 |
Size changes the yardstick. Owner-run carriers are priced on seller’s discretionary earnings, which adds the owner’s pay back to profit; our guide to how SDE is calculated lists the add-backs. Carriers with a paid manager and $1M+ of EBITDA are priced on EBITDA, at higher multiples.
Timing matters too. Cass Information Systems reported September 2026 shipments up 1.9% year over year, the second gain after 42 months of declines, and its truckload linehaul index up 10.1%. Buyers price the next 12 months, so a recovery helps sellers.
Which valuation method fits a trucking company: earnings or fleet value?
Use both and take the higher. The income method values a carrier as a going concern: earnings times a multiple. The asset method values the fleet at orderly liquidation value, what the equipment would fetch in a marketed sale over a few months. When earnings are thin, as ATRI’s sub-1.0% truckload margins for 2025 suggest for many fleets, the fleet value sets the price.
| Method | What it measures | When it sets the price | Trucking watch-out |
|---|---|---|---|
| Earnings multiple (SDE or EBITDA) | Going-concern value | Healthy margins, contracted freight | Depreciation add-backs hide truck replacement cost |
| Fair market value of equipment | Willing buyer and seller, unit in use | Equipment-only deals | J.D. Power: retail sleeper prices fell 6.2% year over year in July 2026 |
| Orderly liquidation value (OLV) | Marketed sale over a few months, seller must sell | The floor when earnings value is lower | J.D. Power: auction prices rose 11.9% year over year in July 2026 |
| Discounted cash flow | Present value of forecast cash flow | Larger carriers with dedicated contracts | Spot-heavy fleets rarely support a forecast |
Do not add the fleet on top of the multiple. The trucks produced the earnings, so “3x SDE plus book value of equipment” counts them twice. Idle units, spare trailers and owned real estate that produce none of the earnings are the exceptions: sell them, or lease the yard to the buyer at market rent.
Equipment prices move on their own cycle. J.D. Power’s August 2026 Commercial Truck Guidelines show July auction prices for 3- to 6-year-old sleepers up 11.9% year over year, while retail prices for 3- to 5-year-old sleepers fell 6.2%. Firmer auction prices raise the OLV floor.
How do you value a trucking company step by step?
Rebuild two years of earnings, pick a multiple band, adjust it for the carrier’s risks, compare the result with the fleet’s orderly liquidation value, then subtract equipment debt. The worked example below runs those five steps on an illustrative 20-truck dry van carrier.
- Rebuild SDE or EBITDA. Add back owner pay, interest, depreciation and one-time costs to two years of tax returns; use the average.
- Pick a band. BizBuySell’s 2.35x to 3.75x SDE for owner-run carriers; EBITDA multiples once a paid manager runs dispatch.
- Adjust the multiple. Use the adjustments table further down.
- Get the fleet appraised. Fair market value and OLV unit by unit, with VIN, model year and mileage.
- Take the higher number, then subtract debt. Truck liens are paid at closing.
| Step | Arithmetic | Result |
|---|---|---|
| Carrier (illustrative) | 20 tractors, 40 dry van trailers, $4,000,000 revenue | $700,000 two-year average SDE |
| Earnings value, low | $700,000 x 2.35 | $1,645,000 |
| Earnings value, average | $700,000 x 3.00 | $2,100,000 |
| Earnings value, high | $700,000 x 3.75 | $2,625,000 |
| Adjusted multiple | 3.00x, minus 0.50x for 6.5-year fleet age, minus 0.25x for a 31% top customer | 2.25x |
| Adjusted earnings value | $700,000 x 2.25 | $1,575,000 |
| Fleet OLV | 70% of $2,000,000 retail fair market value (appraiser’s figure, assumed) | $1,400,000 |
| Price basis | Higher of $1,575,000 and $1,400,000 | $1,575,000 |
| Equipment debt paid at closing | Truck loans and trailer leases | Less $900,000 |
| Owner’s pre-tax proceeds | $1,575,000 less $900,000 | $675,000 |
| Fleet-only alternative | $1,400,000 less $900,000, before wind-down costs | $500,000 |
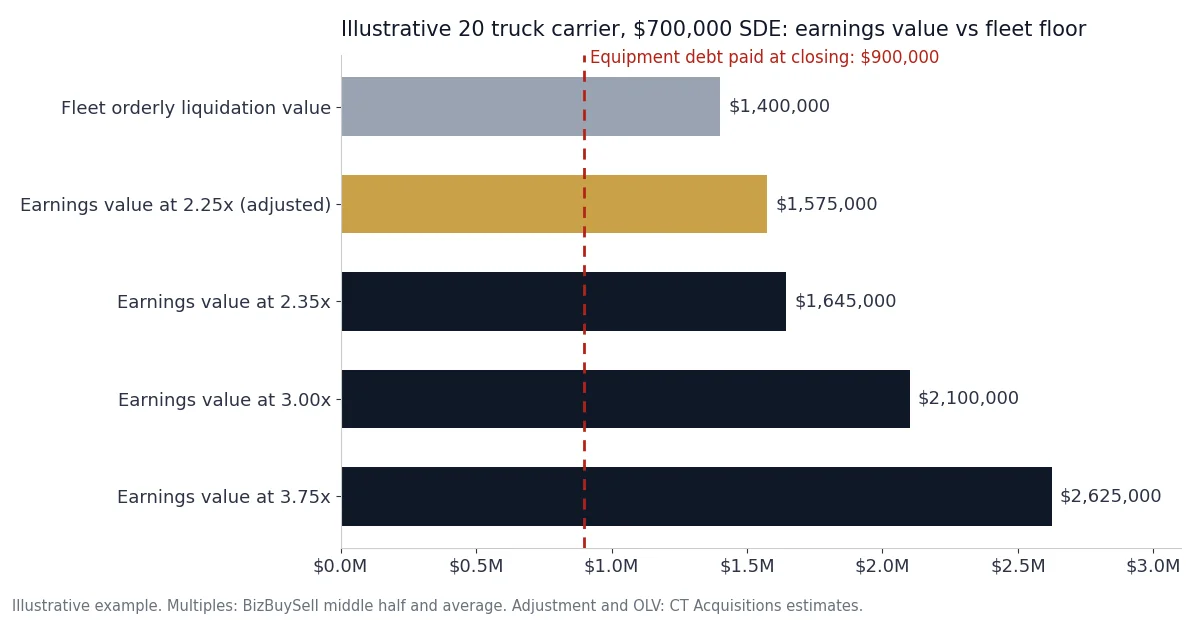
Read the gap, not the headline. In this example the going concern is worth $175,000 more than selling the iron. That gap is the price of the customers, drivers and authority; if yours is near zero, fixing earnings beats negotiating.
Cross-check the replacement cost hiding in SDE. ATRI’s 2025 average for truck and trailer payments was 40.4 cents a mile: $808,000 a year on 2,000,000 miles (20 tractors at an assumed 100,000 each). If paid-off trucks keep your P&L far below that, a buyer prices the replacement wave.
Why do freight brokerages sell for more than asset-based carriers?
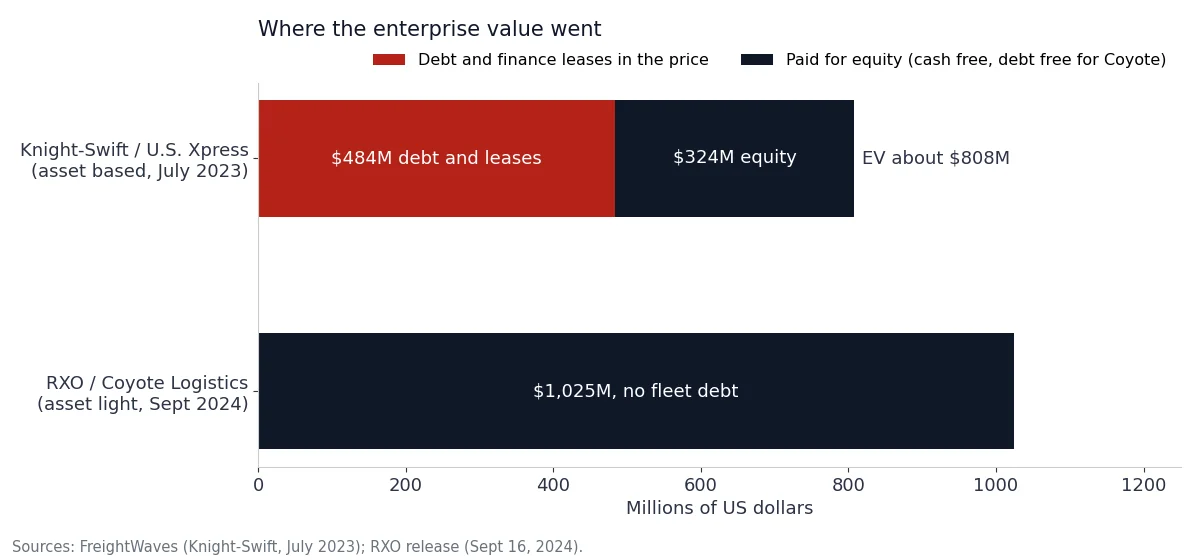
A brokerage owns no trucks, so its earnings turn into cash without a replacement program and no fleet debt comes out of the price. RXO paid about 11.9x 2023 pre-synergy adjusted EBITDA for Coyote Logistics on a cash-free, debt-free basis. Asset-based carriers sell at enterprise value, and fleet debt takes a large share before the owners are paid.
| Deal | Closed | Model | Enterprise value | Debt and leases in the price | Equity or multiple | Source |
|---|---|---|---|---|---|---|
| Knight-Swift / U.S. Xpress | July 1, 2023 | Asset-based truckload | About $808 million | $484 million assumed | $324 million equity ($6.15 a share) | FreightWaves |
| TFI International / Daseke | April 1, 2024 | Asset-based flatbed and specialized | $1.1 billion | Debt payoff included in the enterprise value | $8.30 a share in cash | CDLLife |
| RXO / Coyote Logistics | Sept 16, 2024 | Asset-light brokerage | $1.025 billion | None: cash-free, debt-free | About 11.9x 2023 pre-synergy adjusted EBITDA | RXO |
Price a mixed carrier in pieces. Fleets of 20 to 50 trucks often hold broker authority too. Split the P&L into asset revenue and brokerage net revenue (billings minus carrier pay) and value each on its own earnings; a multiple on gross billings overstates a brokerage, because most of each dollar passes to the hauling carrier.
Brokerage diligence has its own checklist: the $75,000 surety bond or trust fund required by 49 CFR 387.307, carrier vetting records, and how many shippers produce the net revenue. Our guide to selling a freight brokerage covers that process.
What do ATRI’s 2025 cost figures mean for your valuation?
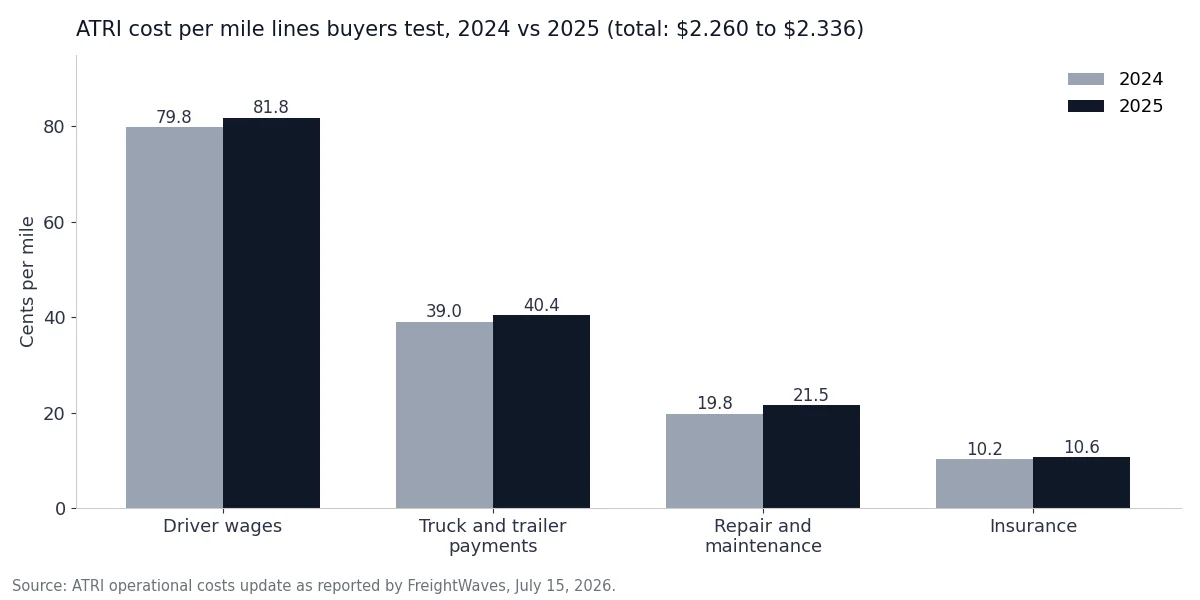
They show where a buyer will press. ATRI puts the average cost to run a truck at $2.336 a mile in 2025, up 3.4%, with truck and trailer payments at 40.4 cents and insurance at 10.6 cents, per FreightWaves’ report of the July 2026 update. A carrier that beats those averages, with documents, can defend the top half of its band.
| Line item | 2024 | 2025 |
|---|---|---|
| Total cost per mile | $2.260 | $2.336 |
| Cost per mile excluding fuel | $1.779 | $1.854 |
| Driver wages (cents per mile) | 79.8 | 81.8 |
| Truck and trailer payments (cents) | 39.0 | 40.4 |
| Repair and maintenance (cents) | 19.8 | 21.5 |
| Insurance (cents) | 10.2 | 10.6 |
| Driver turnover, industry average | 48% | 44.2% |
| Driver turnover, fleets under 26 trucks | n/a | 32% |
| Driver turnover, truckload fleets over 1,000 trucks | n/a | 70.7% |
Margins by segment explain why multiples differ by segment. ATRI reports 2025 operating margins below 1.0% for truckload and refrigerated, 4.0% for tank, an average loss of 0.5% for flatbed, and healthy but flat margins for LTL. Steadier tank earnings support a higher multiple than dry van.
Turnover gets benchmarked too. ATRI measured 32% at fleets under 26 trucks in 2025; a 15-truck carrier at 60% runs near twice that, and the buyer will ask what each refilled seat costs.
How do CSA scores and safety ratings change a trucking company valuation?
They decide whether a deal happens at all. FMCSA’s Safety Measurement System ranks carriers in seven BASICs; above a threshold, FMCSA may warn or investigate. A proposed unsatisfactory safety rating that becomes final stops a general freight carrier from operating on the 61st day under 49 CFR 385.13, which ends the going-concern value.
| BASIC | Threshold, general carriers | What a buyer reads into it |
|---|---|---|
| Unsafe Driving | 65% | Driver hiring and coaching |
| Crash Indicator | 65% | Insurance cost and verdict risk |
| Hours-of-Service Compliance | 65% | ELD and dispatch discipline |
| Vehicle Maintenance | 80% | Fleet age and shop quality |
| Controlled Substances/Alcohol | 80% | Testing program |
| Driver Fitness | 80% | Driver qualification files |
| Hazardous Materials Compliance | 80% | Hazmat program, placardable loads |
Buyers cannot see your percentiles on their own. Section 5223 of the FAST Act keeps property carrier percentiles and alerts off the public SMS site, so a buyer will ask you to export them with the inspection and crash history. Export 24 months of data before talks start.
The scoring is about to change. FMCSA’s notice of November 20, 2024 (89 FR 91874) replaces BASICs with Compliance Categories and groups 959 roadside violations into 116 violation groups; as of July 2026 no launch date had been announced. A carrier near a threshold today could cross it under the new math.
Ratings are separate from scores. Under 49 CFR 385.13, a carrier hauling placardable hazmat or passengers is barred from operating from the 46th day after a proposed unsatisfactory rating, and other carriers from the 61st day, with up to 60 more days if FMCSA finds a good-faith improvement effort. A Conditional rating does not stop operations, but buyers price it.
Can a buyer keep your USDOT number and MC authority?
Yes in a stock or membership-interest sale, because the company that holds the USDOT number and operating authority does not change. In an asset sale the buyer usually runs under its own numbers. FMCSA stopped reviewing and approving transfers of operating authority on October 22, 2013 (78 FR 52457), so there is no FMCSA approval period to wait for in either structure.
| Question | Stock or membership sale | Asset sale |
|---|---|---|
| USDOT number and MC authority | Stay with the company; update the MCS-150 | Buyer uses or applies for its own |
| Safety record and CSA data | Buyer inherits all of it | A new USDOT number starts 18 months of new entrant monitoring under 49 CFR 385.307 |
| Insurance | Insurer reviews the change of control | Buyer binds its own: at least $750,000 for general freight, $5,000,000 for certain bulk hazmat, under 49 CFR 387.9 |
| Past crashes and driver claims | Stay with the company; indemnity and escrow | Mostly stay with the seller |
| Tax for the seller | Mostly capital gain on the shares | Gain on equipment recaptured as ordinary income under IRC 1245; price allocated on IRS Form 8594 |
The new entrant clock is a hidden cost of an asset sale. A buyer under a fresh USDOT number spends 18 months in FMCSA’s new entrant program, and insurers price new authority as unproven, so a clean record is worth more sold with the company. Our comparison of asset sale vs stock sale covers the tax trade-off.
Which adjustments move a trucking multiple, and by how much?
Fleet age, customer concentration, safety record, driver model and segment move a trucking multiple most. The ranges below are CT Acquisitions estimates (illustrative), not survey data; use them to rank what to fix first, then test them against the letters of intent you receive.
| Factor | Premium side | Discount side | Move on the multiple (CT estimate) |
|---|---|---|---|
| Average tractor age | Under 4 years | Over 8 years | 6 to 8 years: minus 0.5x to 1x; over 8: minus 1x to 2x |
| Top customer share of revenue | Under 15% | Over 40% | 25% to 40%: minus 0.25x to 0.75x; over 40%: earnout structures |
| Safety record | No alerts, Satisfactory rating | Conditional, or 2+ alerts | Deal at risk before any multiple is discussed |
| Driver model | W-2, or owner-operators with own authority | Mostly 1099 under carrier control | Minus 0.25x to 0.75x; pure 1099 without own authority: minus 0.75x to 1.5x |
| Dispatch and data | TMS, ELD, dashcams | Paper logs and spreadsheets | Plus 0.25x to 0.5x |
| Segment | Reefer, tanker, hazmat, flatbed | Spot-market dry van | Specialized: plus 0.5x to 1.5x |
If one shipper is over 25% of revenue, expect part of the price to depend on that shipper staying after closing; our guides to customer concentration and valuation and to how earnouts work show the structures.
Driver classification follows the drivers into the deal. California’s AB5 applies the ABC test, which leased owner-operators rarely pass. Buyers’ counsel checks for leases that meet the Truth-in-Leasing rules in 49 CFR Part 376, drivers with their own authority, and a documented right to refuse loads.
Should you sell now, sell the fleet, or fix first?
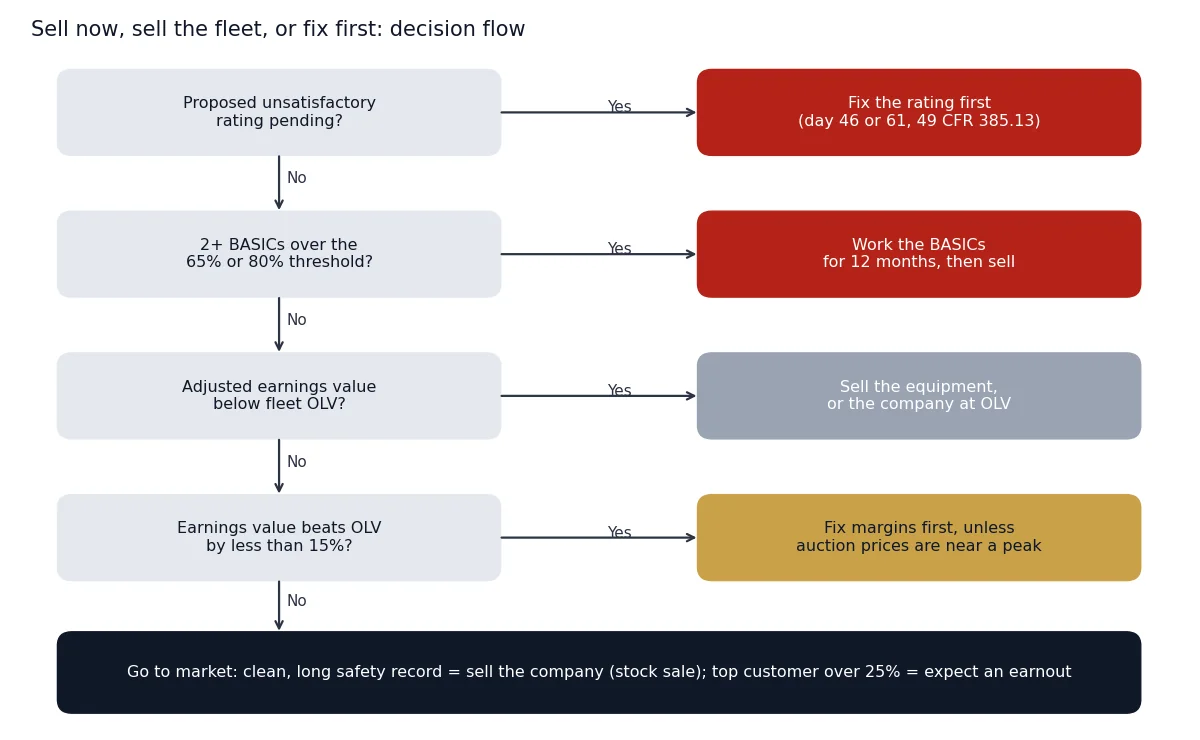
Compare your adjusted earnings value with the fleet’s orderly liquidation value, then check your safety position and customer mix. The table turns those comparisons into rules with thresholds; the flowchart holds the same logic. A fix usually takes 12 to 24 months.
| If your situation is | Then | Why |
|---|---|---|
| If a proposed unsatisfactory rating is pending | Fix the rating first with a corrective action plan | Operations stop on day 46 or 61 (49 CFR 385.13) |
| If 2+ BASICs sit above the 65% or 80% threshold | Work the BASICs for 12 months before going to market | Institutional buyers walk or re-trade |
| If adjusted earnings value is below fleet OLV | Sell the equipment, or the company at OLV | The going concern adds nothing above the iron |
| If earnings value beats OLV by less than 15% | Fix margins first, unless auction prices are near a peak | Little goodwill to defend (CT estimate) |
| If one customer is over 25% of revenue | Expect an earnout, or diversify for 12 to 18 months | Price tied to that customer |
| If you hold broker authority with real net revenue | Value the brokerage separately | Higher asset-light multiple |
| If your safety record is long and clean | Sell the company (stock or membership sale) | Buyer skips the 18-month new entrant clock |
Selling a trucking business? Talk to an M&A advisor first.
We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells. A 15-minute call tells you what your fleet could sell for in the current freight market and which buyer types fit your size and segment. Try our trucking valuation calculator for a starting range first if you prefer.
For the sale process, see how to sell a trucking company; for who is buying across freight, 3PL and brokerage, see logistics mergers and acquisitions in 2026. Towing owners can use our towing business valuation guide.
Want to know what your trucking business is worth?
Benchmarks give you a range. A 15-minute confidential call gives you a real number, based on what active buyers are paying right now and which ones would compete for your business. No cost, no obligation.
How we compiled this
We compiled this page in November 2026 from 13 primary documents: the BizBuySell benchmark, ATRI’s July 2026 release, J.D. Power’s August 2026 guidelines, FMCSA’s SMS methodology, 2024 SMS notice and 2013 transfer interpretation, five provisions of 49 CFR, RXO’s Coyote release and IRS Form 8594 guidance. Other deal terms, ATRI line items and Cass data come from linked trade press. We excluded forum posts. The adjustment ranges and the worked example are CT Acquisitions estimates (illustrative).
Frequently asked questions
How much is a trucking company worth?
Most owner-run trucking companies sell for 2.35x to 3.75x seller’s discretionary earnings, the middle half of BizBuySell’s sold listings. A carrier with the median $400,000 of SDE would price at $940,000 to $1,500,000. If the fleet’s orderly liquidation value is higher, it sets the floor; equipment debt is paid from either number.
How can I value a trucking company?
Rebuild two years of SDE or EBITDA, apply a multiple band, and adjust it for fleet age, customer concentration, CSA scores and driver model. Compare the result with an appraiser’s orderly liquidation value for the fleet, take the higher figure and subtract equipment loans and leases, as the 20-truck example on this page shows.
How much is a business worth with $1,000,000 in sales?
For a trucking company, BizBuySell’s 0.65x average revenue multiple points to about $650,000. Earnings give a better check: at the 20.5% ratio of BizBuySell’s median owner earnings to median revenue, $1,000,000 of sales implies about $205,000 of SDE, worth $481,750 to $768,750 at 2.35x to 3.75x. Replace the 20.5% with your own margin first.
How much is a business worth that makes $300,000 a year?
If $300,000 is seller’s discretionary earnings, a trucking company at BizBuySell’s middle-half multiples of 2.35x to 3.75x is worth $705,000 to $1,125,000, and $900,000 at the 3.00x average. An old fleet, a top customer above 25% of revenue or CSA alerts pull it lower; equipment debt is paid from the price.
Is a trucking business worth 3 times profit?
Roughly, if profit means seller’s discretionary earnings: BizBuySell’s average for sold trucking companies is 3.00x SDE. Larger carriers priced on EBITDA earn higher multiples. For an asset-heavy carrier, also compare the result with the fleet’s orderly liquidation value and subtract the fleet debt the sale must pay off.
Can I sell my trucking company’s MC number or authority?
Sell it with the company. In a stock or membership-interest sale, the USDOT number and MC authority stay with the entity the buyer acquires. FMCSA stopped reviewing and approving authority transfers on October 22, 2013, and a buyer under a new USDOT number faces 18 months of new entrant monitoring under 49 CFR 385.307.
Sources
- BizBuySell, Trucking Company Valuation Benchmarks, accessed November 2026.
- ATRI cost release, July 15, 2026.
- FreightWaves on ATRI line items, July 15, 2026.
- FreightWaves on the Cass Freight Index, October 13, 2026.
- J.D. Power Commercial Truck Guidelines, August 2026.
- FMCSA, Safety Measurement System methodology, accessed November 2026.
- FMCSA, SMS enhancements notice, 89 FR 91874, November 20, 2024.
- FMCSA, Transfers of Operating Authority, 78 FR 52457, August 23, 2013.
- 49 CFR 385.13, 385.307, 387.9, 387.307 and Part 376, accessed November 2026.
- RXO Coyote release, September 16, 2024.
- FreightWaves on Knight-Swift and U.S. Xpress, July 2023.
- CDLLife on TFI and Daseke, April 2024.
- IRS, About Form 8594, accessed November 2026.
About the Author
Christoph Totter is the founder of CT Acquisitions, an M&A advisory firm headquartered in Sheridan, Wyoming, that helps owners of founder-owned businesses make the most of their exit through a confidential sale, a recapitalization or exit planning, with a network of 500+ buyers: search funders, family offices, lower middle-market PE and strategic consolidators. We work for owners on the sell side. Our fee is success only: nothing upfront, and you pay nothing unless the business sells. Connect on LinkedIn · Get in touch
Related Guide: SDE vs EBITDA: Which Metric Matters for Your Business, How trucking sellers should report earnings, and why it changes valuation.
Related Guide: Buyer Archetypes: PE, Strategic, Search Fund, Family Office, How each trucking buyer underwrites differently and what they pay for.
Related Guide: 2026 LMM Buyer Demand Report, Aggregated buy-box data from 76 active U.S. lower middle market buyers.
Related Guide: Business Valuation Calculator (2026), Quick starting-point valuation range based on SDE/EBITDA and segment.
Related Guide: Selling a Business Under $1 Million, Buyer pool, multiples, and process for sub-LMM exits.
Want a Specific Read on Your Business?
15 minutes, confidential, no contract, no cost. You leave with a read on your local buyer market and a likely valuation range.
